My mother used to tell us that you can tell how much someone believes in something by how much they still back it after it disappoints them.
Wells Fargo analyst Aaron Rakers, ranked 5th out of 12,523 Wall Street analysts on TipRanks with a 73% success rate, has just demonstrated exactly that kind of conviction. Aaron cut his Micron stock price target, yes, but then raised his earnings estimates.
That combination tells a story about where the memory market is heading into Micron’s fourth-quarter earnings on Sept. 30. And it is not the bearish one the headline number might suggest.
Micron Technology (MU) reached an all-time closing high of approximately $1,213.37 in June 2026, driven by massive AI-fueled demand, stellar earnings, and long-term strategic customer agreements
Currently, MU trades around $1,075, up 281.92% year-to-date (YTD) and 555.70% over the past year, according to Yahoo Finance. This is after it hit an all-time high of $1,255 on June 25 before pulling back.
Slickcharts shows that it is the fourth-best S&P 500 performer YTD, trailing only SanDisk, Moderna, and Dell.
Also Read: Micron Technology Inc. Latest News
What Rakers actually did and why both numbers matter
Wells Fargo lowered its Micron price target to $1,400 from $1,525 while maintaining an Overweight rating, according to a note shared with TheStreet. I know the 8% cut in the target sounds like bad news. But the rest of the note has a different story.
Wells Fargo simultaneously raised its fiscal 2027 EPS estimate by approximately 5% and its fiscal 2028 estimate by more than 10% compared to prior forecasts.
The firm now projects fiscal 2027 revenue of $261.3 billion with EPS of $166, and fiscal 2028 revenue of $287.8 billion with EPS of $178. Both estimates sit roughly 5% above Street consensus for those years.
More on Micron
- History of Micron: The story behind the computer memory giant
- Micron Technology’s stock buybacks explained
- Who owns Micron Technology? A look at its top investors
I know investors will keep debating whether Micron’s peak earnings are both real and sustainable. That uncertainty can weigh on the valuation multiple the stock commands, even as the underlying earnings trajectory continues to improve.
That is a different problem than “the business is weakening.” It is “the market will need more convincing before it pays full value.”
Wells Fargo also estimates that Micron’s free cash flow will exceed $125 billion annually, with 100% shareholder returns beginning in Dec. 2026. That figure alone tells you what Rakers thinks the business looks like on the other side of this debate.
Micron’s earnings setup heading into earnings
Micron guided fiscal Q4 2026 revenue of $50 billion, plus or minus $1 billion, with a non-GAAP gross margin of approximately 86%, according to a company statement.
Those numbers would represent another enormous sequential step from the Q3 results I covered earlier.
For context:
- Q3 fiscal 2026 showed DRAM revenue of $31.3 billion, up 343% year over year (YOY)
- NAND revenue hit $9.9 billion, up 361%YOY
- Data center revenue exceeded $25 billion for the quarter, an annualized run rate above $100 billion.
- HBM4 shipments crossed $1 billion in revenue.
- Source: Micron Q3 Fiscal 2026 Results
What Wall Street thinks of Micron
- JPMorgan raised its price target to $1,540 from $550 while maintaining an Overweight rating.
- BofA reiterated a Buy rating and $1,550 price target.
- Stifel maintained a Buy with a $1,500 target, citing expectations for Micron to exceed consensus in both Q4 and Q1 fiscal 2027, with supply agreements providing revenue support even amid near-term shipment constraints.
- TD Cowen holds a $1,600 Buy target and describes the company as “mid-cycle in demand growth.”
- Susquehanna sits at the high end of the range with a $2,000 target, citing structural AI-driven memory tightness.
- Citi raised its target to $1,300 from $1,150, projecting worsening undersupply through 2031 driven by AI demand.
- The Lynx Research note I reported on Sept. 8 set a $1,325 target, framing Micron as “primed for a breakout to the upside”
The bigger Micron story behind the numbers
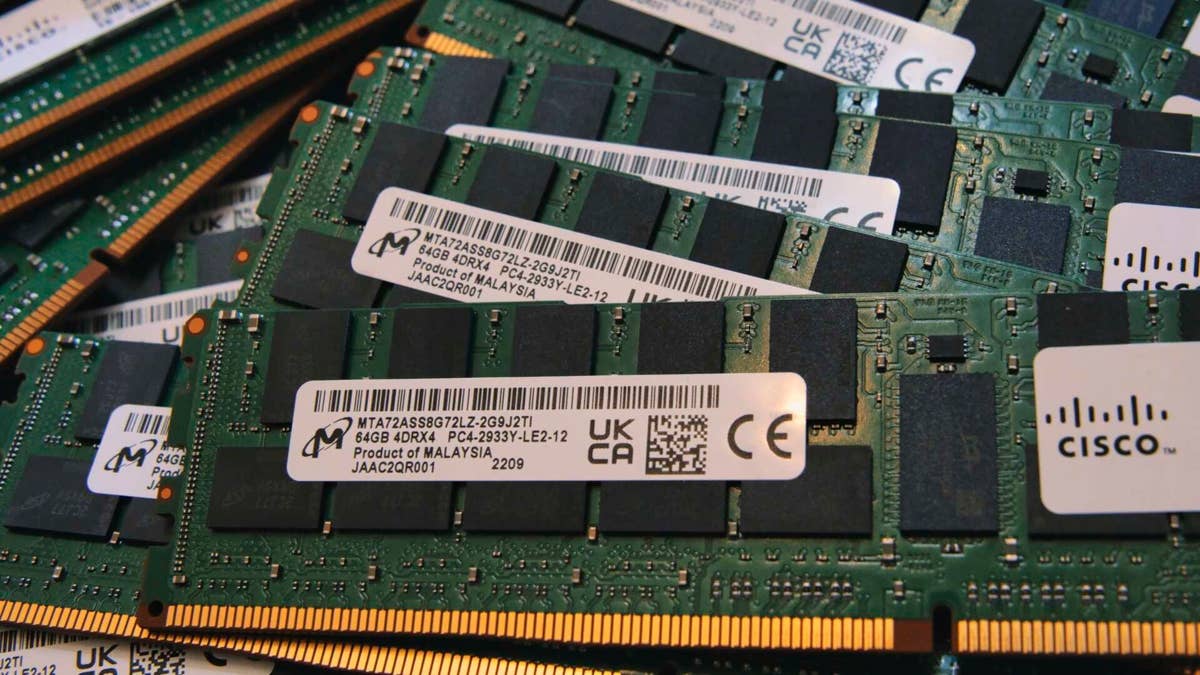
Every person who uses an AI assistant, every company deploying AI agents, every data center humming with GPU workloads is creating demand for the memory Micron makes.
HBM4 — the stacked memory that sits directly inside Nvidia’s most powerful AI chips — is sold out through 2027 and into 2028, according to TheStreet.
The supply agreements Micron has been signing are multi-year commitments that turn what was once a volatile commodity cycle into something closer to contracted infrastructure revenue.
Wells Fargo’s through-cycle EPS estimate of $75 to $90 and gross margin in the low-to-mid 70% range reflects what the baseline business looks like even in a weaker year.
The $166 and $178 EPS projections for fiscal 2027 and 2028 show what Micron’s earnings power could look like during the current AI infrastructure supercycle.
That gap is at the heart of the debate Rakers identified, and it explains why the price target fell even as earnings estimates moved higher. The market will eventually resolve that debate with a multiple. So, Sept. 30 is the next data point in that resolution.
Related: Micron, SanDisk get new aggressive price targets from top analyst