I rarely see double-upgrades from Wall Street. JPMorgan analyst Richard Choe moved an AI stock directly from Underweight to Overweight on Sep. 14, skipping a neutral rating entirely, in a note shared with TheStreet.
JPMorgan may have underestimated this one. Now it’s slamming the brakes, making a U-turn and hitting the gas.
The double-upgrade is JPMorgan’s second such move in the AI-adjacent space in recent months. The bank made the same jump with Circle Internet Group, a fintech and digital financial services company tied to the growing stablecoin economy in Nov. 2025, Yahoo Finance reported.
Before that, Lanxess, a German specialty chemicals maker, got the double upgrade in March 2026.
Now IREN gets the same dose, with JPMorgan upgrading from Underweight to Overweight and raising its price target to $65 from $46, a 41% increase.
IREN Limited (IREN) trades at $43.17, up 14.30% year-to-date and 27.12% over the past year, according to Yahoo Finance. The three-year return is an aggressive 761.68%.
We can attribute that massive explosion to the impact of the company’s pivot from Bitcoin mining to AI cloud infrastructure on long-term shareholders. Choe’s reasoning comes down to one word, and it is a good one: Nvidia.
Also Read: IREN Limited Latest News and Stories
What actually drove the IREN double-upgrade
JPMorgan’s upgrade rests on a specific structural development that transformed IREN’s competitive positioning.
IREN secured a five-year partnership with Nvidia worth around $5.5 billion. The deal is worth approximately $3.4 billion over five years, and also granted Nvidia a five-year option to buy up to 30 million ordinary shares at $70 each, representing up to $2.1 billion in conditional investment rights. Both total down to $5.5 billion.
IREN also achieved “Exemplar Cloud” status on the Nvidia GB300 NVL72 system, according to IREN disclosures.
I take that designation as Nvidia’s validation that IREN’s infrastructure meets the highest standards for deploying its most advanced GPU systems.
More Wall Street:
- J.P. Morgan nears $1 trillion, but your gains hinge on 1 office
- Morgan Stanley warns of possible stock market correction
- JPMorgan resets Lululemon stock price target by 38%
Beyond Nvidia, IREN has been stacking contracts across the AI ecosystem: Microsoft receiving the first Horizon 1 deployment, Cohere, Prometheus, Perplexity, Figure AI, Fal AI, and Higgsfield AI signed, plus a new multi-year contract with an undisclosed leading frontier AI lab, according to IREN’s fiscal year 2026 results.
Customer prepayments on recent contracts cover 45% to 55% of GPU capital expenditure, meaning customers are partially funding IREN’s buildout.
JPMorgan also flagged the pricing shift. AI compute services are now fetching $15 to $20-plus per watt, up from the prior $10 to $15 range.
The same fiscal year 2026 report notes that the recent three-year contracts are priced above $20 million in revenue per megawatt, with active discussions at approximately $25 million per megawatt.
This business transition justifies the upgrade
The scale of what IREN has accomplished in fiscal year 2026 is the foundation beneath JPMorgan’s conviction.
- AI Cloud Services revenue grew 8x to $128.8 million in FY26 (versus FY25 $16.4m)
- Raised its 2026 contracted annualized run-rate revenue (ARR) guidance to $4 billion
- 2026 ARR capacity is largely sold out
- Late-stage customer discussions are underway for a significant portion of 2027 capacity, with 2028 financing and customer discussions progressing in parallel.
- Source: IREN’s FY26 Results
The capital structure behind the expansion is notable for its scale and efficiency. IREN secured $3.6 billion in investment-grade GPU financing for the Microsoft contract at 6.0%, funding 96% of the associated GPU capital expenditure together with customer prepayments.
A separate $2.8 billion in GPU financing from Blue Owl and PIMCO at 9.0% supports non-investment-grade customer deployments. Total committed capital, including cash, GPU financing, and prepayments, reached $14 billion.
Management committed to winding down all Bitcoin mining by December 2026, eliminating the strategic ambiguity that has historically weighed on investor perception of the business.
“We have spent years assembling what is difficult to replicate: power, land, data centers, compute, software and people,” said Co-CEO Daniel Roberts in the earnings commentary. “This is only the beginning.”
The deployment roadmap and why the physical infrastructure is the real deal
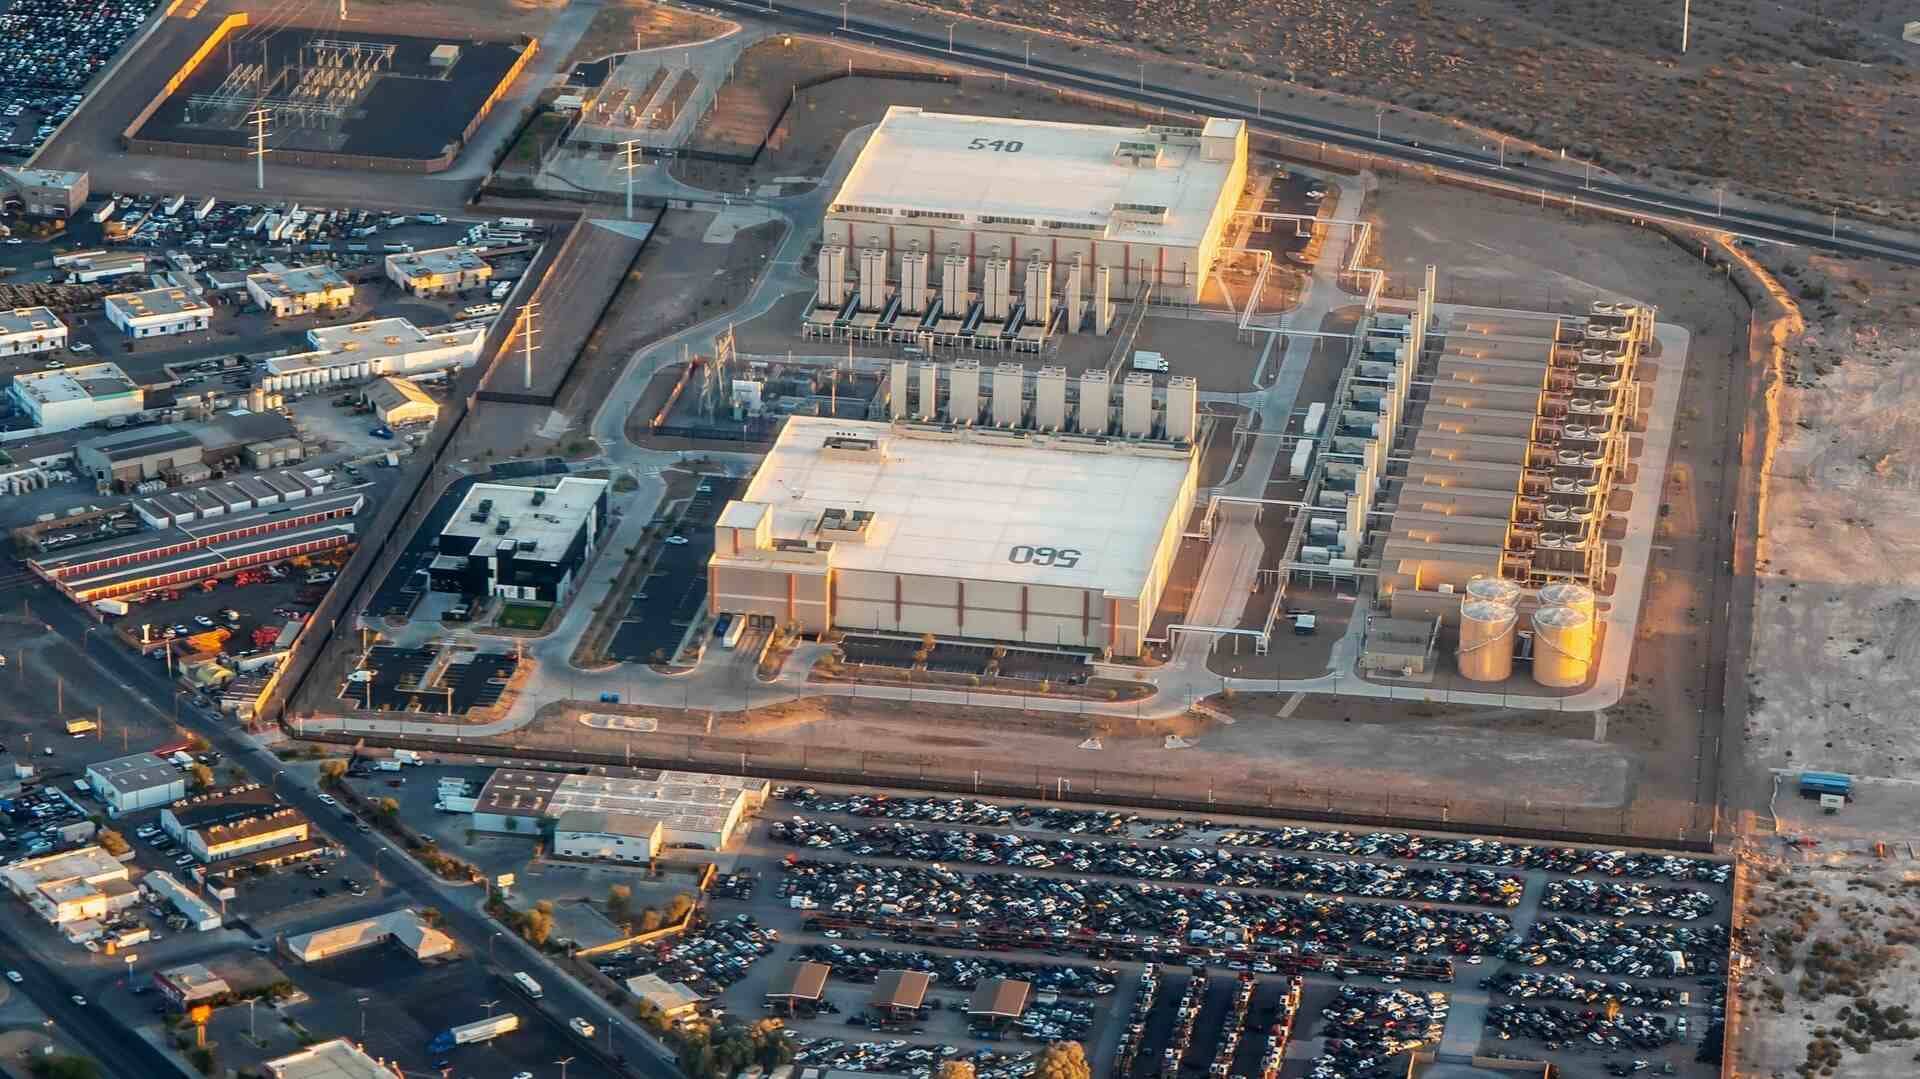
Competitors rent data center capacity. IREN owns the land, electrical grid interconnections, and physical data centers outright across North America, Europe, and the Asia-Pacific region. That all-around ownership structure gives it cost management advantages and capacity control that asset-light competitors cannot replicate.
The deployment targets are aggressive: 0.3 gigawatts of IT capacity in 2026 and 0.8 gigawatts in 2027, with additional liquid-cooled deployments planned at Mackenzie, Canal Flats, and Prince George in 2027, IREN reported.
Global expansion is progressing at Sweetwater in Texas, Kiowa in Oklahoma, Bundey in Australia, and Badajoz in Spain.
Horizon 1, the first of four 50-megawatt liquid-cooled GPU deployments at Childress, has been delivered to Microsoft. Horizon 2 is already in commissioning, while Horizons 3 and 4 are in late-stage construction and targeted for delivery in Q4 2026. That’s a serious buildout.
The net cash position, existing GPU financing commitments, and contracted customer prepayments give IREN approximately $14 billion in available capital to fund the buildout. That removes the near-term dilution risk that has historically constrained smaller AI infrastructure companies.
At $43 against a $65 price target from a firm that just skipped neutral entirely, JPMorgan’s conviction is visible. Also, the 2026 capacity ramp and the Q4 Horizon deliveries are likely to show up in the financial results sooner or later.