Drivers, travelers, and households continue to feel the crippling effects of the oil shock, even as the immediate disruption around the Strait of Hormuz starts to ease.
Saudi Aramco CEO Amin Nasser is warning that the global oil market has lost much of the buffer that normally helps keep fresh supply problems from quickly spilling into fuel prices and everyday costs, as reported by Seeking Alpha.
Since the Iran war began, nearly 3 billion barrels of oil supply have been lost, while about 1 billion barrels have been drawn from global stocks.
Depleted inventories leave less room to absorb the next disruption. Even if shipping flows improve, governments and energy companies would still need to rebuild those reserves while continuing to meet normal demand.
The bigger issue, then, is not just whether supply returns. It is how quickly the market can rebuild its safety cushion.
Aramco’s warning is really about what happens after the oil crisis
Nasser is essentially arguing that even if the immediate geopolitical shock from disruptions in the Strait of Hormuz eases, the oil market wouldn’t return to normal as quickly as is commonly perceived.
Speaking at the Energy Intelligence Forum in London, he said the world entered the crisis with almost 10 billion barrels of oil stocks.
Since the Iran war began, nearly 3 billion barrels of gross oil supply have been lost, while more than 1 billion barrels have been pulled from inventories to cushion the disruption.
More Oil & Gas:
- Goldman Sachs doubles down on oil price forecast for 2026
- Drivers lose control over gas price squeeze
- A big shift in the U.S. energy market is about to happen
Aramco now estimates that less than 6 billion barrels of commercial inventories remain, with much of that oil not practically available because some stocks are needed to keep pipelines, terminals, and other infrastructure operating.
The “scarily thin” argument is that 100 million barrels of emergency crude and diesel that the G7 recently agreed to release may soften the immediate squeeze.
Nasser’s assessment, however, was much harsher: “Emergency reserves might buy us a winter. They cannot fix long-term supply.”
Nasser also said rebuilding depleted inventories while simultaneously satisfying normal consumption could take up to two years. He also argued that without Saudi Arabia’s East-West pipeline, which bypasses Hormuz, Brent could have reached $200 a barrel.
It’s important, though, for investors to understand that flow recovery isn’t stock recovery.
Middle Eastern shipments are already recovering.
Gulf oil flows, excluding Iran, averaged about 81% of pre-war levels in September, while crude and condensate exports recovered to roughly 91%, as reported by Reuters. Yet refined-product exports were only around 60% of pre-war levels.
That helps explain why Brent can hover around $100 even while diesel and other fuels remain exceptionally expensive.
The refining side may actually be the bigger problem. Kuwait Petroleum CEO Shaikh Nawaf Al-Sabah estimates that the Iran war has left the world short roughly 6 million barrels a day of refined products. He warned that there simply is not enough spare refining capacity elsewhere to compensate for shuttered Gulf facilities.
U.S. data reinforces that point.
American diesel inventories fell to 107.9 million barrels in September, the lowest seasonal level in records dating back to 1982, while retail diesel prices climbed above $6 a gallon, according to Binance.
That said, I interpret Nasser’s warning as bigger than a call for $150 oil. The market has burned through much of its safety cushion, which makes the next disruption potentially more painful.
And even when supply normalizes, I think rebuilding inventories could create another source of demand that markets are underestimating.
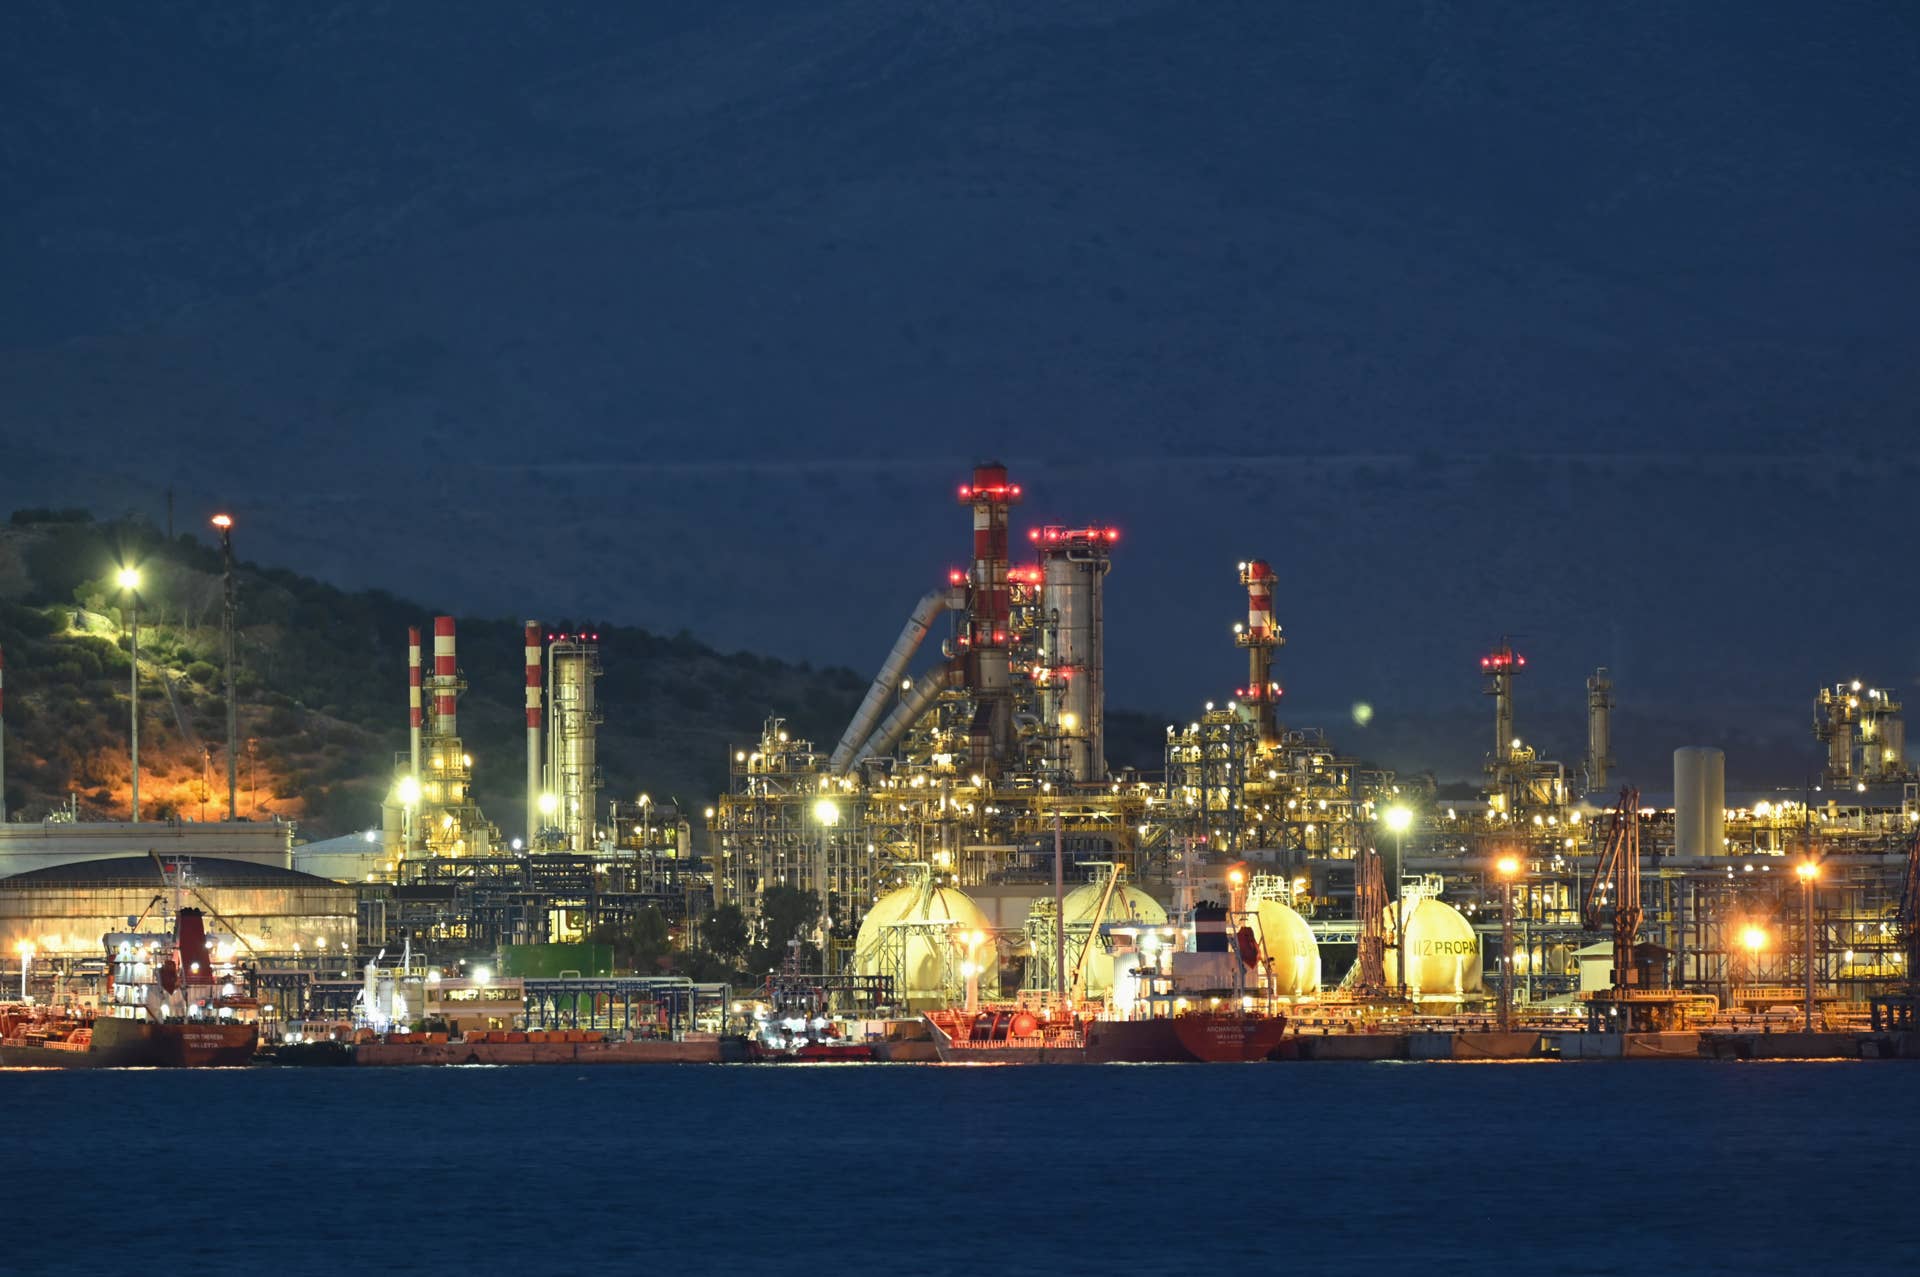
Wall Street still sees room for Brent to cool from here
Using Brent at around $99.49 a barrel on Oct. 6 as the comparison point, most major banks still expect oil prices to ease from current levels even as Middle East risks keep the market volatile.
Here are the latest publicly reported forecasts:
- Morgan Stanley: $100/bbl in Q4 2026, roughly 0.5% upside from current Brent. It also sees $95 in Q1 2027 before prices ease further.
- UBS: $95/bbl by year-end 2026, about 4.5% downside. UBS sees $90 by March 2027 and $85 by mid-2027.
- Bank of America: $95/bbl by year-end, about 4.5% downside. Its base case is much calmer than its stress scenario, which could send Brent above $150 if supply disruptions worsen materially.
- HSBC: $95/bbl for Q4 2026, about 4.5% downside, with $85 forecast for 2027.
- Goldman Sachs: $85/bbl by December 2026, implying roughly 14.6% downside, followed by about $80 in 2027.
- J.P. Morgan: $78/bbl at year-end 2026, around 21.6% downside, with its July framework pointing to roughly $64 on average in 2027.
- Citi: $70/bbl in Q4 2026, about 29.6% downside, and $65 on average in 2027.
Chevron, ConocoPhillips, and even United are preparing for a tighter oil world
Nasser is not alone, and executives at major U.S. companies have been talking about the same scenario.
Chevron (CVX) CEO Mike Wirth delivered an unusually similar message, as reported by Reuters on Oct. 6, saying that the global energy system is now more fragile than it was earlier in the Iran conflict, with crude and refined-fuel buffers continuing to shrink.
Wirth had already warned in September that the mechanisms that restrained crude earlier in the conflict had largely been exhausted: “I think the risks remain to the upside over the next few months.”
To me, Chevron and Aramco are describing essentially the same vulnerability from different market positions. Inventories absorbed the first shock, but they cannot absorb shocks indefinitely.
ConocoPhillips (COP) is somewhat less alarmist, but its former CEO and current executive chairman, Ryan Lance, is also arguing for a structurally higher price floor, as reported by Reuters. Lance said he sees WTI’s floor moving toward $70 a barrel, with a longer-run mid-cycle level of roughly $65 to $70.
But Lance also identified the longer-term problem. “The real strategic question for companies like mine is where the conventional production is going to come from,” he said.
Occidental Petroleum (OXY) CEO Vicki Hollub made a related argument even before the Iran shock intensified, saying in February that U.S. producers would need oil at roughly $70 to continue growing output, as BOE Report noted.
Moreover, the implications are already spilling well beyond Big Oil.
United Airlines (UAL) CEO Scott Kirby told employees in March that the carrier was preparing for Brent to reach as much as $175 a barrel and potentially remain above $100 through the end of 2027, according to Reuters.
At those levels, Reuters calculated United’s annual fuel bill could increase by roughly $11 billion.
I think United is particularly useful confirmation because an airline has the opposite economic exposure of Aramco.
Saudi Aramco generally benefits from expensive crude; airlines generally do not. When companies on both sides of the barrel are preparing for prolonged tightness, I pay closer attention.
What I think this means for consumers and investors
For consumers, I would watch diesel before obsessing over Brent.
Crude gets the headlines, but diesel moves trucks, farm equipment, construction machinery, and much of the industrial economy, while jet fuel feeds directly into airline costs. When those fuels stay expensive, the impact spreads through shipping, groceries, airfare, and manufactured goods.
That pressure is already visible.
U.S. diesel recently reached about $6.50 a gallon, while airlines have cut less-profitable routes as fuel costs rise. The U.S. services sector is also seeing its strongest input-cost pressures since 2022, with energy a major driver.
For investors, I see a more complicated setup than simply “oil stocks go up.” Higher prices can boost cash flow for Exxon, Chevron, and ConocoPhillips, while refiners can benefit from strong margins. But $100-plus Brent is not guaranteed to last as Gulf exports recover and strategic reserves are released.
What changes my view is the lack of cushion. Even if Hormuz normalizes, depleted inventories still need to be rebuilt.
I would watch throughput, diesel stocks, refinery availability, and reserve replenishment closely. To me, that keeps energy a macro risk well into 2027.
Related: ‘Bond King’ issues stunning warning to stock market investors