Marvell Technology (MRVL) stockholders just got a powerful signal from Bank of America after the chipmaker’s Analyst Day, with a sizeable price target bump and an upgrade to key forecasts as management laid out a much bigger long-term growth story.
After the event, the bank believes Marvell’s networking, optics, storage, and custom-compute portfolio could give it a much larger role in the AI infrastructure buildout than the market has been pricing in.
For perspective, Marvell stock has been a tremendous wealth compounder for investors, unlike the broader, choppier AI trade, returning 235% year to date compared with the S&P 500’s 14% gain, according to Seeking Alpha.
BofA’s analysts, in a note shared with me, said the event solidified their view of Marvell’s ability to outgrow its end markets, as hyperscalers spend more on custom silicon and high-speed interconnects.
That said, the unanswered question is whether Marvell can convert that broader opportunity into the kind of sustained earnings growth now embedded in BofA’s revised outlook.
Marvell Investor Day: What investors need to know
Marvell’s Oct. 6 Investor Day materially raised the long-term bar for the company, which prompted BofA and other banks to raise their price targets and forecasts.
- Management bumped its FY2028 revenue outlook to about $20 billion and laid out a new $70 billion to $90 billion FY2031 revenue target, with $80 billion at the midpoint.
- Marvell now sees a roughly $400 billion addressable market by 2030, about four times its previous estimate of opportunity.
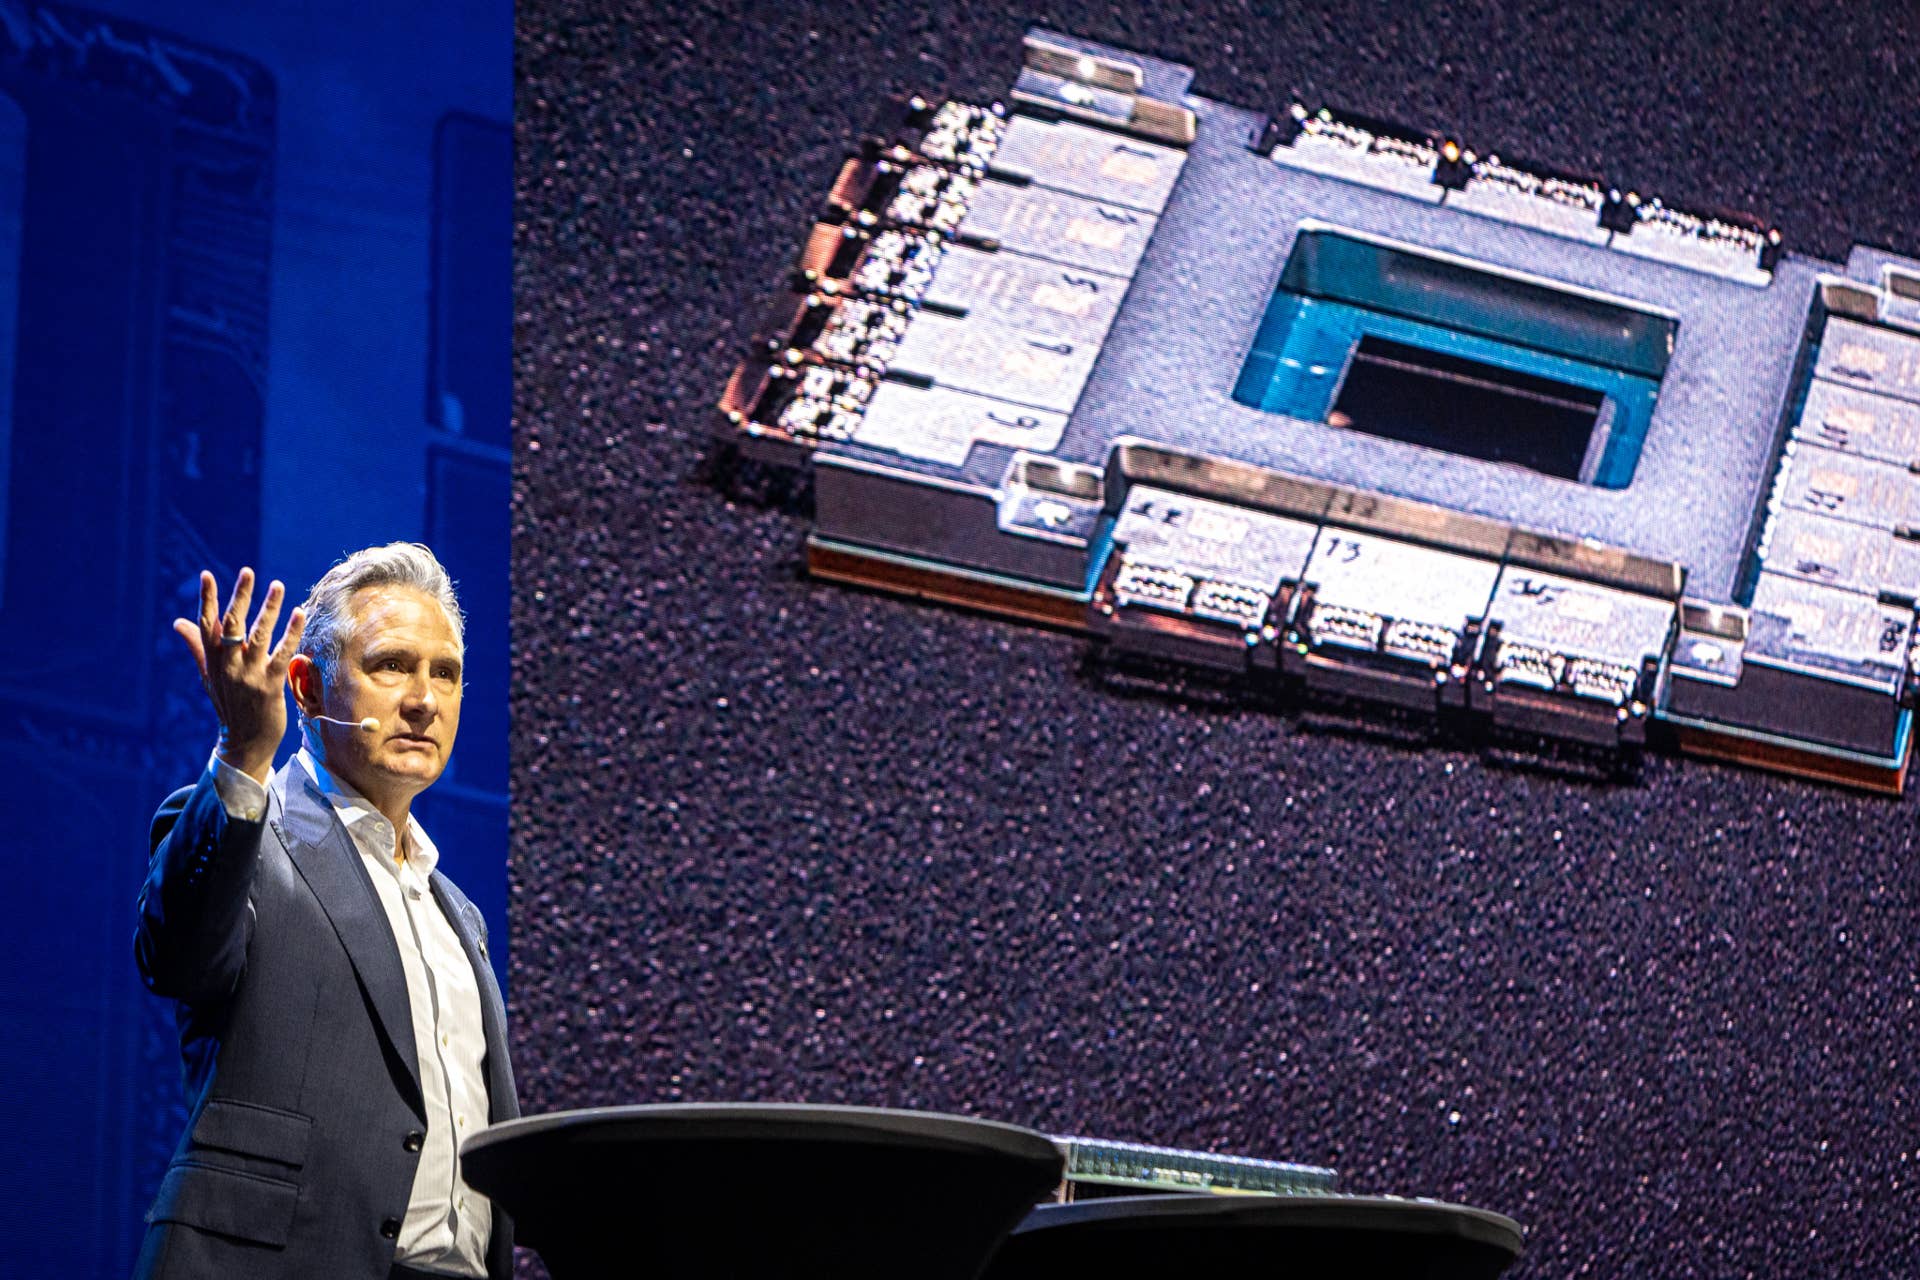
- CEO Matt Murphy emphasized that the outlook is bottom-up: “All of this is grounded in the business we have today, our customer positions, and the opportunities that are already right in front of us.”
Bank of America sees Marvell’s AI opportunity getting much bigger
Bank of America came out of Marvell’s Analyst Day with a Buy rating, a $400 price target, and a far more aggressive long-term earnings outlook. Against the report’s reference price of $271.25, that target implies roughly 47.5% upside.
The standout point for me is that BofA is not basing the call on a single product cycle. The thesis is that Marvell’s mix of custom compute, interconnect, switching, storage, and communications gives it exposure across multiple layers of AI infrastructure, rather than relying on a single semiconductor category.
More Tech:
- Anthropic-powered AI model sends shocking message to employee
- Rocket Lab clears 1st hurdle in its biggest satellite deal
- Apple’s $54 billion iPhone machine may be about to break its biggGest ritual
Moreover, BofA raised its 2028 revenue estimate to $20.09 billion from $18.01 billion and its 2029 estimate to $34.84 billion from $28.50 billion. EPS forecasts were raised to $7.59 from $6.60 for 2028 and to $13.92 from $11.02 for 2029.
I think the biggest change is scale.
Marvell now sees a roughly $400 billion total addressable market by 2030, versus about $104 billion previously, and is targeting $70 billion to $90 billion in sales, with an $80 billion midpoint. BofA said that could support $32-plus in EPS by 2030, far above the current consensus.
The bank also sees additional upside from Google’s TPU ecosystem.
Marvell’s XPU attach opportunity could benefit from growth in Google TPU units, as well as broader adoption by other hyperscalers. Specifically on the Google opportunity, the bank estimates that the tech giant could ship 12 million to 13 million TPUs in 2028 and 15 million to 20 million-plus by 2030, creating a sizable attach opportunity for Marvell.
BofA also expects Google-parent Alphabet (GOOGL) to represent less than half of Marvell’s XPU attach sales over time.
BofA also points to Amazon (AMZN) AWS Trainium and Microsoft (MSFT) Maia as important future ramps.
To me, the core argument is simple: Marvell might be evolving from a strong AI networking supplier into a much broader beneficiary of compute infrastructure, and BofA now expects earnings growth to accelerate with that shift.
Marvell’s upside is compelling, but execution has to catch up
My takeaway is that Marvell now has a much stronger long-term AI story, but the stock also gives investors less margin for any missteps.
At BofA’s reference price of $271.25, Marvell trades at roughly 64.7 times 2027 earnings, falling to 35.7 times 2028 earnings and 19.5 times 2029 earnings.
That rapid compression matters because, in my view, the pricing setup becomes much easier to defend if BofA is right that earnings can rise from $4.19 in 2027 to $13.92 in 2029.
The risk is that those numbers depend on a very large AI infrastructure buildout actually arriving on schedule. BofA specifically highlights constraints around power, land, and data-center shells, all of which could slow hyperscaler deployments.
Competition is another concern.
Marvell faces internal chip teams at major cloud customers, rival ASIC suppliers such as Broadcom (AVGO), and Taiwan-based competitors, and merchant silicon from Nvidia (NVDA). There is also uncertainty about the economics of Marvell’s expanded relationship with Google and how much dilution could ultimately result from the associated warrants.
I would therefore treat Marvell as a growth-at-a-price story rather than a straightforward value play.
Investors already owning the stock should, in my view, focus on custom-silicon ramps, interconnect growth, and evidence that hyperscaler spending remains on schedule.
For new money, I would be more selective about entry points. The long-term opportunity looks substantially larger after Analyst Day, but at today’s valuation, Marvell needs to keep converting that opportunity into real revenue and earnings growth.
Related: Goldman Sachs revamps SpaceX stock estimates before crucial earnings test