Nobody budgets for the worst day of their life.
You plan for the car payment, the mortgage, and the kids’ activities. You don’t plan for the ambulance ride, the surgery, or the months you can’t work.
That’s the trap. A serious injury is a financial event as much as a medical one, and the money damage often outlasts the hospital stay by years.
Most households don’t have much of a cushion. Only 63% of adults would cover a $400 emergency with cash or its equivalent, according to the Federal Reserve‘s latest household well-being report, released May 13. Everyone else would borrow, sell something, or fall behind.
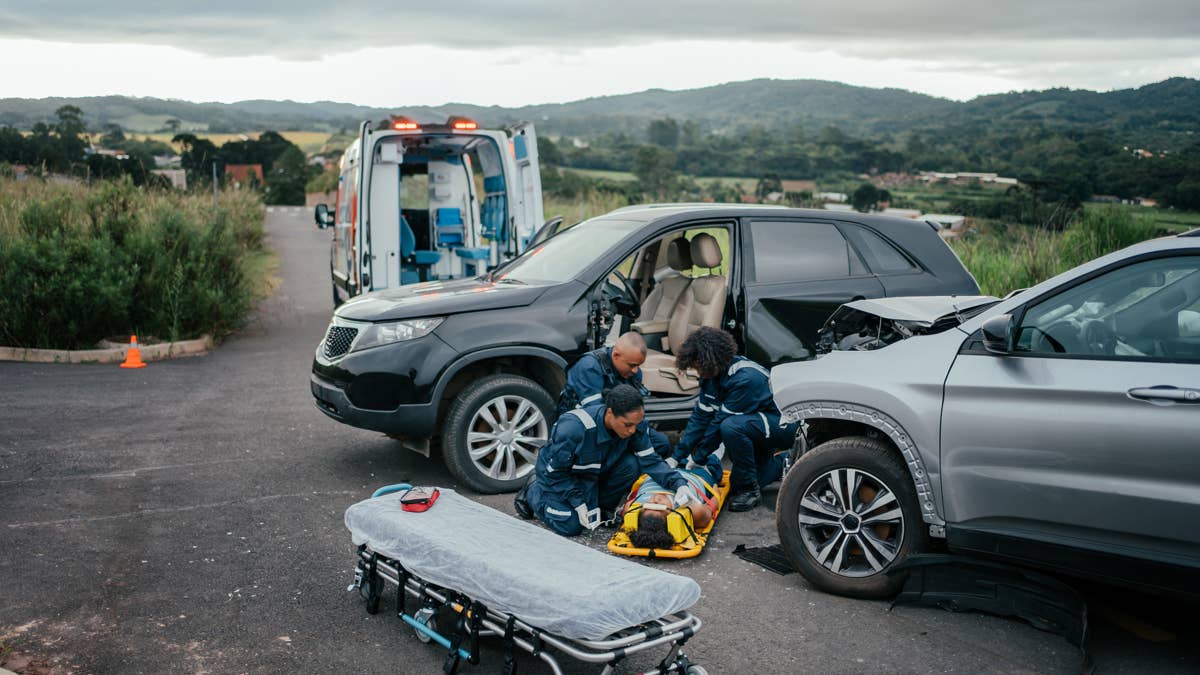
A $400 car repair is one thing. A trip to a trauma unit after a wreck on I-285 is another, and the costs from that kind of day can run well into six figures.
Now set that against what a serious crash injury really costs. A disabling or incapacitating crash injury carries an average economic cost of $174,000, according to the National Safety Council‘s 2024 estimates. That covers lost wages and productivity, medical bills, administrative costs, and vehicle damage.
In Georgia, the minimum auto policy pays $25,000 per injured person, according to the Office of Insurance and Safety Fire Commissioner.
The average cost runs nearly seven times that coverage, a gap of roughly $149,000. In my analysis, it’s the number every Atlanta family should know before an accident, not after one.
The bills that show up first after a serious injury
Medical care is the obvious hit. Emergency transport, trauma care, surgery, imaging, and prescriptions stack up fast, and even good health insurance leaves you with deductibles, co-pays, and out-of-network charges.
Rehab keeps the meter running. Physical therapy, occupational therapy, and mental health care can stretch for months or years.
Some injuries also require home modifications, mobility equipment, or long-term nursing help. Those costs rarely appear in the first round of bills, but they can end up being the heaviest.
Related: Your bigger accident settlement could leave you with less
The national toll is staggering. Injuries cost the U.S. $4.2 trillion in 2019, including $327 billion in medical care, according to the Centers for Disease Control and Prevention. Nonfatal injuries alone accounted for about $2 trillion across nearly 26 million cases.
Much of that cost lands on household balance sheets. At least 20 million adults owed more than $250 in medical debt, and about 3 million owed more than $10,000, according to the Peterson-KFF Health System Tracker, which analyzed federal survey data from the end of 2021.
Why a lost paycheck can sting more than the hospital
Lost income is the cost families most often underestimate. You may miss weeks or months of work, and a spouse or parent may cut hours to care for you.
I ran the numbers on a simple case. If you earn $60,000 a year and miss three months, that’s about $15,000 in gross pay gone, before a single medical bill arrives.
Self-employed workers and gig drivers have it worse, since many have no paid leave at all. And if an injury keeps you from returning to the same job, the loss can follow you for decades as reduced earning power.
More Healthcare:
- Your health insurance may not protect your finances
- Paying cash for U.S. medical care could save you a fortune
- Medicare goes after hospital markup you’ve paid for years
That risk is less rare than it sounds. More than one in four of today’s 20-year-olds will become disabled before reaching retirement age, according to the Social Security Administration.
Then come the quiet costs. Child care, rides to appointments, meal delivery, cleaning, and yard help all add up when you can’t manage daily tasks.
Credit card balances climb once savings run dry, and interest compounds the strain. Chronic pain, anxiety, and post-traumatic stress can also hit your work and relationships, even though those harms are hard to price.
How Georgia’s 2025 tort reform changes the math
Georgia lets you seek compensation for medical expenses, lost wages, future care, and pain and suffering when someone else’s negligence caused your injury. You generally have two years to file a lawsuit, under O.C.G.A. Section 9-3-33.
Fault matters a lot. Georgia follows a modified comparative negligence rule, so you recover nothing if you’re found 50% or more at fault, according to O.C.G.A. Section 51-12-33.
Here’s what that means in dollars. A $100,000 award shrinks to $70,000 if a jury puts you at 30% fault, and it drops to zero at 50%.
The rules shifted again when Gov. Brian Kemp signed Senate Bill 68 on April 21, 2025. Key changes for injured people include the following, according to the governor’s office:
- Defendants can show jurors the amounts needed to satisfy medical bills under a plaintiff’s health coverage, alongside the billed charges, for claims arising on or after April 21, 2025.
- Closing arguments on pain and suffering must be tied to evidence presented at trial.
- Either side can ask the court to split a trial, so jurors decide fault before hearing damages.
Seat belt use is also back on the table. Under O.C.G.A. Section 40-8-76.1, jurors may consider evidence that an injured driver wasn’t buckled up when weighing fault or damages, subject to the court’s rules on admissible evidence.
The billed-versus-paid change is the one I’d watch. If a hospital bills $80,000 but your insurer pays $30,000, the defense can now point jurors to the lower number, which makes careful records of your care more valuable than ever.
Liens and policy limits can shrink what reaches you
A settlement figure isn’t what lands in your bank account. Hospitals, health insurers, and government programs may claim a right to be repaid from it.
Here’s a simple illustration. On a $100,000 settlement, a one-third attorney fee and a $20,000 medical lien would leave you about $46,700.
Policy limits can cap things even further. If the at-fault driver carries only Georgia’s minimum, $25,000 may be all their insurer pays for your injuries.
That’s why your own policy matters. Uninsured motorist coverage protects you when a driver without insurance injures you or your passengers, according to the Georgia insurance commissioner’s office, and medical payments coverage can help with early bills.
Early offers deserve a hard look, too.
“Families often accept early offers because they need money right away, without realizing that future treatment and lost earning power haven’t been accounted for,” a representative of Van Sant Law said.
Having the Van Sant Law firm review the long-term costs can help families understand what a settlement would need to cover before they sign.
Protecting your credit and cash while a claim drags on
Start with a bare-bones budget that reflects your new income. List every monthly obligation and call lenders before a payment is late, since many creditors run hardship programs.
The Consumer Financial Protection Bureau offers free guidance on handling debt, medical bills, and financial stress.
Your credit report needs watching. A federal judge in Texas vacated the CFPB’s rule banning medical debt from credit reports in July 2025, according to Consumers’ Checkbook.
Equifax, Experian, and TransUnion still say they voluntarily skip medical debts under $500, wait one year before reporting unpaid medical bills, and remove paid ones, the publication reported. Those are company policies, not law, so check your reports.
Keep every record. Save bills, receipts, pay stubs, and letters, track mileage to appointments, and keep a short journal of pain levels and limits on your good and bad days.
Ask for help early. Hospital financial counselors may offer payment plans or charity care, your employer may offer disability benefits, and Atlanta community groups can help with food, housing, and utilities.
An injury can take your health for a season. With the right coverage and records, it doesn’t have to take your financial future with it.
Related: Health insurance is about to cost you a lot more in 2027