There is a version of this conversation that happens in a lot of households, where one spouse sees a hobby and the other starts wondering when it crossed a line. Dave Ramsey has sat in the middle of that disagreement more than once. His word for what he heard this time was habit.
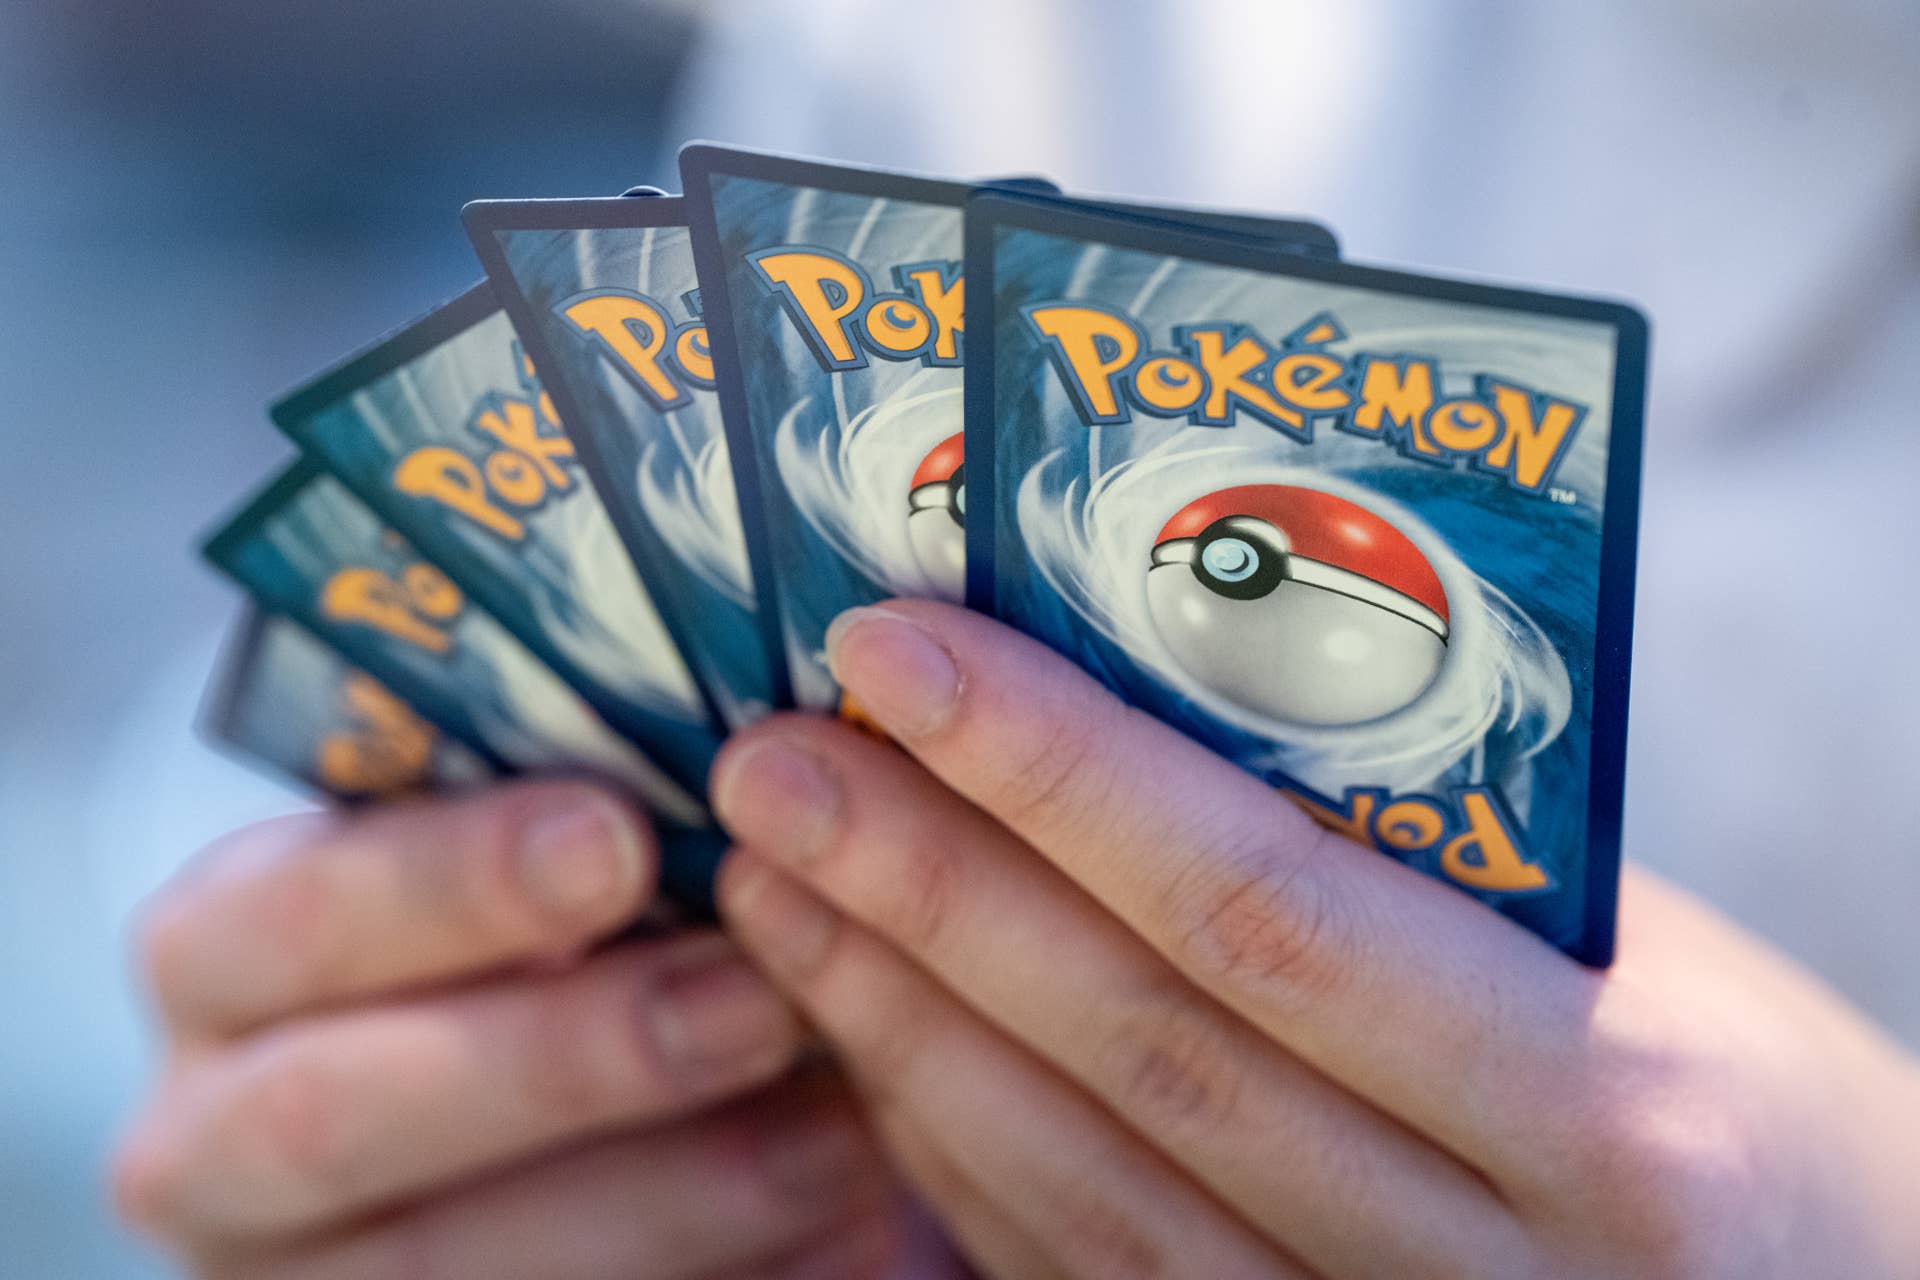
A 27-year-old caller named Lisa told “The Ramsey Show” that her 35-year-old husband has been putting about 80% of his pay into Pokémon cards for roughly two years. The collection sits at around $33,000, and he refers to it as his portfolio.
Ramsey called it something else. “It’s not an investment, and it’s not a portfolio. It’s a habit,” he said.
The setup is unusual enough to seem like an edge case. Lisa explained that her husband’s employer covers their housing, utilities, car, and gas, which means very little of his paycheck goes toward living expenses.
That arrangement has given him more room to spend than most households have. It has also made it easier to avoid a financial question the couple will eventually have to answer.
What happens when the employer benefits go away
The employer-provided benefits are what make 80% of a paycheck available for cards at all. Take them out of the picture, and the household suddenly has real costs it has not been budgeting for.
Rent, utilities, and transportation all carry real dollar amounts. Someone else is covering them right now, but that arrangement may not last.
Also read: Dave Ramsey warns one IRA move could cost you $700,000 in taxes
The $33,000 is an estimate based on what the cards might fetch, not a number the family has actually tested in a sale. What a buyer will pay in any given week depends on market demand, and that demand is not always there when you need it to be.
A savings account does not come with that uncertainty.
That does not mean the cards have no value. It means that value has never really been confirmed under real selling conditions, and most people only discover the gap when they try to sell at the wrong time.
The index numbers are real, but they come with context
Ramsey is not wrong that most collections do not perform like investments, but the card market has actually produced numbers that are hard to dismiss.
CardTrack 100, which tracks the 100 most valuable Pokémon cards by price, has outpaced the S&P 500, gold, Bitcoin and the Nasdaq Composite since September 2021, rising roughly 168% over that period at an annualized return of about 21%.
That is a data point worth taking seriously, and not everyone in the conversation dismissed it.
“Dave Ramsey might be right in this case, but lots of people, including my son, make real money collecting and trading cards. Pokémon and Magic: The Gathering have massive followings, and some cards are truly rare. All collectibles are a risk, but there is money to be made here,” said TheStreet co-Editor-in-Chief and former toy store general manager Daniel Kline.
What the index measures, though, is the 100 most valuable cards in existence, which is a different thing from what most buyers put together through retail purchases. Grading fees, marketplace fees, and dealer spreads also eat into what a seller actually takes home, and those costs do not appear in the index.
It is also worth noting that the same measure fell roughly 27% between September 2021 and January 2024. A strong recent run does not mean the asset behaves predictably over time, or that it can replace a diversified retirement account.
Why the percentage going in matters more than the total value
Look past the collection’s value and the more telling figure is the 80%. That is the share of a paycheck going toward cards while an emergency fund sits unfunded, retirement contributions go unmade, and no one has thought through what expenses look like if the employer-provided benefits disappear.
A collection that appreciates does not fix that. What matters is whether collecting actually fits inside a household’s financial plan, or whether it has quietly become the plan itself.
More Dave Ramsey:
- Dave Ramsey limits family lending to one of two options
- Dave Ramsey warns American workers on 401(k)s, IRAs, Social Security
That gap is also harder to close than it looks. Cards are not an asset you can sell in pieces when cash runs short. The whole collection goes to market at once, at whatever price buyers are willing to pay that week, and there is no guarantee the timing works in your favor.
What to think through before the next purchase
If you collect anything with the idea that it contributes to your financial security, a few things are worth running through before the next purchase.
Start with what you would actually net if you sold the collection today: the real proceeds after platform fees, grading costs, and any other transaction expenses. That is the number available in an actual emergency, not the estimated value on a marketplace listing.
Then think through your income picture without any employer-provided benefits. If housing, transportation, or utilities currently covered by someone else disappeared, what would your real monthly expenses be?
The gap between that number and your current paycheck tells you how much buffer actually exists, and how much of that buffer is going toward cards.
Collecting and building financial security can coexist. Plenty of people manage both without much conflict. But when a hobby is absorbing the majority of take-home pay before the household has a financial cushion in place, the label attached to the collection is the least of the problems.