The hottest IPO in history feels pretty lukewarm right now.
Five months after SpaceX went public, anyone who bought at the offering price is roughly where they started. That’s a long, bumpy ride to nowhere.
The business itself is booming. SpaceX (SPCX) grew third-quarter revenue 161% to $14.6 billion and earned $4.4 billion, its first profitable quarter since the June IPO, according to TeslaNorth.
“We are in an inflection moment for SpaceX across launch connectivity and super intelligence,” CEO Elon Musk said on the company’s earnings call.
However, a subtle shift has emerged between how fast SpaceX is growing and what investors will pay for it.
According to a Morgan Stanley research report seen by TheStreet, SpaceX stock is now cheaper than the S&P 500 on 2028 earnings, even as the bank’s forecasts for the company have nearly doubled.
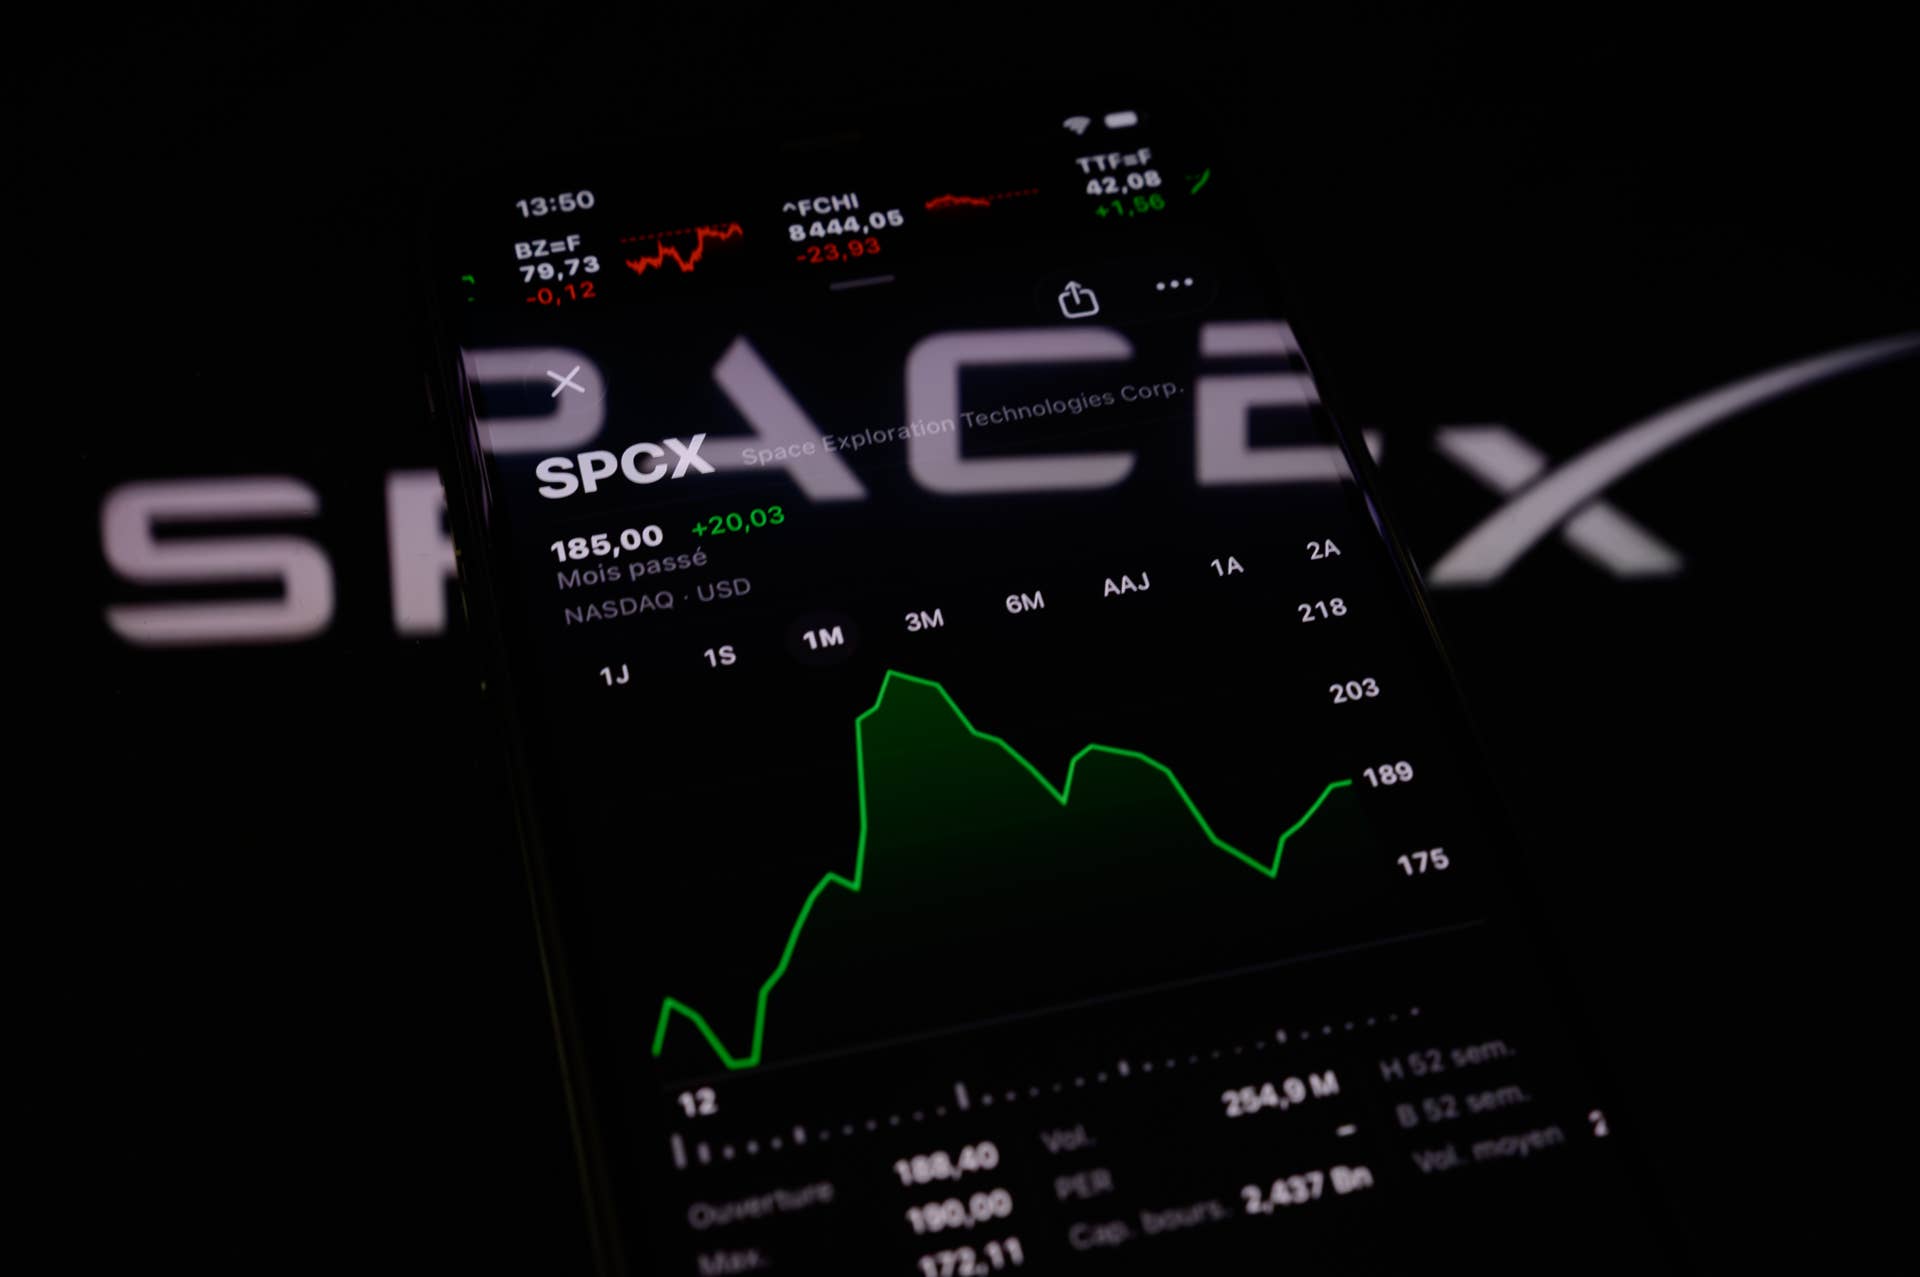
Morgan Stanley nearly doubled its SpaceX forecasts
Morgan Stanley analyst Adam Jonas laid out the shift in a Nov. 3 note titled “SPCX Getting Even Cheaper: Cash Flow Positive 4 Years Earlier.”
In less than four months since he started covering the stock, Jonas has raised his 2027 revenue forecast by 93% to $175 billion. He lifted his 2028 forecast by 84% to $289 billion.
He now expects SpaceX to generate positive free cash flow by 2031, four years earlier than the 2035 he expected in July. He also cut his projected borrowing to $390 billion through 2031, from $670 billion through 2035.
Related: Tesla-SpaceX merger math just shifted in Tesla’s favor
“On FY28, SPCX trades cheaper than the S&P500. Interesting,” wrote Jonas.
At his 2028 adjusted earnings forecast of $109 billion and a market value of about $1.91 trillion, SpaceX would trade at 17.6 times earnings. That compares with 17.7 times for the S&P 500, the note showed.
Jonas kept his Overweight rating and $300 price target. The stock closed at $136.37 on Nov. 2, according to the note. By my math, his target implies about 120% upside.
Why the stock fell while the business boomed
The stock tells a different story than the income statement.
SpaceX priced its IPO at $135 on June 11 and peaked at $225.64 on June 16, according to FinanceFeeds. It closed at $134.72 on Oct. 30, just below the offering price.
By my math, the Nov. 2 close sits about 40% below that peak and barely 1% above the IPO price.
Three things have weighed on the shares. Lockup expirations keep adding sellable stock, valuations were stretched at the peak and capital spending is enormous, according to The Motley Fool.
More on SpaceX stock:
- SpaceX has a plan to make your phone carrier obsolete
- Bank of America sends SpaceX stock investors strong signal
- SpaceX’s multi-trillion-dollar case rests on a bet not yet launched
The spending is the part I’d watch most. SpaceX spent $19.6 billion on capital projects in the third quarter, more than its $14.6 billion in revenue.
SpaceX expects to spend another $35 billion to $40 billion in the fourth quarter, its chief financial officer said on the call. By my math, that’s roughly 2.4 to 2.7 times last quarter’s revenue.
More supply is coming, too. Up to 797.6 million more shares are set to unlock in early December, FinanceFeeds reported.
Given that backdrop, it’s easy to understand why the stock has lagged. Jonas thinks the market is pricing SpaceX’s AI business at close to nothing.
What Morgan Stanley expects next
Jonas sees a near-term test.
Starship Flight 15, expected this month, will attempt to catch both the booster and the ship. Musk said success is “more likely than not,” the note said.
“Flight 15 is shaping up as SpaceX’s biggest test of Starship reusability, derisking TAMs [total addressable markets] across the broader business,” wrote Jonas.
He also argues the stock price covers only the rockets and Starlink. At about $140 a share, investors are paying roughly $123 for space and connectivity and just $17 for AI, Jonas wrote.
His $300 target leans heavily on that AI business. Enterprise AI accounts for $170 of the target, with connectivity at $111, X and Grok at $11 and space at $8, the note showed.
By my math, enterprise AI makes up about 57% of the target. Morgan Stanley already applies a 50% discount to that business for execution risk.
Much will likely depend, however, on whether SpaceX can turn its AI spending into revenue fast enough. SpaceX guided first-quarter 2027 revenue to $33 billion to $37 billion.
At the $35 billion midpoint, that’s about a $140 billion annual pace, by my math. Jonas’s $175 billion forecast for 2027 needs SpaceX to grow well beyond it as the year goes on.
I’d treat the 2028 math with care. A price-to-earnings multiple two years out depends on forecasts that have already jumped by as much as 93% in four months, and they can move back.
Still, Jonas sees the pullback as a chance to revisit the stock before the catch attempt. Investors have “a unique opportunity to ‘revisit’ SPCX ahead of the attempt, with fundamentals accelerating across all major business lines,” he wrote.
Related: 80% of S&P 500 stocks are in correction territory. These 3 are still buys