On Tuesday, November 10, 2026, I wrote that Take-Two Interactive Software (TTWO) isn’t ready to declare victory on GTA 6. That caution was only half the story.
I’ve played every Grand Theft Auto game, starting with the ones I snuck as a kid. Each ends with the credits rolling and a choice: keep driving around the city or stop.
That choice now matters to Take-Two’s investors. On the Monday, November 9, 2026, earnings call, Bank of America analyst Omar Dessouky asked CEO Strauss Zelnick how Take-Two keeps those players.
Zelnick called it “an array of high-class problems.” He said he had “literally never” had to answer it, “because you can always keep going.”
Also read: Take-Two isn’t ready to ‘declare victory’ on GTA 6 before launch
That is a strong message, and Take-Two backed it with its forecast. It kept its fiscal 2027 net bookings outlook of $8 billion to $8.2 billion, according to its earnings release. It did so after a quarter slightly below its own guidance, Zelnick said.
Everyday spending slipped before the launch
The shortfall hit Take-Two’s most dependable money. Recurrent consumer spending, the money Take-Two earns inside its games, fell 9%, according to the release. CFO Lainie Goldstein said guidance had called for a 5% drop, and NBA 2K drove the gap.
President Karl Slatoff said “it is really hard to know exactly what has caused a little bit of softness” in NBA 2K27’s launch. That uncertainty matters, because NBA 2K shows fans will pay into one franchise year after year.
GTA needs that same habit. Bank of America’s note shows what rides on it.
Bank of America draws a line for launch weekend
Dessouky and fellow analyst Arthur Chu reiterated a Buy rating and a $330 price target in a research note shared with TheStreet. Opening weekend is their test.
“We think a number below $1.5bn would imply that units would fall short of FY27 investor expectations,” they wrote. They put investors’ median expectation near 50 million units.
Pricing is the bright spot. The analysts say guidance implies more than half of preorders went to the $99.99 Ultimate Edition, “a sign of the pricing power of the franchise.”
Even so, Bank of America conservatively models a 30% premium mix. Sensor Tower estimated that share at nearly 90% at the end of August, Reuters reported. Still, the weekend is the short game.
Bank of America sees the real payday in GTA Online
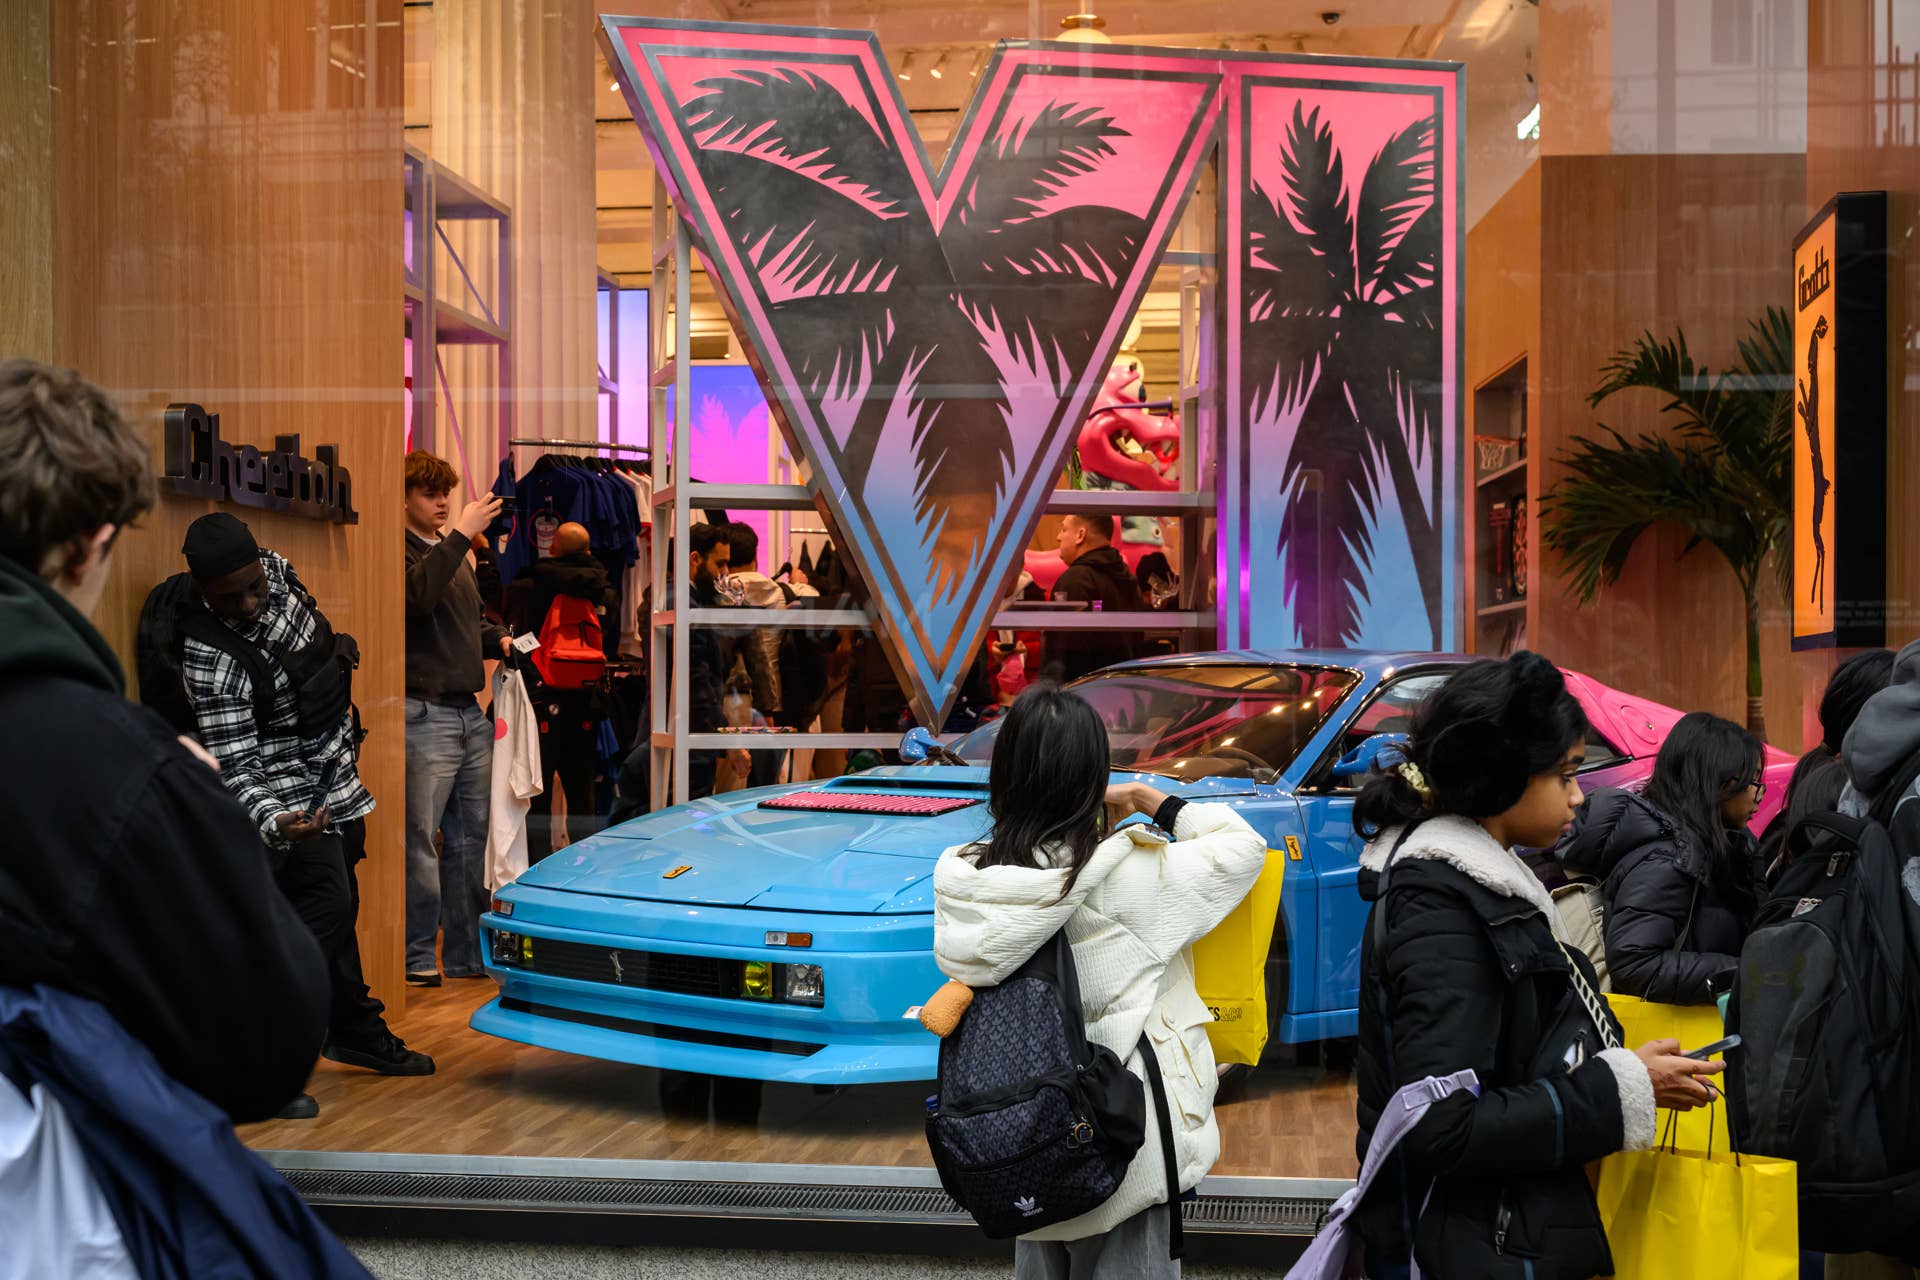
The bank’s long-term case rests on GTA Online. That’s the endless version fans keep playing until the next GTA arrives. They spend real money there on guns, cars, outfits and even houses.
BofA expects that spending will approach levels seen in “the industry’s other pay-to-progress games,” where players pay to move ahead faster.
More Take-Two:
- Take-Two isn’t ready to ‘declare victory’ on GTA 6 before launch
- GTA 6 sick days could cost employers as Take-Two cashes in
- GTA 6 sneakers will reportedly cost more than the game
The catch is timing. Bank of America now assumes the next GTA Online arrives in fiscal 2028, which begins in April 2027. That shift mostly explains its cut to fiscal 2027 in-game spending to $5.36 billion from $5.54 billion.
It also cut its fiscal 2027 earnings estimate to $7.43 per share from $8.75. The target held because it rests on fiscal 2028.
Zelnick’s answer to Dessouky was confident but undated. When asked by TD Cowen’s Doug Creutz about the year after launch, he said, “I’m not going to give you guidance for fiscal 2028 today.” Investors didn’t seem to mind.
The valuation is the number to track
Take-Two shares jumped 8.3% the day after the call. They remain below the 52-week high of $265.94 cited in the note.
Bank of America argued that the stock was cheaper than the S&P 500, trading at 16 times its fiscal 2028 estimate. That estimate is $13.02 per share and leans heavily on rising GTA Online spending. The Street’s average is lower. On the $10.23 average StockAnalysis tracks, the stock now trades near 22 times.
The 29 analysts tracked by StockAnalysis rate Take-Two a Strong Buy, with an average target of $283.86. Bank of America’s $330 is the highest on that list.
That valuation gap is worth tracking until Take-Two reports its holiday quarter early next year. The company expects earnings of $1.30 to $1.44 per share, according to the release. If estimates climb faster than the stock, GTA 6 added real earnings power.
Even Bank of America’s own model shows earnings per share slipping about 4% in fiscal 2029 as the launch fades. Take-Two now lives on what fans keep spending, and GTA 6 will test that publicly.
The first verdict comes on launch weekend. The one that matters comes when the credits roll and players decide whether to keep going.