Chief executives get two microphones. One is bolted to an earnings call, where every number carries legal weight and a team of lawyers reads it first.
The other is a hallway, a stage, or a scrum of reporters, where the same person can say almost anything.
Nvidia (NVDA) has used both for three years, and the pattern has held. The company guides carefully in writing. Then its founder talks about the future in round numbers that make the written guidance look timid.
That split has mostly worked in shareholders’ favor. Nvidia has spent three years beating its own revenue guidance, so the expansive version kept turning out to be the accurate one. Investors learned to treat the hallway version as a preview rather than a promise.
On Thursday, Sept. 17, the two versions stopped agreeing.
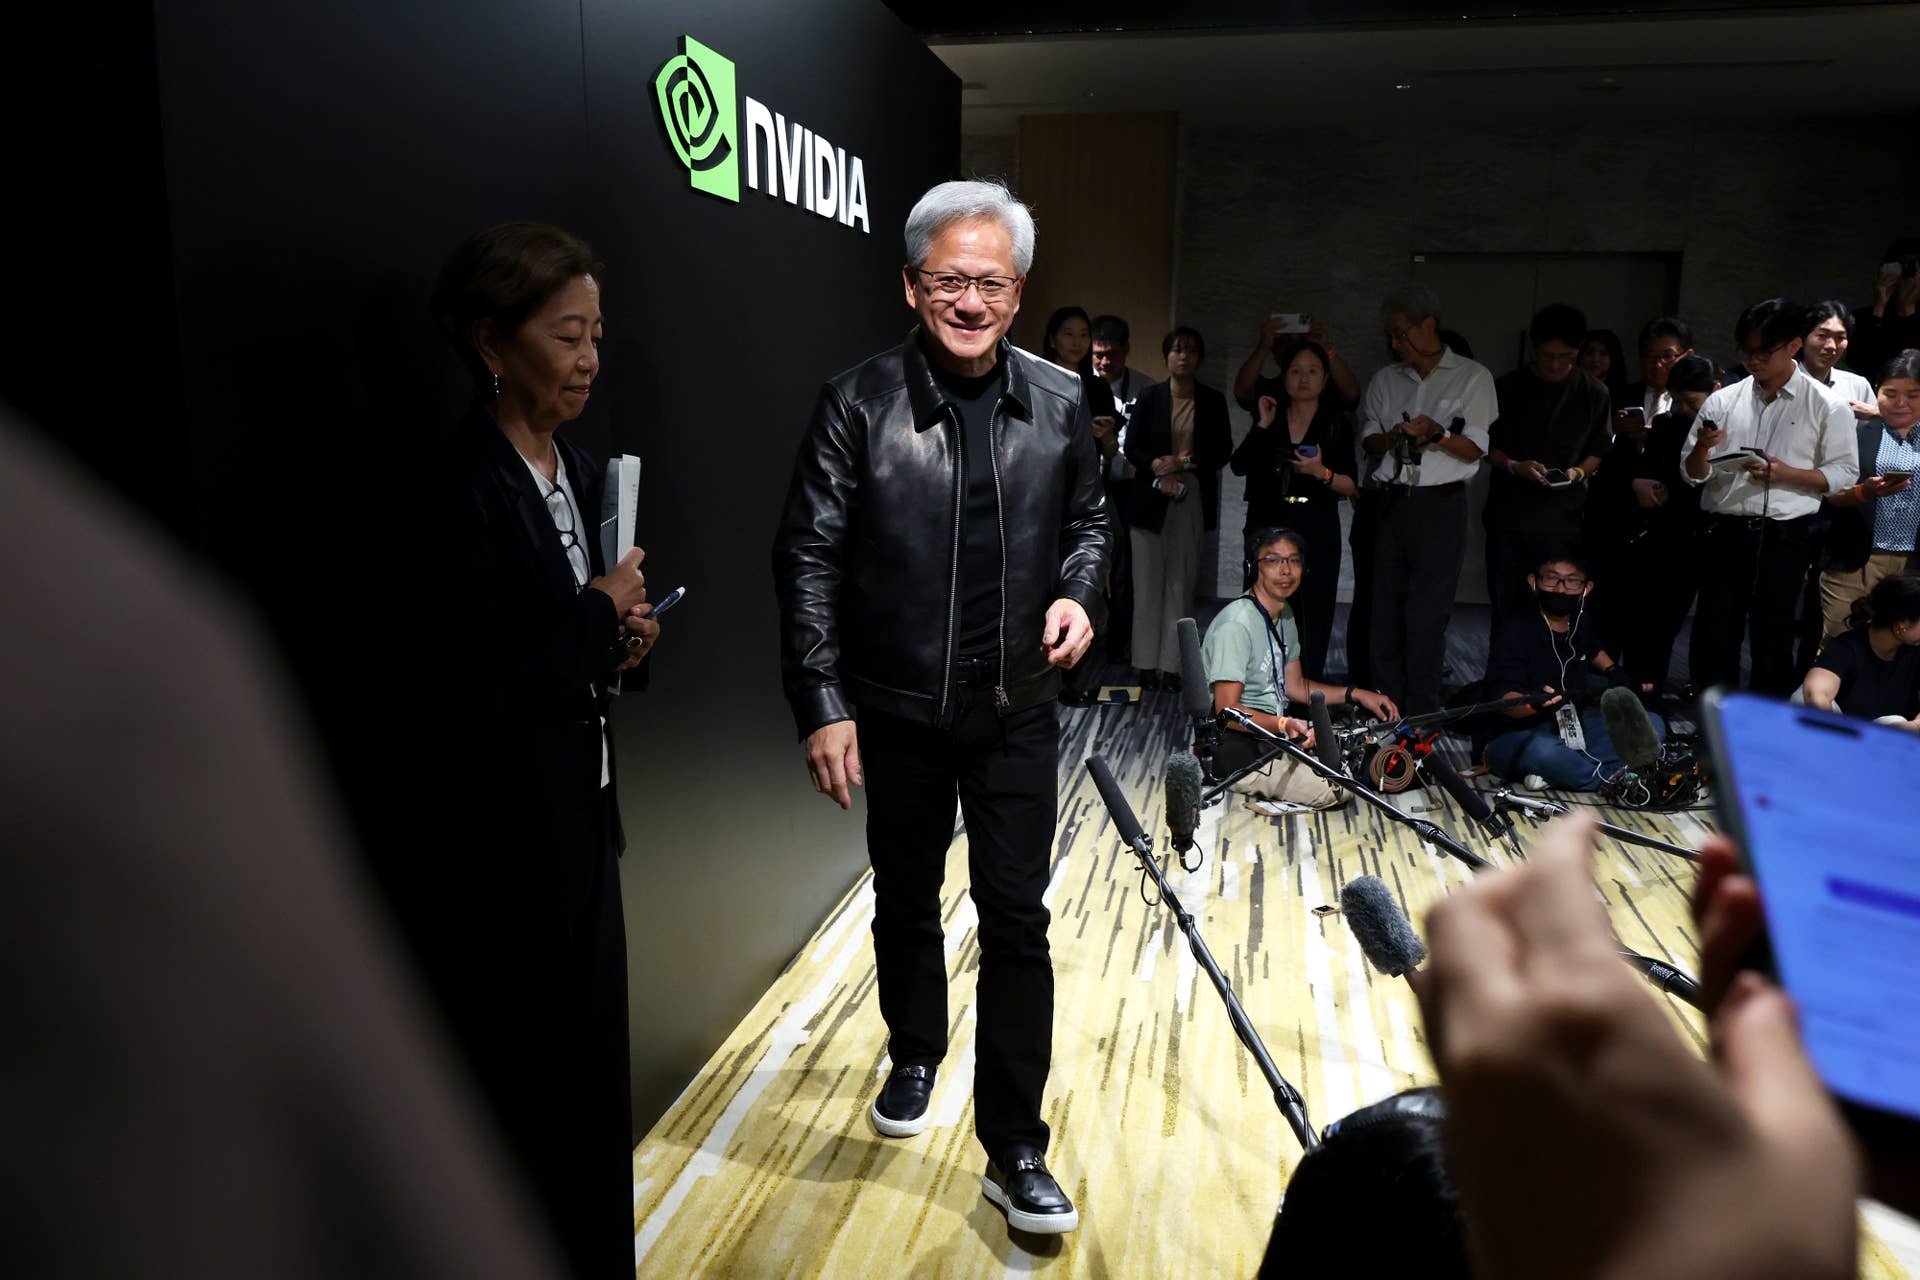
Speaking to reporters at an artificial intelligence (AI) gathering convened by King Charles III in Scotland, Jensen Huang said Nvidia expects to sell twice as many chips over the coming year, according to Bloomberg.
Nvidia’s own paperwork calls for something smaller.
How Nvidia turns chip supply into revenue growth
Nvidia sells far more than the data center graphics processing units (GPUs) that dominate the headlines. It also sells central processors, networking switches, optical chips, laptop silicon, and the processor inside Nintendo’s Switch 2.
That mix matters, because a chip is not a fixed unit of revenue. A Blackwell rack system and a laptop GPU each count as one chip sold. They do not count as the same dollars.
More Nvidia:
- Nvidia cloud partner crosses major compute threshold
- Jim Cramer drops 5-word verdict on Nvidia stock
- Nvidia CEO Jensen Huang doubles down on his big 2030 market bet
The distinction rarely came up while the data center business was swallowing everything else. Revenue for the quarter ended July 26 was $96.2 billion, up 106% from a year earlier, with data center sales of $89.0 billion, according to Nvidia’s earnings statement.
Gross margin that quarter was 75.0%, the same statement confirmed, and Huang’s summary of the business was three words: “Compute is revenue.”
That is the machine. Chips go out, margin comes back, and the market pays roughly 30 times earnings for the privilege of watching it run.
What Huang’s doubled chip forecast leaves out
Nvidia has guided to about 70% revenue growth for the fiscal year ending in January 2028, which works out to roughly $673 billion, according to CNBC. Huang’s comment in Scotland points to unit volumes doubling, which is 100%.
Those are two different measures, and I ran them against each other before writing a word of this piece. If units double while revenue grows 70%, average revenue per chip falls by roughly 15%.
That is arithmetic, not opinion, and three explanations fit it.
- Nvidia may be sandbagging its written guidance again, which is the friendliest reading.
- The product mix may be tilting toward cheaper parts as AI spreads into laptops, cars, and robots.
- Huang may have been describing a supply scenario his company has not committed to on paper.
He gave the demand reason himself, telling reporters that in almost every country where Nvidia operates, “people want to invest in AI,” CNBC reported.
Two Nvidia forecasts, side by side
- Chip units sold will roughly double over the coming year, Huang told reporters in Scotland, according to Bloomberg.
- Revenue is guided to grow about 70% in the fiscal year ending January 2028, or roughly $673 billion, CNBC noted.
- Second-quarter revenue was $96.2 billion at a 75.0% gross margin, according to Nvidia’s earnings statement.
- Third-quarter revenue is guided to $108 billion, plus or minus 2%, the same statement indicated.
The margin math behind doubling Nvidia shipments
Nvidia has already told investors where the pressure lands. Gross margin will decline and bottom out in the fourth quarter of fiscal 2027 at 71% to 72%, partly because of memory prices, according to CNBC’s earnings coverage.
Finance chief Colette Kress framed the memory shortage as a problem the AI buildout is creating for itself, CNBC noted.
What struck me in my analysis of that guidance is the sequencing. The margin trough arrives before the unit doubling does.
Related: Jensen Huang just sent Wall Street a message about AGI
Shipping twice as many chips at 71% is a different business from shipping half as many at 75%. It is still an extraordinary business. It is a less profitable one per unit, and that is the part a doubling headline hides.
Huang has doubled down before. He repeated a $3 trillion to $4 trillion global AI infrastructure forecast for 2030 at a Wall Street technology conference on Sept. 10.
For a stock carrying a market value above $5 trillion, revenue per chip is the line that decides whether next year repeats this one.
Why AI oversight is the wild card for Nvidia investors
The Scotland event was not a sales conference. King Charles III used it to press the industry, telling executives from Nvidia, OpenAI, Google DeepMind, and Anthropic that “we need sufficient means of control before it is all too late,” according to Fortune.
Huang’s answer was that safety belongs to individual companies rather than a coordinated pause. When a product is not safe enough, “we should hold it back and keep engineering,” he said, Scripps News reported.
That position is consistent, and it is also commercially convenient. Nvidia’s customers are the labs being asked to slow down, and every month of delay in a training run is a month of deferred orders.
No regulator was blocked in Scotland, because no regulator with authority over frontier models exists yet. What happened is that the most powerful supplier in the chain argued against creating one, in front of a head of state who had just asked for it.
If that argument loses anywhere, whether in Brussels, Washington, or London, the unit ramp acquires a governor it does not currently have.
What the Nvidia chip forecast means for your money
Nvidia carries the heaviest weight in the S&P 500. If you hold an index fund, a target-date fund, or whatever your 401(k) put you in by default, you own this forecast whether or not you follow chip pricing.
The temptation is to read “twice as many chips” as twice as good. Twice as many chips is a different claim from twice the revenue, and Nvidia’s own filings say so.
The number worth marking on your calendar is the gross margin line in November’s third-quarter report. If it holds near 74%, Huang’s version wins, and the written guidance was conservative.
If it slides toward the 71% floor while the unit talk keeps climbing, the market will be paying for volume it cannot bank.
Huang has been right more often than he has been wrong, and betting against him has been an expensive hobby.
The thing to watch this time is not whether he is right about the chips. It is whether each one is still worth what it was.
Related: Jensen Huang just answered Michael Burry’s Nvidia bear case