The stock market often feels like déjà vu.
You see a growth stock like Nvidia (NVDA) race higher for weeks, tell yourself you’ll buy when it gets cheaper, and then freeze when it does. Suddenly, buying that dip feels more like catching a falling knife.
That’s exactly the dilemma facing investors following Nvidia’s October sell-off.
Shares closed at $221.97 on Oct. 21, down 7.2% from their Oct. 6 closing high of $239.24, according to Yahoo Finance data. The pullback lands in the 5% to 8% range, and that’s the kind of retreat Jim Cramer says he likes to watch for strong stocks.
However, there’s a catch.
Nvidia stock had fallen more than 10% from that high just days earlier, and concerns about AI capital expenditures are seemingly reaching a fever pitch.
Cramer has long told viewers to “own it, don’t trade it” when it comes to Nvidia. His buying rule, however, comes with a warning, which is that a cheaper stock isn’t automatically a healthier investment.
So, which kind of drop is this for shareholders?
Nvidia’s October sell-off puts Cramer’s 5% to 8% rule to the test
In the Oct. 21 “Mad Money” episode, Cramer told his viewers about how he decides when a stock that’s been winning might finally be worth a closer look.
His starting point is the market’s new high list, such as Yahoo Finance’s list of the top gainers over the past 52 weeks.
Companies reaching fresh peaks often have something working in their favor, whether it’s strong earnings or momentum across their industry. But chasing those peaks can leave investors paying too much.
More Nvidia:
- Nvidia stock flashes massive signal as Wall Street leans in
- Nvidia’s AI boom revives a Warren Buffett warning for investors
- Nvidia puts $500 billion on the table, challenges banking as we know it
“New high list is not a shopping list. It’s an inspiration list. You keep an eye on those names, then wait for them to come down so that you can pull the trigger,” Cramer said.
His preferred pullback is 5% to 8%. And Nvidia’s October hammering offers an unusually precise example.
The chipmaker closed at $239.24 on Oct. 6 and $221.97 on Oct. 21. That’s a 7.2% drop. Using the earlier closing high, Cramer’s range translates to roughly $227.28 at the upper end and $220.10 at the lower end.
In addition, investors who watched the entire slide know it wasn’t that tidy. Nvidia closed at $214.13 on Oct. 16, down about 10.5%, before climbing back into the range.
“I’ve found less than 5%, and you’re probably too early, more than 8%, and it’s more likely that something’s going wrong, very wrong, maybe even with the underlying company,” Cramer then went on to say.
That means every 9% or 10% decline doesn’t always signal trouble. It means price alone can’t tell investors whether they’re seeing ordinary profit-taking or a business problem.
Nvidia has passed Cramer’s numerical screen.
The tougher question is whether the reasons investors sold it have changed the company’s forecast as AI investment continues to accelerate.
The real risk for Nvidia sits with companies financing the AI boom
Jim Cramer had a familiar message for Nvidia shareholders near the tail end of that episode: “Own it, don’t trade it.”
He repeated the long-term stance, despite the chipmaker’s troubles, and his reasoning begins with the business.
For context, Nvidia reported $96.2 billion in fiscal Q2 sales, up 106% year over year. Data center sales reached $89 billion, up 117% underscoring tremendous demand.
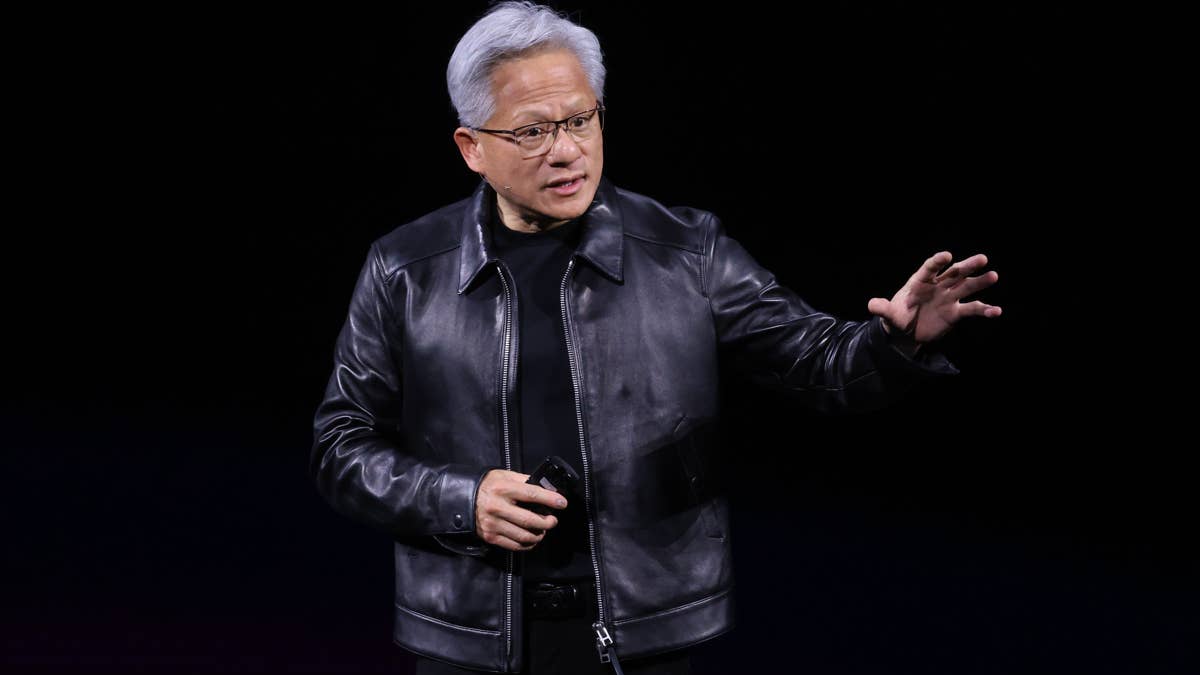
And CEO Jensen Huang is preparing for more. On Oct. 21, Nvidia announced supply agreements designed to increase critical chip-substrate capacity 2.5 times over three years. It also committed $1.1 billion to help its supplier, KYEC, expand semiconductor testing in the United States.
However, the issue is that Nvidia’s buyers need money to keep building data centers.
Take Nvidia-backed CoreWeave (CRWV), for example.
According to Seeking Alpha, the Nvidia-backed giant carried $51.61 billion in total debt, including lease obligations, and $46.03 billion in net debt as of Q3 2026. Its current ratio was also just 0.46, indicating it had only 46 cents in current assets for every $1 of short-term liabilities. That’s low, well behind the commonly used benchmark of 1.0.
Meanwhile, Nvidia expects its next-quarter gross margin to slip to around 74%, down from 75%, even as it spends billions to secure manufacturing capacity.
Though it doesn’t prove Nvidia’s growth is breaking down, it raises the question about whether AI customers can keep financing the orders Nvidia expects to fill.
Nvidia’s $108 billion forecast puts Cramer’s buying rule to the test
Nvidia’s upcoming earnings report will help investors decide if the recent sell-off was an opportunity or an early warning.
The company expects fiscal Q3 sales of $108 billion, plus or minus 2%, implying $105.8 billion to $110.2 billion. But another big sales number won’t settle every concern.
Investors need to watch whether major cloud customers can maintain their spending plans, how Nvidia’s Vera Rubin rollout progresses, and whether rising component costs squeeze margins. Strong chip demand matters less if customers struggle to finance the data centers housing those chips.
That’s where Cramer’s disciplined approach comes into play. His 5% to 8% pullback rule serves as a starting point for further research, and in the episode, he illustrated how investors could build a 100-share position in Nvidia through four purchases of 25 shares each, rather than committing all their money at once.
The stakes extend beyond stock pickers.
Nvidia represents a substantial share of the S&P 500, giving retirement savers exposure through index funds.
So Nvidia’s lower price may appeal to investors, but customers’ ability to keep spending will determine whether the business can justify that optimism over the years.
Related: Bank of America sees a $300 billion test for Google stock