In October, I covered Bank of America’s thesis on raising Seagate’s price target to $1,200 while the stock was trading around $642. I added my own technical read, pointing to three consecutive bearish weekly candles and warning that buying then would be like trying to catch a falling knife.
My verdict was to wait for a bullish confirmation near $570 support, ideally alongside a strong Oct. 27 Q1 fiscal 2027 earnings report. Yes, we got the earnings catalyst, but the technical setup never confirmed.
The $570 support level eventually broke down, and Seagate suffered another sharp sell-off. But it looks like we just found another key support level around $445 that the price is reacting to.
The business has kept growing. Seagate (STX) reported fiscal first-quarter revenue of $4.233 billion, up 61%, with non-GAAP EPS of $7.68 and a record $1.479 billion in free cash flow.
CEO Dave Mosley himself pointed to long-term customer visibility and a “multi-year growth phase.” However, the stock has fallen about 43% in 3 months, and 56% from its $1,145 all-time high reached in June 2026. Currently, Seagate trades at $501, according to Yahoo Finance.
Also Read: Seagate CEO drops eye-opening message on exploding AI data demand
Seagate’s sales surge as the stock slides
In a note shared with me at TheStreet, Morgan Stanley maintained Seagate at an Overweight and Top Pick with a $1,148 target in a note titled “Management Meetings Highlight the Disconnect Between Strong Fundamentals and Weak Sentiment.” Moving from $501 to $1,148.00 represents a 129% gain.
Morgan Stanley says revenue and pricing are accelerating, and the supply-demand gap is widening. Yet the shares trade at about 5.2x its calendar 2028 EPS estimate of $89.21, below historical trough multiples for hard drive makers and about 3 times its bull case.
More Seagate:
- Seagate’s booming business comes with an unexpected twist
- Morgan Stanley cuts Seagate stock price target but sees 72% upside
- BofA sees 80% upside for Seagate stock, but Micron shares look cheaper
Yahoo Finance data shows the stock is still up 82.74% this year, 71.63% over one year and 635.27% over three years through Nov. 10.
Seagate also guided the December quarter to revenue of $4.8 billion, plus or minus $100 million, and non-GAAP EPS of $9.20, plus or minus 20 cents. It retired $1.2 billion in debt during the quarter, with another $750 million since, and raised its dividend by 3% to $0.76. So, fundamentally, the business is doing okay.
What spooked Seagate investors
Looking more closely, I found several factors behind the sell-off.
On Oct. 2, Nikkei Asia reported that Toshiba plans to double its capacity for hard drives used in AI data centers within its fiscal 2027, and Seagate fell 10.2% that day. Seagate and Western Digital (WDC) each fell 10.2%, reflecting concerns about heightened overseas competition.
More followed. TIKR reported chip and memory stocks dropped on Oct. 22 after Lam Research’s outlook and Tesla’s capital spending cut, and on Oct. 30 Seagate fell 8% as the Nasdaq had its worst day since June.
By Nov. 2, the stock had closed at $593.76, down 30% from its Oct. 2 close. TIKR also reported that investors sold data center and storage stocks after the midterm elections, with rising memory prices a second worry.
I know how quickly market sentiment can change when several negative headlines hit the same stock. Even when the long-term demand story remains intact, investors can rush for the exit before the fundamentals have time to catch up.
TIKR’s analogy is that Seagate has little exposure to flash memory prices, and most of its drive supply is committed under long-term agreements and contracts through 2028. Morgan Stanley agrees that memory is mostly a cost for drive makers.
Morgan Stanley has five answers to that Seagate debate
- No sign of industry irrationality. Capital spending stays flat at 4% to 6% of revenue, and supply grows through areal density — how much data fits on each disk, not more units. Management says Hyperscaler demand for exabytes exceeds its 25% long-term framework, and volume and pricing for 2027 are already negotiated.
- Component inflation slows cost declines, but stronger pricing offsets it.
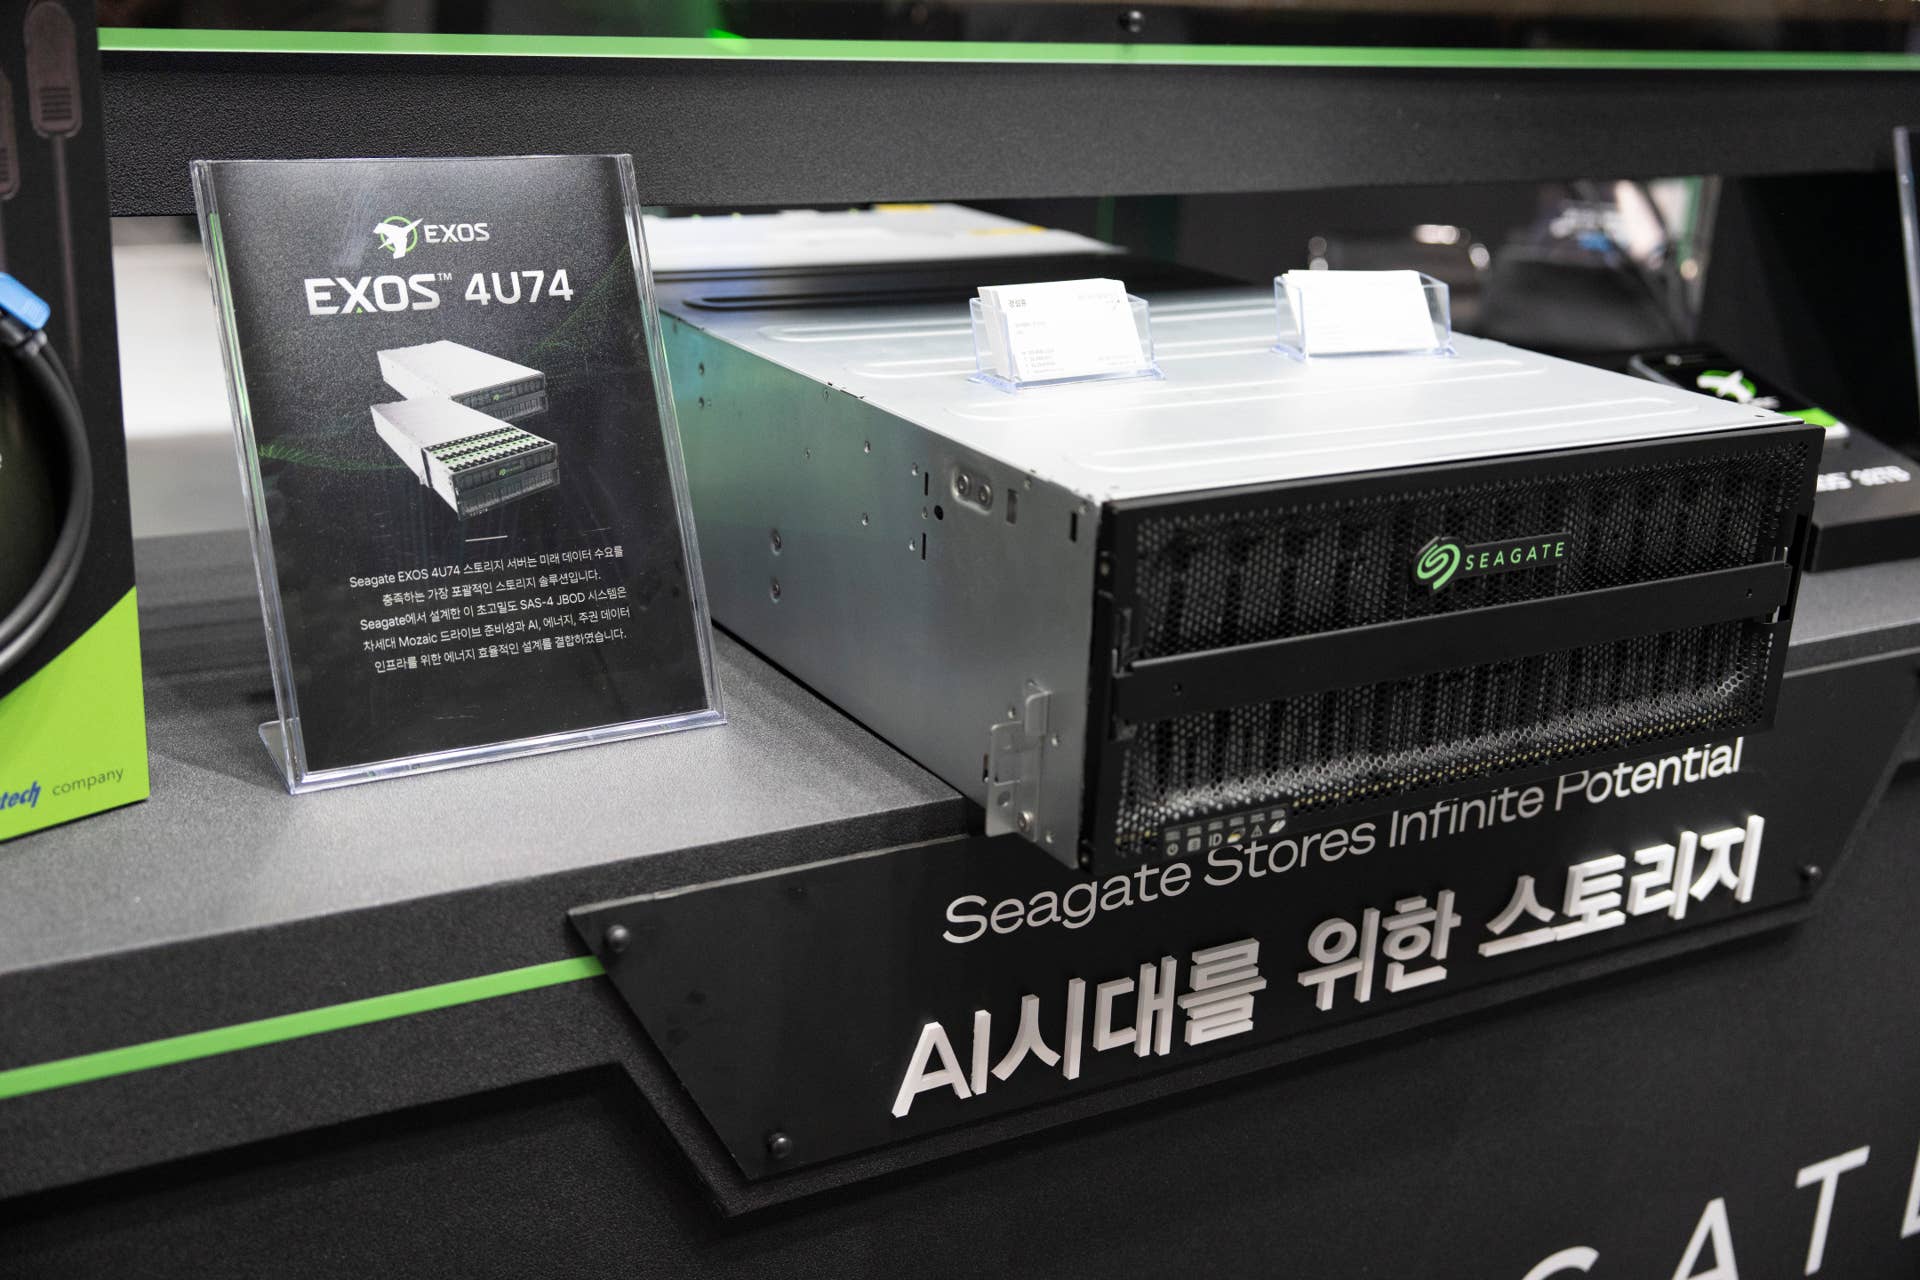
- HAMR, Seagate’s heat-assisted recording technology, is on track, with Mozaic 4 shipping to major cloud customers without qualification issues.
- Drives are less cyclical than memory. Exabytes drive their growth, which outpaces pricing growth by about 4x, and capital spending and depreciation are under 10%, versus 20% to 40% for memory makers.
- Density and a shift toward data centers are structurally lifting margins.
Buybacks and scenarios
With debt cut from $5.0 billion to $2.8 billion in the last 12 months, according to the note, Seagate’s focus shifts to shareholders. Morgan Stanley says buybacks could reach about 30% of market cap in 2.5 years.
The base case of $1,148 applies 15x fiscal 2028 EPS of $76.64, with gross margins in the 60% range. The bull case is $1,580 if cloud demand surprises and HAMR drives margins toward 70%.
The bear case is $522 if growth slows, AI demand falters, solid-state drives displace cold data storage, and the industry expands capacity again.