There’s a particular kind of frustration that comes from owning a company with a $715 billion backlog and a stock that keeps falling anyway.
Boeing’s (BA) order book is the largest in its history. The world still needs airplanes. And yet BA is down 13.43% year to date, according to Yahoo Finance.
In September alone, it has a fresh 9.7% slide driven by a software bug, certification delays on the 737 MAX 10, and another labor contract expiring, according to a Morgan Stanley note shared with me at TheStreet.
Morgan Stanley sees a potential entry point in all of that noise. But it has a very specific trigger.
The firm maintained its Equal-weight rating and $250 price target on Boeing in the note on Sept. 30, describing the setup ahead of the Oct. 1 SPEEA labor vote as “a potential tactical buying opportunity” if the contract is ratified.
BA trades around $187. The $250 target implies roughly 33% upside, according to the note.
ALSO READ: History of Boeing: Company timeline and facts
The Oct. 1 Boeing contract vote: why it matters more than headlines suggest
The Society of Professional Engineering Employees in Aerospace (SPEEA) represents Boeing’s professional and technical engineers, a workforce whose skills are foundational to aircraft certification, software development, and production ramp.
Voting on Boeing’s revised contract offer closes Oct. 1 at noon PST, with results expected that afternoon.
If members ratify the contract, a major labor overhang would be lifted from a stock already facing multiple headwinds.
If they reject it, Oct. 7 becomes the earliest possible strike date, according to the note, though rejection does not automatically trigger one.
More Boeing:
- Boeing CEO warns of 737 Max production delays
- Boeing races to defuse a threat that could ground its comeback
- Boeing’s safety reckoning cost it just $3.1 million
Morgan Stanley’s note introduces an important historical distinction. SPEEA has conducted exactly one full strike against Boeing in its history: a 40-day work stoppage in 2000, plus a one-day walkout in 1993.
That contrasts sharply with the IAM machinists, who struck Boeing seven times between 1948 and 2008, including a nearly two-month work stoppage in 2024. Most current SPEEA members have never been through a strike against Boeing.
The SPEEA Professional and Technical Bargaining Unit Councils are recommending acceptance of the revised offer. That is not a guarantee, but it is meaningful context.
“We would not necessarily extrapolate the experience of the 2024 IAM negotiations directly to SPEEA,” as Morgan Stanley notes.
For investors who lived through the 2024 IAM strike and watched it cost Boeing production and shareholder confidence for months, the distinction between that workforce and this one is the difference between a bad week and a bad quarter.
The Boeing MAX 10 issue and what it means for the 2027 timeline
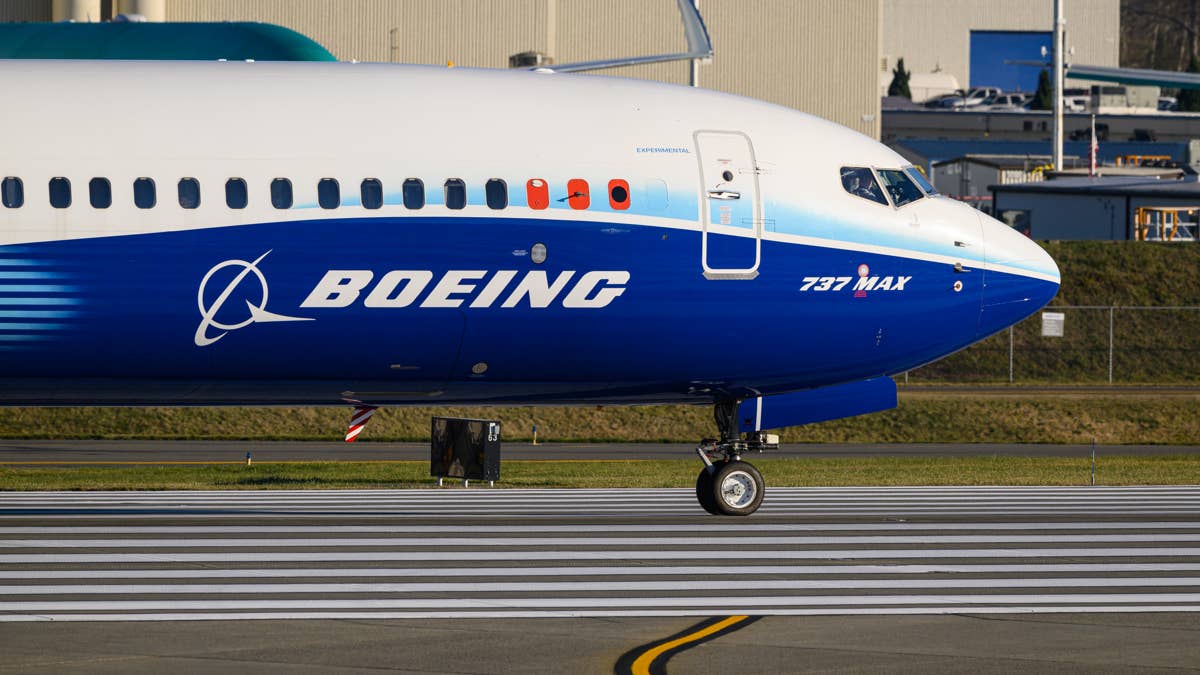
Boeing’s stock has also been reacting to FAA commentary suggesting a potential delay on 737 MAX 10 certification, following the disclosure of a software issue that has affected MAX 7 deliveries.
Morgan Stanley’s honest assessment is that consensus free cash flow estimates will likely be revised lower as more details emerge. The 737 MAX 10 represents approximately 24% to 25% of Boeing’s expected 2027 backlog, according to Cirium data cited in the note, making the headline exposure look significant.
The partial mitigation: Operators may be able to convert MAX 10 orders to MAX 8 or MAX 9 variants and still take delivery, preserving some 2027 revenue even if the MAX 10 certification slips.
The timing of MAX 10 certification is largely in the FAA’s hands, not Boeing’s. That distinction matters when assessing responsibility for delays and the path to recovery.
Morgan Stanley’s $10 billion free cash flow anchor remains intact, supporting its $250 price target based on a 20x multiple of normalized 2028 FCF per share of $12.29.
At current levels around $187, BA trades at approximately 15 to 16 times FCF yield — a 6.4% FCF yield if the $10 billion figure holds.
Boeing’s business underneath the headlines
Boeing’s Q2 2026 results, reported July 28, 2026, showed revenue of $24.6 billion driven by 171 commercial deliveries, according to Boeing’s earnings release.
The GAAP loss per share was -$ 0.67, with operating cash flow of $1.4 billion and free cash flow of $0.6 billion. The total company backlog grew to a record $715 billion, including more than 6,200 commercial airplanes.
That backlog tells you that airlines around the world are still betting on Boeing’s future, despite everything. That’s an important part to note.
The question has never been about demand but about Boeing’s ability to execute against that demand without another self-inflicted disruption — regulatory, mechanical, or labor-related.
The Oct. 1 vote could give Boeing its clearest near-term signal on whether 2026 brings another disruption or a return to greater stability. Morgan Stanley thinks ratification creates a buying opportunity. The answer arrives on the afternoon of Oct. 1 .
Related: Boeing races to defuse a threat that could ground its comeback