Wall Street has spent years obsessing over when the Federal Reserve will lower interest rates, but billionaire investor Stanley Druckenmiller thinks investors may be asking the wrong question.
The senior macro investor argues that U.S. interest rates are already too low and that future rate cuts aren’t essential, according to the Financial Times.
His argument comes at a critical period.
Treasury bonds have been under selling pressure amid inflation fears, growing U.S. public debt, and considerable bond issuance by artificial intelligence startups, CNBC noted. And it puts the focus of market chatter back on borrowing rates.
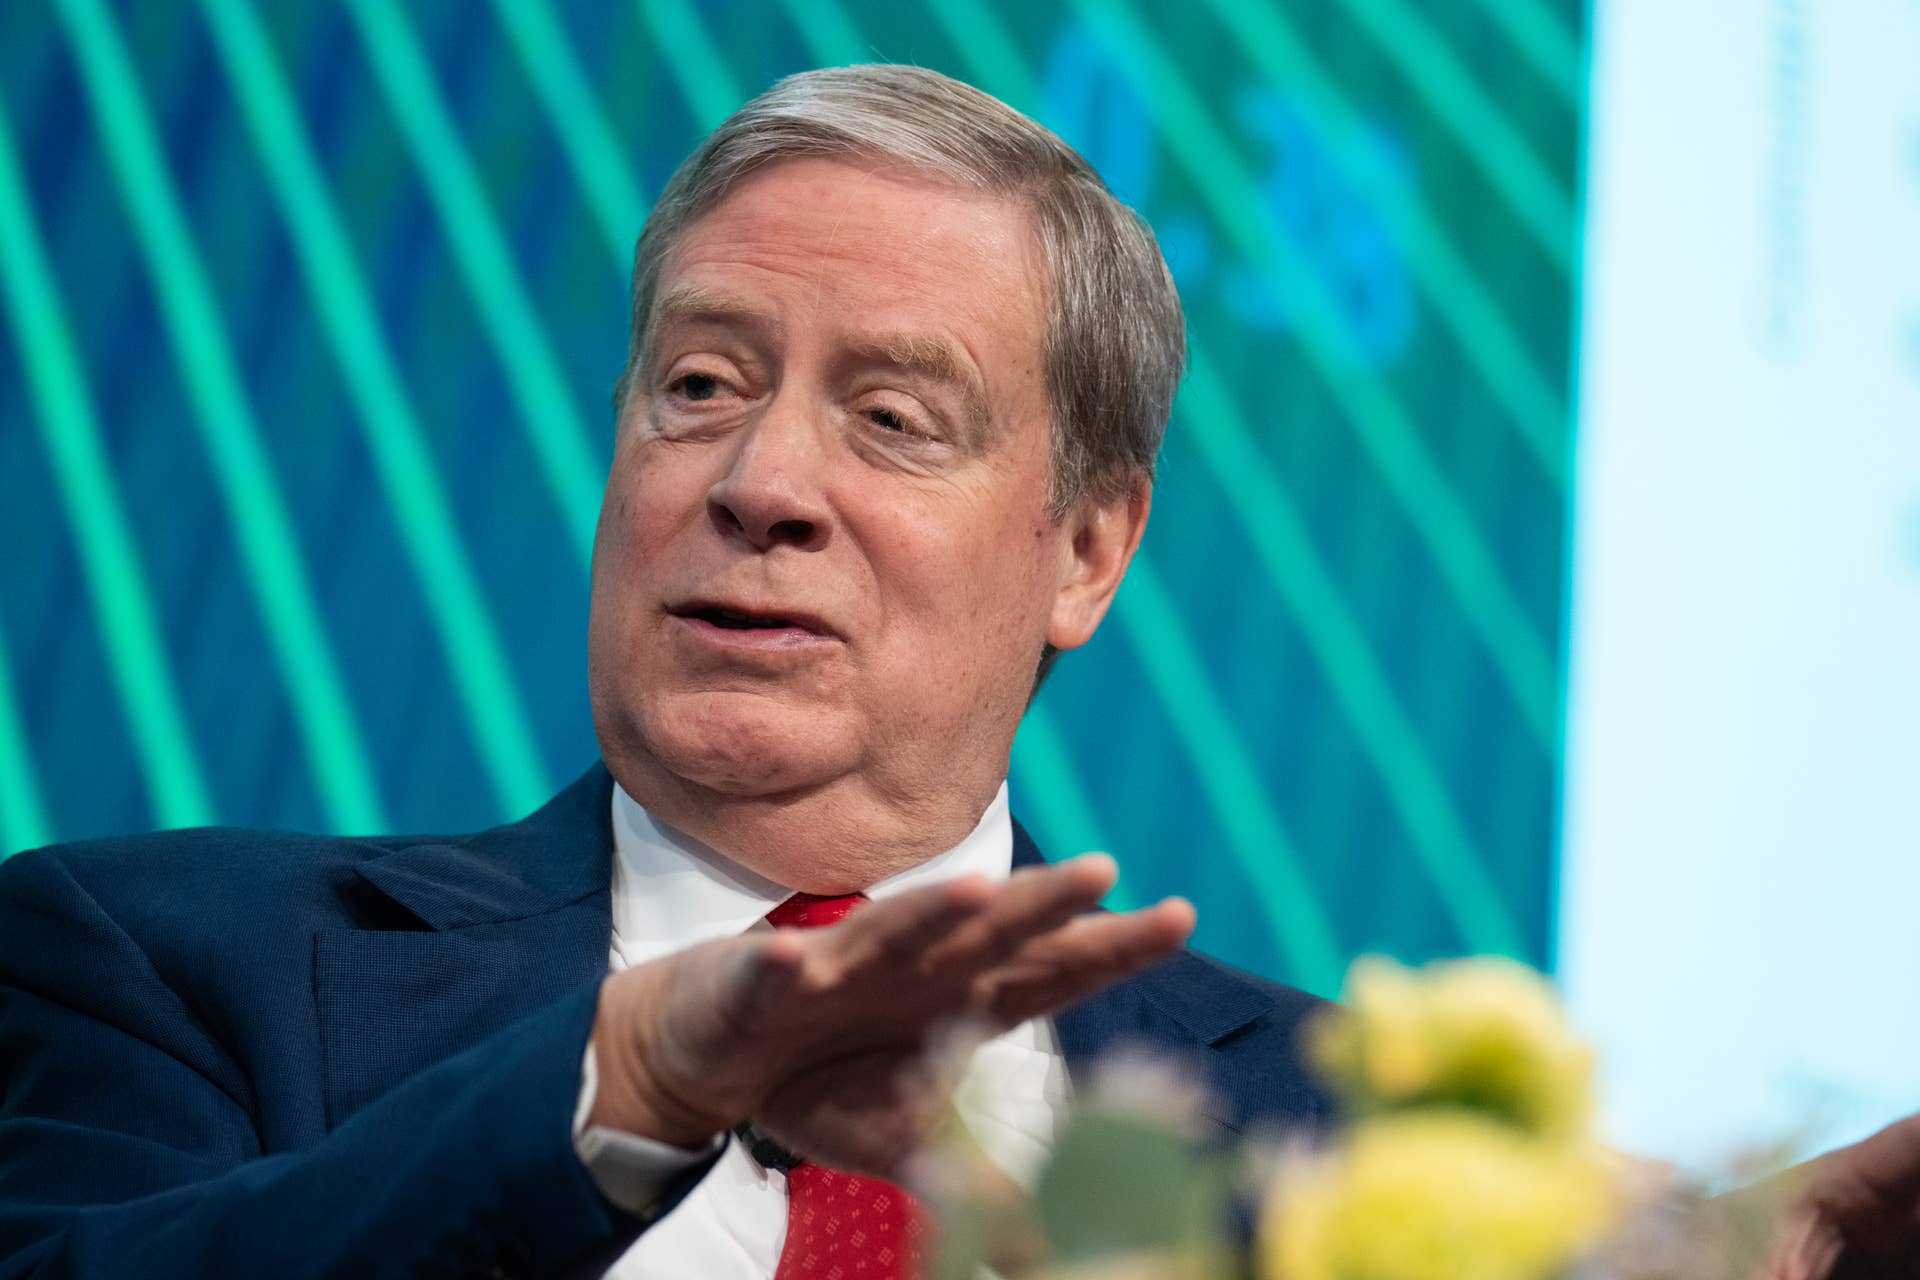
Druckenmiller’s warning came at a Piper Sandler conference in New York, where he also targeted Federal Reserve officials who say current monetary policy is restrictive.
His thesis is straightforward: Look at the financial markets.
Druckenmiller thinks asset prices throughout the globe are not indicative of an economy that is suffering from too-tight monetary circumstances. It’s a critical difference for investors.
If Druckenmiller is correct, there may be less justification for the Fed to cut rates than investors hoping for softer monetary policy want.
His warning has implications far beyond the bond market, since Treasury rates already are under rising pressure.
Stanley Druckenmiller says Federal Reserve rates are too low
Druckenmiller did not alter his verdict on monetary policy.
“Committee members on the Fed who keep saying Fed fund rates are restrictive are just ridiculous,” Druckenmiller said, according to Investing.com.
His thesis speaks to one of the biggest problems facing policymakers and investors: Is the interest rate high enough to cool the economy and tame inflation?
In normal times, when monetary policy is tight, higher borrowing rates are anticipated to dampen demand, limit investment, and finally take the heat out of inflation.
Druckenmiller does not feel the present financial circumstances warrant the label. “I believe in common sense, and all you have to do is look at asset prices around the world,” he said, as the Financial Times reported.
Related: Stanley Druckenmiller triples stake in airline giant
The comments suggest that investors shouldn’t assume that today’s interest rates are very burdensome just because they’re high relative to most of the post-financial-crisis era.
For Druckenmiller, it’s about how markets and the economy are reacting.
The difference has important implications. If monetary policy is not truly restrictive, more rate cuts might be particularly troublesome if inflation pressures linger.
Druckenmiller’s remarks also come amid unique political and policy circumstances.
He has long been a mentor to Treasury Secretary Scott Bessent and a close associate of Federal Reserve Chair Kevin Warsh, according to Fortune.
Although Druckenmiller said he is no longer allowed to speak with Warsh, he described him as one of his “closest friends” and a “great Fed chair,” the Financial Times noted.
That relationship makes Druckenmiller’s critique particularly noteworthy, as investors attempt to decipher where U.S. monetary policy is headed next.
Rising Treasury yields raise stakes for Druckenmiller’s warning
Government bonds were under selling pressure due to inflation from President Donald Trump’s Iran conflict, growing U.S. public debt, and large bond issuance by artificial intelligence businesses, CNBC reported.
Treasury prices are falling and yields are rising.
Those higher yields don’t remain isolated inside the government bond market. They may impact borrowing costs across the economy, from mortgages and corporate debt to company investment and the rates consumers are charged.
They may also have major ramifications for share prices.
Yields on government bonds are higher, meaning investors may get better returns on investments that are typically regarded safer than stocks. That might raise the return investors need to keep pricey stocks.
More Fed:
- J.P. Morgan drops Fed rate bombshell over Warsh, inflation
- Fed interest-rate decision rocks Wall Street’s inflation fears
- BofA says Fed hike today would be one for the books
That link may be especially crucial for high-growth and technology businesses that are prized for their potential revenues years in the future.
So Druckenmiller’s caution isn’t only about what the optimal federal funds rate should be. It’s also a cautionary tale about the assumptions investors make when pricing assets.
A market that expects borrowing prices to fall might react quite differently from one that is bracing for rates to stay high.
Investors positioned expecting much softer monetary policy may need to rethink such expectations if Druckenmiller is right that rate cuts are no longer essential. But it doesn’t automatically guarantee the Fed will boost rates.
Druckenmiller’s remarks were mostly along the lines of his opinion that rates are too low and don’t need to be dropped further.
Still, his reasoning poses a tougher dilemma for Wall Street. If the economy does not need lower rates and bond yields are already heading up, the age of investors relying on ever-cheaper money may be tougher to sustain.
Druckenmiller also challenges Treasury Secretary Scott Bessent
Druckenmiller didn’t stop at criticizing Federal Reserve policies. He even took on the bond-market attitude of Treasury Secretary Scott Bessent, despite their lengthy friendship.
In August, Druckenmiller attacked Bessent’s enlarged bond-buyback program in an opinion article in the Wall Street Journal. The extended program, which began in September, called for a $6 billion operation.
But according to Investing.com, many Wall Street investors have been dissatisfied with the continued rise in Treasury rates.
This is another dimension to the discussion about U.S. borrowing rates. Treasury buybacks and Federal Reserve interest rate choices are separate policy instruments, but both operate in an environment where the government must finance itself and the bond market is under pressure.
The Treasury needs to fund federal borrowing, and investors are always deciding what return they want for holding government paper. Higher returns may make the funding extremely costly.
The story says Druckenmiller was a longstanding mentor to Bessent, so the clash isn’t coming from someone who doesn’t know the Treasury secretary well.
His larger message still holds true. He does not believe that policymakers should presume that financial conditions would have to ease.
This creates an unpleasant tension for Wall Street. Investors tend to like lower interest rates since they cut borrowing costs, stimulate economic activity, and make risk assets seem substantially more appealing. Yet lower rates are not always beneficial if they happen when inflationary pressures remain strong.
The Fed needs to decide whether cutting borrowing rates would help foster sustainable economic expansion or fuel inflation concerns.
Clearly Druckenmiller feels that policymakers should be more worried about the latter.
Stanley Druckenmiller’s warning challenges Wall Street’s rate outlook
Druckenmiller’s new statements present investors with a simple but profound question: What if rates don’t need to fall?
The response may have consequences throughout financial markets for investors who have waited years for softer monetary policy.
Druckenmiller, who thinks U.S. borrowing rates are currently too low, said he doesn’t see a need for more rate cuts. He also dismissed Federal Reserve officials’ view that current monetary policy is restrictive.
Some of his proof is there in front of our faces.
Druckenmiller does not think monetary policy is choking the economy and causing asset prices around the globe to rise.
Meanwhile, the bond market is sending another big signal. Inflation fears, rising U.S. government debt, and substantial corporate bond issuance cloud the future for rates and put pressure on Treasury bonds.
The situation gives policymakers little room for error. If the Fed cuts rates too quickly while inflation persists, it risks worsening price pressures. If monetary policy is excessively tight for too long, however, the Fed risks unintentionally undermining economic activity.
Druckenmiller feels policymakers are overly focused on the second risk.
For Wall Street, the implications are far deeper than Federal Reserve meetings. Interest rates affect stock prices, business finance, mortgages, government borrowing costs, and investors’ desire to take risks.
A prolonged spell of higher rates would compel investors to rethink assumptions constructed around cheaper money.
Druckenmiller’s remarks don’t dictate what the Federal Reserve will do next. Yet one of Wall Street’s most recognizable macro investors is stating his opinion with extraordinary clarity.
And when the Treasury market feels the heat, investors may find it harder to disregard that warning.
Related: Citi says Fed rate hike could deliver stock market shock