As retail investors, we’re all feeling a tad overwhelmed by the recent headlines here at TheStreet about shifting Federal Reserve interest rates, surging Treasury yields, and persistent sticky inflation.
Recently, strong economic data and higher energy costs pushed the 10-year Treasury Yield to 5.34%, its highest intraday level since 2002.
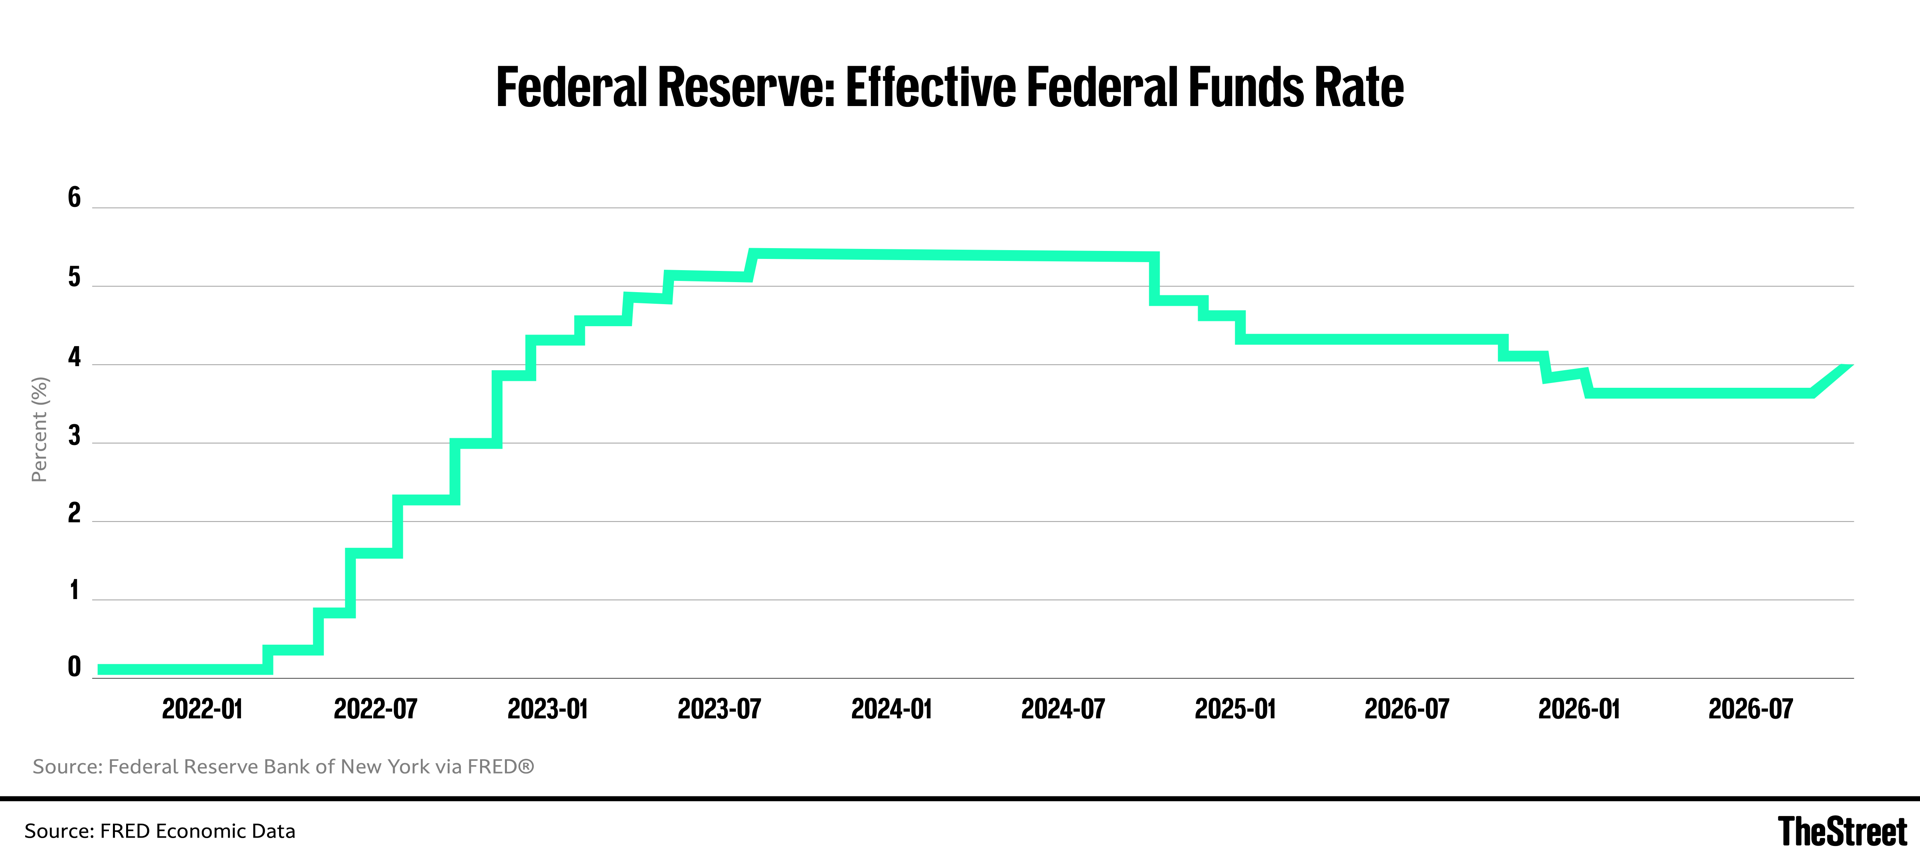
These developments have fueled multiple market conversations about an extended tightening cycle at the Fed with more rate hikes to come after the September increase in the benchmark Federal Funds Rate to the 3.75% to 4.0% range.
However, a new UBS Wealth Management note sent to TheStreet anticipates “one further rate increase in December,” and its experts say “resilient economic growth and robust corporate earnings should help equities withstand moderate policy tightening.”
Whew.
Understanding the markets and Fed rate increases
The decision by the policymaking Federal Open Market Committee that raised the federal funds target rate by a quarter point in September was driven largely by high energy prices and robust economic indicators.
Despite these pressures, underlying economic metrics show encouraging signs of stabilization, according to UBS.
More Fed:
- J.P. Morgan sees Fed rate hikes going out with a bang this year
- October Fed rate hike hinges on two looming economic reports
It cited the three-month annualized rate of core Personal Consumption Expenditures — the Fed’s preferred inflation gauge — as having dropped to 2.05% in August, the lowest level since July 2024.
Plus, UBS said the September labor report indicated a cooling trend, with nonfarm payrolls rising by just 29,000, falling well below consensus expectations.
Fed policy discussions also remain balanced, the note said. This includes comments from Fed Governor Christopher Waller, which I reported on, indicating that he is not “greatly concerned’’ about higher interest rates causing a “damaging slowdown in the economy.” Instead, he is focused on keeping consumer and business inflation expectations anchored.
What a Fed rate increase means for your portfolio
For everyday investors, a measured Fed hiking cycle doesn’t spell disaster for the broader market, UBS said.
In fact, historical data shows that past U.S. economic downturns generally did not begin until at least two years after the Fed kicked off rate increases.
Solid corporate fundamentals further back this: UBS forecasts S&P 500 earnings growth of 25% in 2026 and 14% in 2027.
This profit growth should provide a strong cushion for equities, even as borrowing costs edge slightly higher, UBS said.
Actionable strategies for retail investors after Fed rate hike
UBS suggests considering the following approach to navigate these shifting conditions.
Maintain diversified equity exposure. Do not try to time the market to a single projected Fed rate hike. Instead, spread your investments across various regions, sectors, and return drivers while carefully managing single-stock concentrations.
Capitalize on fixed income. Higher starting yields present attractive entry points. Consider rating a fixed income favorably by adding portfolio income through medium- to long-term duration high-quality bonds, as well as medium-maturity credit from strong investment-grade issuers.
Stay cautious on extremes. While quality bonds offer great value, remain diligent regarding the longest debt maturities and lower-quality credit.
Fed’s dual mandate focuses on jobs, prices
The Fed’s dual mandate from Congress requires maximum employment and price stability.
Yes, it’s a tricky balance of monetary policy because:
- Lower interest rates support hiring but can fuel inflation. This risks fueling further inflation, potentially leading to an inflationary spiral.
- Higher rates cool prices but can weaken the job market. This increases the cost of borrowing and further stifles economic activity.
How an interest-rate hike hits home
The Fed’s September interest-rate hike, the first since January 2023, sent ripples through the entire financial system with the most immediate pressure hitting short-term borrowing such as variable-rate credit cards and student loans.
Indirectly, it impacted fixed-rate mortgage rates, which rely on Treasury yields, as well as corporate debt and capital investment.
The good news? Interest rates on savings accounts and CDs could see an increase.
What the next Fed rate hike means for your investments
The CME Group’s FedWatch Tool shows traders pricing in a roughly 19% probability of a Fed rate hike at its Oct. 27-28 FOMC meeting, with expectations of an 89% rate hike by its Dec. 8-9 meeting.
UBS said a December rate hike should be viewed as part of a measured normalization rather than an economic derailment.
“U.S. nominal GDP was growing 6.6% year-over-year at the end of the second quarter, comprising around 2.1% real growth and a 4.4% increase in the broad price level,’’ the note said. “This can help companies grow revenues and profits in current-dollar terms.”
Related: Hot September CPI numbers, possible Fed rate hikes spark anxiety for midterm voters