Nvidia’s (NVDA) backing was expected to give CoreWeave (CRWV) an incredible competitive edge in the AI boom. Yet even a $2 billion investment from AI’s poster child hasn’t prevented a punishing pullback in the cloud infrastructure provider’s stock price.
In January, Nvidia scooped up nearly 23 million CoreWeave shares at $87.20 apiece, strengthening a partnership built on Nvidia graphics processors and a $6.3 billion agreement to buy unused cloud computing capacity through 2032.
Despite securing a remarkable number of customer contracts to rent out AI computing power, CoreWeave shares closed out November 6 at $46.40, nearly 47% below Nvidia’s buy-in price, as debt investors demand strong compensation for lending to the company.
In her latest market commentary, Cathie Wood highlighted an uncomfortable question for shareholders.
The ARK Invest boss questions whether CoreWeave can finance the AI infrastructure required to fulfill its enormous contracts without debt costs that would overwhelm the business, coming just before a crucial earnings test.
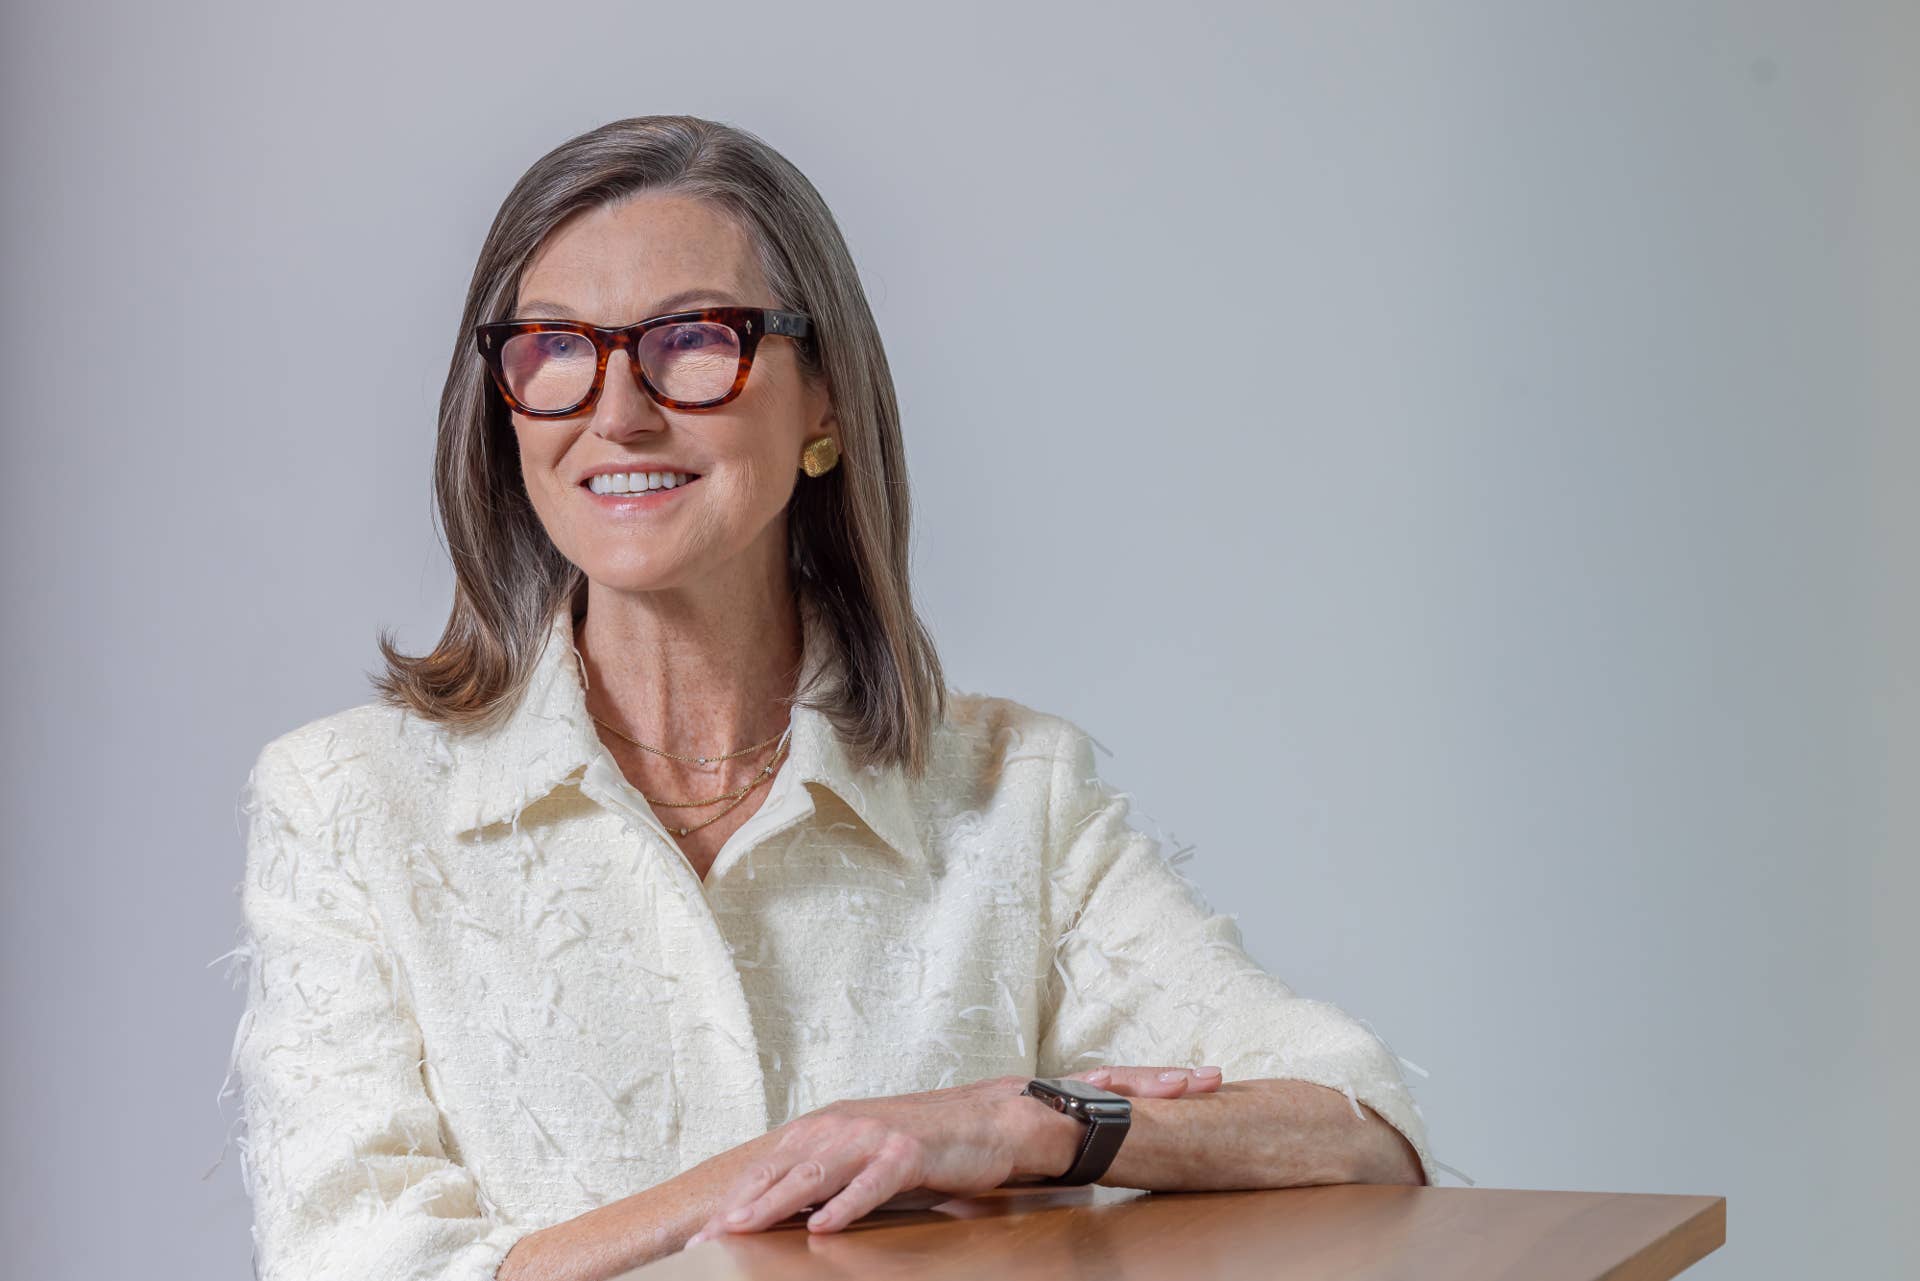
Cathie Wood sees a debt warning even Nvidia can’t erase
Speaking on her November 7 webcast, Wood said that credit markets now demand far more default protection for CoreWeave than for typical high-yield corporate borrowers.
For perspective, a credit-default swap is essentially insurance against a borrower failing to repay its debt, with higher spreads underscoring greater lender anxiety. By November 6’s close, CoreWeave’s five-year credit-default-swap spread sat near 1,155 basis points after peaking out at 1,289 basis points the prior day as reported by 24/7 Wall Street.
More Cathie Wood:
- Cathie Wood buys $47 million of popular semiconductor stock
- Cathie Wood buys $11.2 million of popular AI stock
- Cathie Wood buys $9.1 million of tumbling tech stock
That’s roughly four times the roughly 300 basis points Wood cited for comparable high-yield companies.
“And I think it’s interesting because CoreWeave’s contracts are with primarily the hyperscalers and they are backed by those contracts. So they should be good money. And yet the market just doesn’t believe it.”
Wood’s comments expose a pertinent financial gap.
Signing contracts with creditworthy giants such as Microsoft or Amazon doesn’t automatically offer a supplier cheap capital to build the facilities those deals require.
Unlike diversified tech leaders supported by profitable software and advertising empires, CoreWeave is a specialist neocloud operator. Wood warns that if local political pushback or power shortages slow data center construction across states and cities, CoreWeave faces an outsized risk.
Nevertheless, Wood feels CoreWeave’s default spreads will likely calm down once broader post-election market jitters settle.
CoreWeave’s $104 billion backlog hides a costly financing trap
Lenders are uneasy because CoreWeave must spend billions of dollars upfront on chips, real estate and power infrastructure long before its customer contracts generate cash.
According to its June 30 balance sheet, CoreWeave carried $35.55 billion in debt principal, $5.52 billion in cash and $5.02 billion in shareholders’ equity. That equals a steep debt-to-equity ratio of 7.1 times, which basically means that the company owed $7.10 in debt principal for every dollar of book equity.
Moreover, that tremendous leverage is already eroding its operational flexibility. In Q2, CoreWeave generated $2.58 billion in sales but incurred $640 million in net interest expense, which resulted in a massive $626 million net loss. Roughly one dollar of every four dollars in quarterly sales went toward net interest costs.
Over the first half of the year, operating cash flow of $3.66 billion fell $10.45 billion short of the $14.12 billion spent on property and equipment.
The bulls try to counter that argument by saying that CoreWeave’s midyear sales backlog, along with more than $25 billion in subsequent commitments, justifies heavy borrowing. Moreover, Wood argued that power and chip bottlenecks might force healthy efficiencies across AI development rather than repeat the wasteful late-1990s telecom bubble.
Cathie Wood’s Nvidia buying sets up a tougher CoreWeave test
Strong AI demand and high borrowing costs underscore the need for investors to be much more selective about which AI infrastructure companies they support.
ARK Invest’s recent trades highlight that distinction. After buying roughly $61.9 million of CoreWeave shares across selected sessions from October 6 to October 19, Wood’s funds sold about $20.3 million of the stock across November 5 and November 6. During the November 5 tech selloff, ARK purchased approximately $45.8 million of Nvidia shares.
Portfolio sales could reflect routine position sizing or liquidity management rather than a bearish verdict. Still, adding the chipmaker while trimming a leveraged data center partner underscores the stakes for CoreWeave’s Q3 earnings report on November 10.
Wall Street forecasts around $3.5 billion in sales, up 159% from $1.36 billion a year earlier, according to Zacks. Analysts also forecast a loss of $1.17 per share, much wider than the $0.08 loss reported a year ago.
Though the forecast sits within CoreWeave’s own sales guidance of $3.45 billion to $3.6 billion, projected quarterly interest expenses of $860 million to $940 million will continue to keep debt costs and its bottom line in focus.
Investors will watch updated debt balances, interest expense, CapEx and the rate at which contracted backlog converts into active, revenue-generating capacity. If borrowing costs stabilize as deployments scale, Wood’s expectation for calmer credit markets could gain traction.
However, if financing grows costlier, even surging revenue may not soothe Wall Street. The next test isn’t just AI demand. It’s whether CoreWeave can afford to deliver it.
Related: Bank of America has unexpected advice for tech stock investors after midterms