Record profits are supposed to reassure investors. Micron Technology (MU) is showing why that doesn’t always work in a stock market obsessed with what comes next.
The memory-chip maker has had record sales and profits. Wall Street doubts the artificial intelligence boom can sustain those profits, so its shares have plummeted.
Micron stock plunged 13.9% on Nov. 20, closing at $594.51. That left shares down 44.2% from their Sept. 30 closing price of $1,065.11.
Billionaire investor David Tepper is facing an unpleasant test as a result of the drop.
His investment firm, Appaloosa LP, increased its Micron stake by 28.2% during the third quarter, making the chipmaker its largest reported stock holding.
According to Appaloosa’s Nov. 16 SEC filing, the fund owned 1.25 million Micron shares worth approximately $1.33 billion as of Sept. 30.
By November 20, the value of those shares will have decreased by around $588 million to $743 million, if Appaloosa has kept them. Neither a real investment loss nor any subsequent transactions are disclosed in the statement.
As the memory-chip industry gets ready for another potential change in supply and demand, the more important concern for regular investors is whether Micron can maintain its extraordinary profitability.
David Tepper’s Micron investment reveals a bigger AI bet
Tepper invested in more than just a single semiconductor stock.
Additionally, during the third quarter, Appaloosa raised its holdings in Nvidia (NVDA) by almost 31%. The fund added exposure to additional companies engaged in computer infrastructure by establishing new stakes in Oracle (ORCL) and Applied Materials (AMAT).
Still, Micron accounted for around 17.6% of Appaloosa’s $7.56 billion stated securities portfolio, making it its biggest reported holding.
Memory chips are crucial to artificial intelligence, so that concentration is important. Advanced processors need high-bandwidth memory to handle massive amounts of data, while data centers need conventional memory and storage.
Related: Micron’s $35 billion decision comes with a consumer catch
The interest may be explained by Micron’s recent financial results.
Micron reported fiscal fourth-quarter revenue of $54.23 billion, compared with $11.32 billion a year earlier. Full-year revenue reached $133.19 billion, up from $37.38 billion in fiscal 2025.
The increase in profitability was much more remarkable.
Micron’s fiscal year adjusted gross margin was 81.1%, up from 40.9%. Before operating expenses and other costs, the company made 81 cents per dollar of revenue.
However, the results have been different for investors who purchased Micron close to its September pricing.
A hypothetical $10,000 investment at the Sept. 30 closing price of $1,065.11 would have been worth approximately $5,582 at the Nov. 20 close, excluding dividends and transaction costs.
That’s a $4,418 decline in less than two months.
For individual stockholders, the disparity draws attention to a crucial differential. When investors begin to question whether future profits will meet prior expectations, a firm might continue to thrive even as its stock price drops.
Additionally, Micron’s most recent client agreements might provide a crucial hint about what comes next.
Micron’s $32 billion customer protection comes with a catch
The market for memory chips has always been unstable.
Prices and profits rise when producers are unable to meet the demand for chips. However, costs might drop significantly as more manufacturing lines and firms begin to supply the market.
Micron thinks things could be different now.
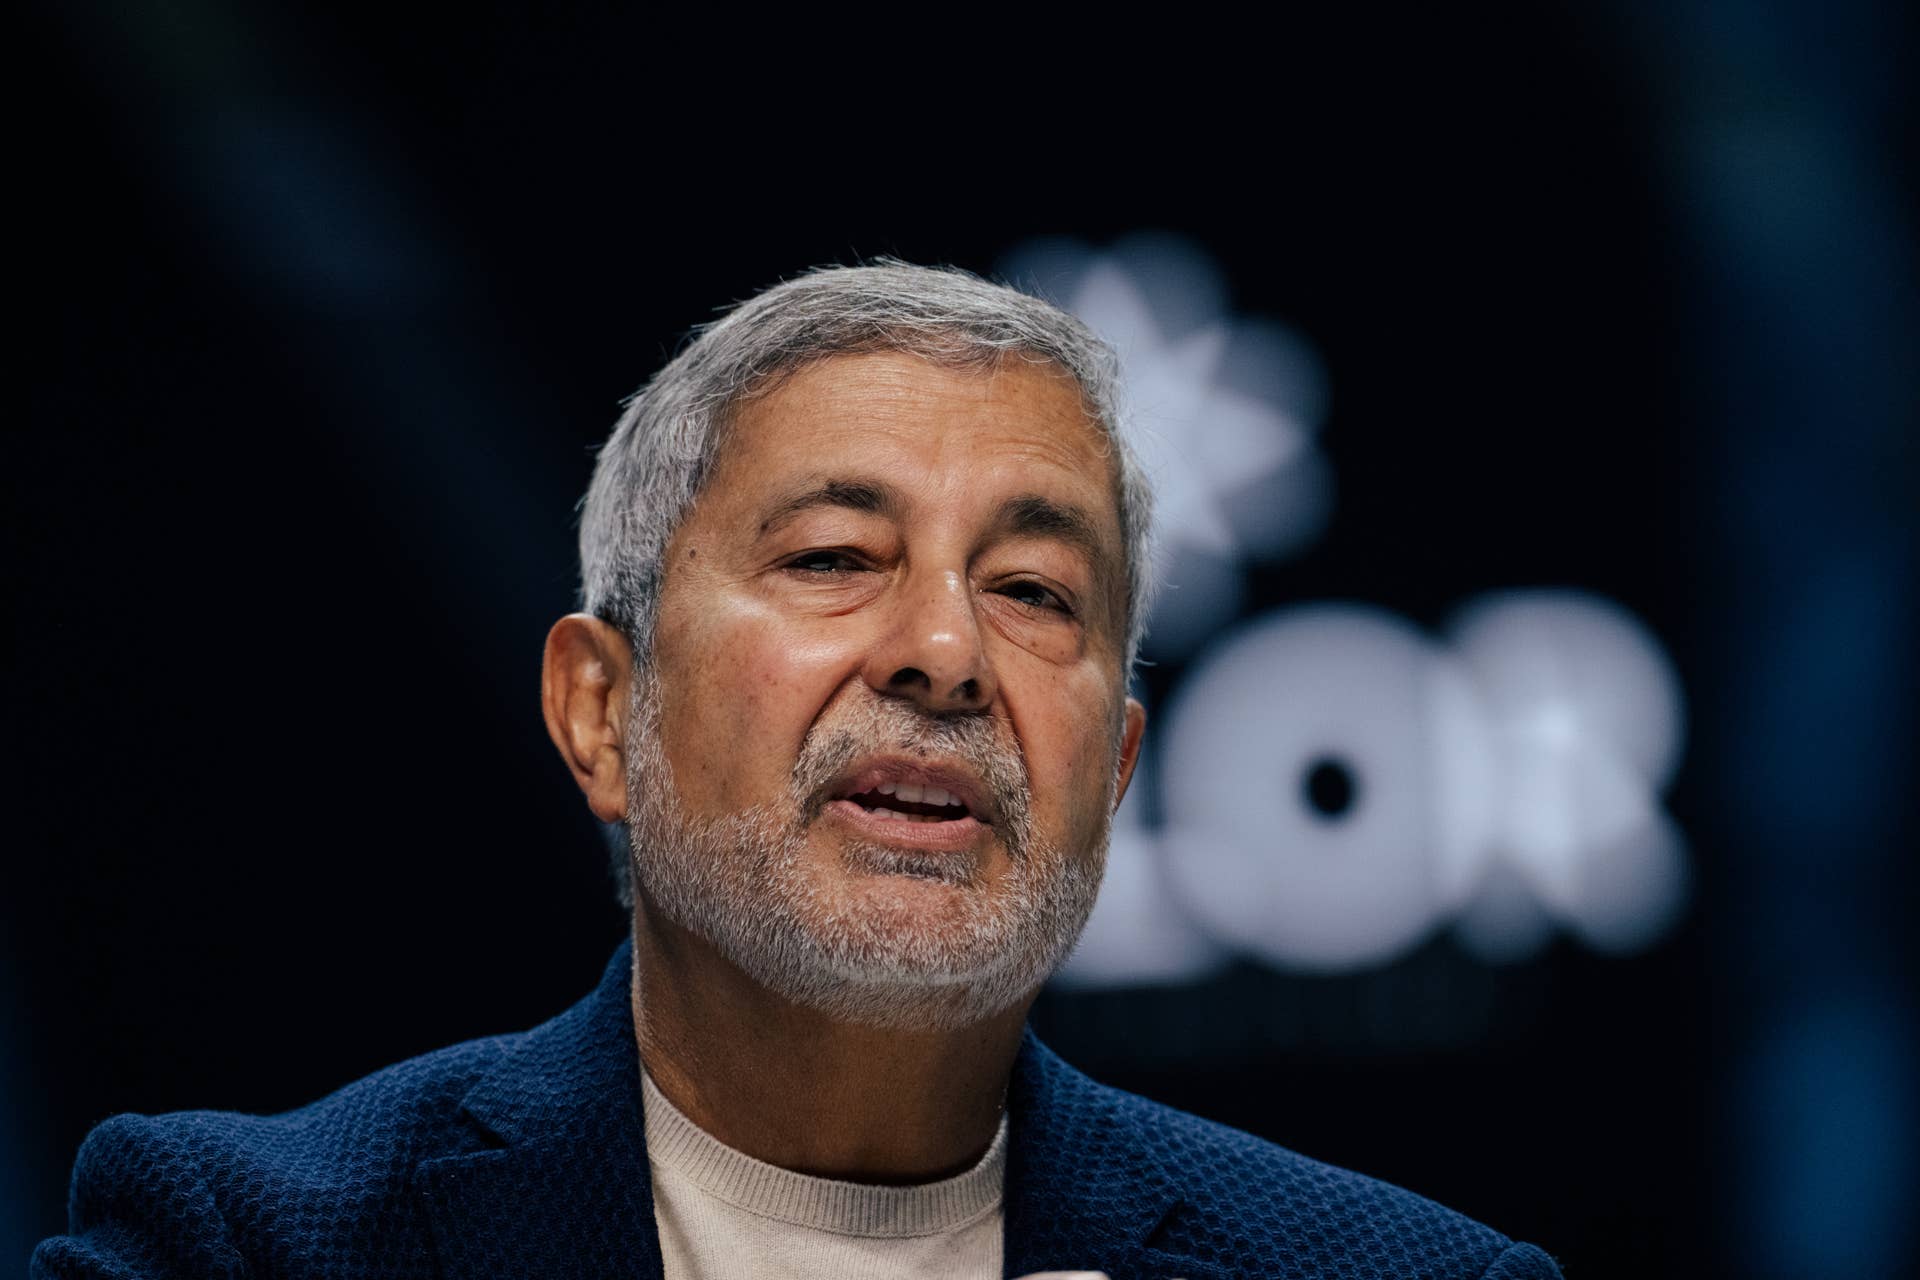
During the TomorrowX Summit on Nov. 18, CEO Sanjay Mehrotra said demand remained strong and industry supplies were expected to tighten further in 2027 and 2028.
Additionally, he said that 75% of Micron’s anticipated 2027 production had already been sold and that customer conversations would continue until 2028.
The comments suggested that major buyers remained eager to secure future supplies despite the recent market turmoil.
“Demand remains robust for our business.”
Additionally, Mehrotra highlighted 26 significant client agreements with upfront cash payments and other financial obligations totaling almost $32 billion.
These multiyear agreements help Micron plan production investments and gain more insight into client demand.
Some contain clauses that mandate that clients fulfill their payment responsibilities or buy agreed-upon amounts even if their needs alter.
Such arrangements might lessen the company’s revenue’s susceptibility to unexpected order cancellations.
Mehrotra did, however, also reveal a significant qualifier.
While some agreements do not mention prices, others have set pricing or pricing ranges.
Future consumer demand does not guarantee that every memory chip will sell at today’s lucrative prices.
Additionally, the $32 billion amount does not reflect $32 billion in income that has already been recorded but rather a mix of deposits and financial obligations.
The difference is important for shareholders.
Customer agreements could help protect Micron against a sudden collapse in orders, but their ability to protect profit margins depends on contract terms and future memory prices.
Why Micron’s extraordinary profits face a new threat
A recent memory-industry projection highlights the uncertainty surrounding Micron’s future.
Research firm TrendForce warned on Nov. 19 that NAND flash memory prices could begin declining in early 2027 as manufacturers increase supplies and some customers reduce orders.
Solid-state drives, laptops, and cellphones all employ NAND chips to store data. Although they vary from the high-bandwidth memory that powers sophisticated AI systems, they both support Micron’s operations.
TrendForce projects that the global supply of NAND bits will rise by 25% to 30% in 2027. Meanwhile, Chinese cloud providers have lowered their projected business storage product orders by more than the extra demand that North American clients are expected to generate.
According to the company, NAND contract prices may drop by up to 5% in the first quarter of 2027, with more significant drops starting in the second quarter.
More Artificial Intelligence:
- AI investments fail when companies ignore the hard part of transformation
- Morgan Stanley issues a fresh warning about AI stocks
- CrowdStrike gives companies a ‘kill switch’ as bots go off script
The forecast does not mean demand for Micron’s AI-focused memory products is collapsing.
In fact, the company’s ongoing investment in improved technology and long-term client agreements indicate that there is still significant demand.
For investors, however, the distinction between robust AI demand and declining traditional memory pricing may become more crucial.
Micron projects an adjusted gross margin of 86.25% and fiscal first-quarter sales of around $61.5 billion in 2027.
The business would make around $53.04 billion in gross profit per quarter at such levels.
Quarterly gross profit would drop by around $3.08 billion if the margin dropped by five percentage points but sales stayed the same.
That is not an estimate of Micron’s performance; rather, it is a hypothetical sensitivity calculation.
However, it shows how when profitability is abnormally high, even a little margin reduction might have a significant impact on profits.
This raises an unsettling potential for investors.
Even with record sales, a firm may still let shareholders down if its profit margins deteriorate faster than the market anticipates.
What David Tepper’s Micron bet means for investors
Tepper identified a significant potential in a business that supplied vital components for the AI economy, as seen by his Micron holdings.
A quarterly securities report, however, merely offers a historical overview of an investor’s assets.
The fund does not disclose its current position, purchase prices, hedging agreements, or overall investing strategy.
Therefore, replicating the declared position would require individual investors to make a judgment based on insufficient information.
Examining whether the presumptions behind Micron’s latest results are still valid is a more beneficial strategy.
Evidence suggests that growth will continue.
The management of Micron anticipates increased demand in 2027, and compared to the shorter contracts typically seen in the memory sector, its multiyear client agreements provide more revenue predictability.
Additionally, the corporation has predicted record sales and very high profitability for another quarter.
However, the dangers are becoming more apparent.
According to TrendForce’s NAND projection, more supply may cause prices in a portion of Micron’s business to decline. But a fixed price is not always guaranteed by long-term client agreements.
As a result, Micron may continue to sell more chips even if its gross profit per dollar of sales decreases.
Therefore, the company’s anticipated 86.25% adjusted gross margin is the most crucial figure for investors to monitor.
If Micron sustains profitability close to that level, it would strengthen the argument that expanding AI demand and lengthier customer commitments are altering the memory industry’s economics.
Instead, a significant drop can indicate that the business is still susceptible to the price cycles that have traditionally influenced its financial results.
The September position exposed Tepper to $1.33 billion in investments. Their subsequent decrease in value shows the financial stakes.
The lesson is more general for common stockholders.
A billionaire’s conviction cannot eliminate the danger of purchasing a successful firm at a price based on unusually advantageous circumstances.
Micron’s next earnings report will be useful in determining if the memory industry’s well-known cycle is starting to reappear or whether those favorable circumstances are becoming permanent.
Related: Micron stock gets stunning $3,000 call despite 6% plunge