Discount stores have long served as an alternative to expensive supermarkets, and today, amid persistent food inflation, they have become a necessity for many budget-conscious shoppers.
But retailers built around low prices are finding that aggressive expansion to meet shoppers’ needs does not always translate into higher profits.
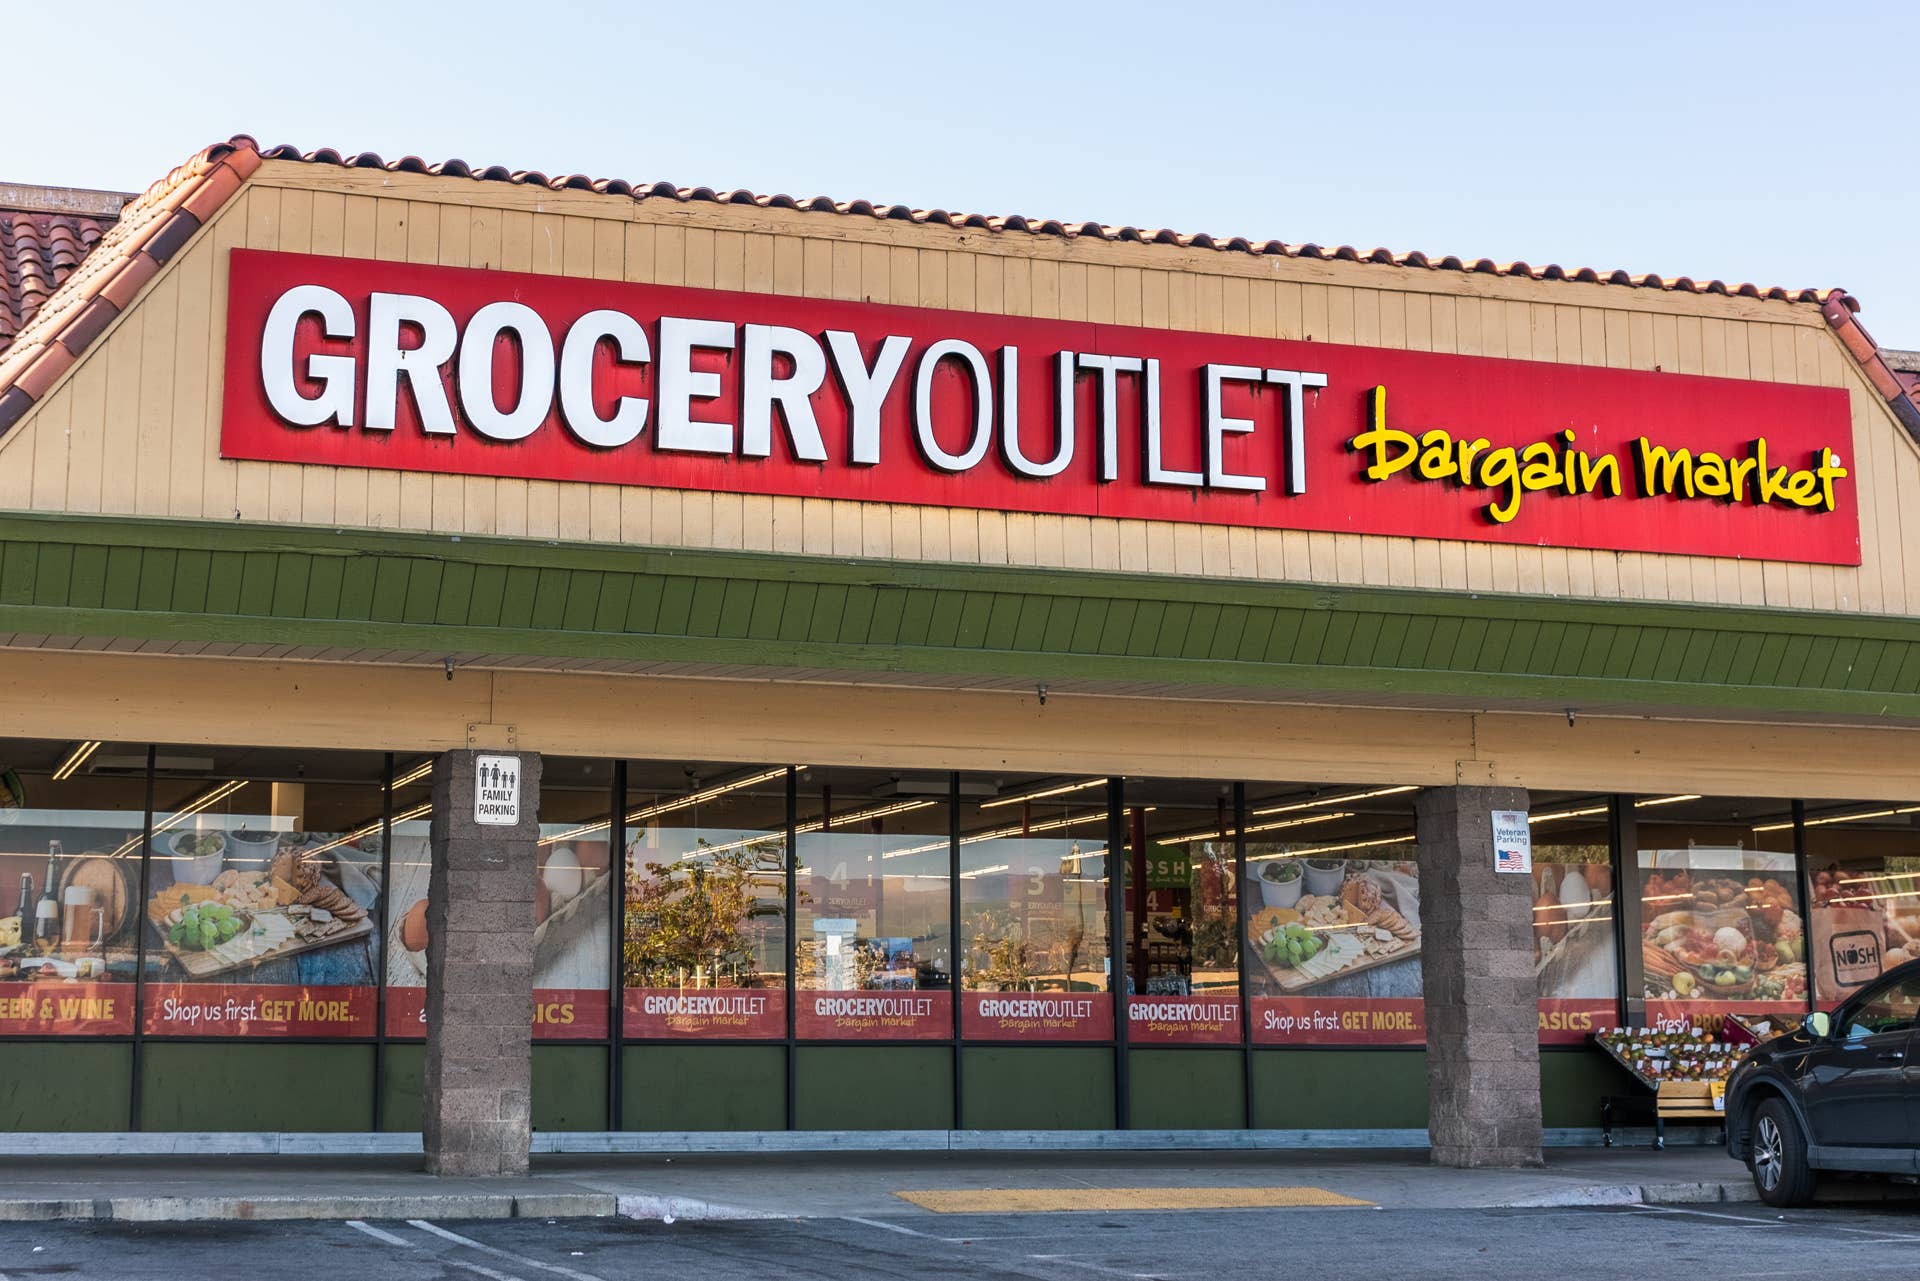
Grocery Outlet, the 80-year-old discount supermarket chain known for selling recognizable brands at steep discounts, has spent much of 2026 dealing with the consequences of expanding too quickly.
The company has closed dozens of underperforming locations, abandoned previously planned projects, and overhauled its approach to attracting shoppers.
Now, the chain is making another significant change.
Grocery Outlet plans to slow store expansion in 2027 and concentrate entirely on markets where it already has an established presence, marking another departure from its earlier growth strategy.
So, shoppers expecting a new Grocery Outlet store in their city might be in for disappointment.
The decision comes even as customer traffic improves and the company attempts to rebuild its reputation as a bargain-shopping destination.
Grocery Outlet announces slowdown in new store openings
During its Nov. 10 third-quarter earnings call, Grocery Outlet CEO Jason Potter said the retailer plans approximately 20 net new store openings in fiscal 2027.
All of those openings will be infill locations, meaning additional stores in markets where Grocery Outlet already operates.
The approach differs from its previous strategy of expanding into new markets while simultaneously adding stores in established markets.
More Retail:
- Struggling home goods chain closing more stores
- Verizon makes changes to be more like T-Mobile used to be
- Home Depot drops generous offers as customers grow harder to win
Over the past three years, roughly half of its new stores were in new markets and the other half were infill locations, Potter explained.
In 2026, approximately two-thirds of the new-store group consists of infill locations. That proportion is expected to rise to 100% next year.
Grocery Outlet now expects 30 to 31 net new stores in fiscal 2026, down from its previous forecast of 30 to 33.
Excluding the 36 stores shuttered under its optimization program, the retailer had already added 27 net locations through Oct. 3, leaving just three to four additional net openings needed during its final quarter.
From this, the planned 2027 openings represent a meaningful slowdown.
Potter acknowledged that newer stores in existing markets have generally performed as expected, but results in newer markets have been less consistent.
“We will have some work to do when we do come back around in the midterm to new market growth, refining our process there,” Potter said during the earnings call.
A separate disclosure from CFO Ian Ferry helps explain the shift.
Ferry said Grocery Outlet’s four-wall, four-year returns, a measure of profitability relative to investment at individual stores, have declined from more than 35% around the time of its 2019 IPO to approximately 20% to 25% more recently.
“They have come down over the last several years as construction costs have become elevated and CapEx required has gone up,” Ferry said.
The company is consequently focusing on locations where it can more reliably predict financial performance.
UBS analysts said in a Nov. 11 research report shared with TheStreet that the slowdown should help Grocery Outlet. The retailer will be able to concentrate resources on its turnaround while reducing capital expenditure requirements in 2027.
The bank estimates that the planned expansion represents approximately 3.5% store growth, roughly half the pace of fiscal 2025. Grocery Outlet has not announced which cities or states will receive the approximately 20 planned stores.
Grocery Outlet continues restructuring after 40 store closures
The decision follows a difficult period for the discount grocery chain.
Earlier this year, Grocery Outlet launched an optimization program targeting 36 financially underperforming stores after acknowledging that it had expanded too aggressively.
The program was approved by its board on March 2, and all 36 locations were closed in March and April. Overall, the company closed 40 stores during the first 39 weeks of fiscal 2026, including those targeted under the optimization program.
The closures were part of a broader effort to improve profitability, reduce unnecessary expenses and redirect resources toward stronger locations.
As TheStreet previously reported, Grocery Outlet also terminated leases for previously planned stores and undertook layoffs as part of an earlier restructuring. However, the financial consequences of the latest closures are lasting longer than initially expected.
In its Nov. 10 earnings release, the company increased its estimated total net restructuring charges to between $22 million and $29 million. The higher costs are primarily due to updated estimates for lease terminations and expenses for properties no longer in use.
Importantly, Grocery Outlet did not announce another round of store closures during the third quarter. Instead, it opened 14 new locations and closed none during the period, ending Oct. 3 with 561 stores across 16 states.
Grocery Outlet’s turnaround is beginning to attract more shoppers
Despite the challenges, Grocery Outlet is seeing early signs that its strategy is gaining traction.
During the third quarter:
- Net sales increased 0.9% year over year to $1.18 billion.
- Comparable-store sales rose 0.5%, reversing the declines reported earlier in the year.
- Customer transactions increased 2.4%.
- Average transaction value fell 1.9%.
The figures suggest more shopping trips, even as customers spend less per visit.
The company attributed part of the improvement to its renewed focus on opportunistically purchased products.
Unlike conventional supermarkets, which typically stock a relatively stable assortment, Grocery Outlet frequently purchases surplus and closeout merchandise from suppliers, allowing it to sell recognizable brands at substantial discounts.
As TheStreet previously reported, Grocery Outlet has been rebuilding that merchandise pipeline and restoring the treasure-hunt shopping experience that originally distinguished it from larger supermarket chains.
Potter said the company has even reduced portions of its everyday merchandise assortment to make more room for opportunistic products in its supply chain and stores.
The changes are showing results across grocery, frozen foods, and deli departments. UBS said the strategy is particularly important because opportunistic products can help Grocery Outlet offer deeper customer savings while supporting stronger merchandise margins.
However, the turnaround is far from complete.
The retailer has also changed its approach to grocery delivery, introducing in-store price parity through services including Instacart.
Potter said the move is helping to attract new shoppers and increase online basket sizes.
Grocery Outlet will outsource to independent operators
The retailer’s decision to concentrate on established markets illustrates a broader challenge for discount chains.
Opening stores in unfamiliar markets can bring new customers, but it also requires investments in distribution, marketing, and real estate without the benefit of an established local reputation.
Grocery Outlet’s latest strategy seeks to reduce that uncertainty.
The company has been testing a different approach to opening locations. It will initially operate certain new stores itself before potentially transferring them to independent operators, according to its latest SEC filing.
Historically, independently operated stores have been a defining part of Grocery Outlet’s business model. But the slower expansion strategy also presents challenges.
UBS warned that focusing on existing markets could increase leasing expenses and put pressure on operating expense ratios in the coming year.
With fewer new stores contributing to sales, the retailer will also depend more heavily on improving performance at existing locations. Even so, UBS analysts Mark Carden, Michael Lasser and Mathew Rothway expressed greater confidence in Grocery Outlet’s recovery.
In their report, the analysts raised the stock’s 12-month price target to $14 from $11.50 while maintaining a Neutral rating, citing progress in merchandise availability and a clearer path toward sustainable comparable-store sales growth.
The bank nevertheless expects near-term profitability to remain under pressure.
Higher repairs and maintenance expenses, along with continuing fuel and freight costs, are among the challenges.