I covered in a recent story how I was pricing out a storage upgrade for my PlayStation 5 because I needed more room for Grand Theft Auto 6.
Then I saw what the SSD I wanted would cost. Suddenly, I was far less worried about making room for the game than making room in my budget.
Perhaps the sticker shock reminded me of a story I wrote in October, when Intel warned that rising memory costs were slowing down PC demand. The AI boom continues to drive production toward high-bandwidth memory used in data centers, leaving far less capacity for conventional RAM.
My PS5 drive uses flash storage, not RAM, but both continue to get more expensive as demand for AI hardware grows.
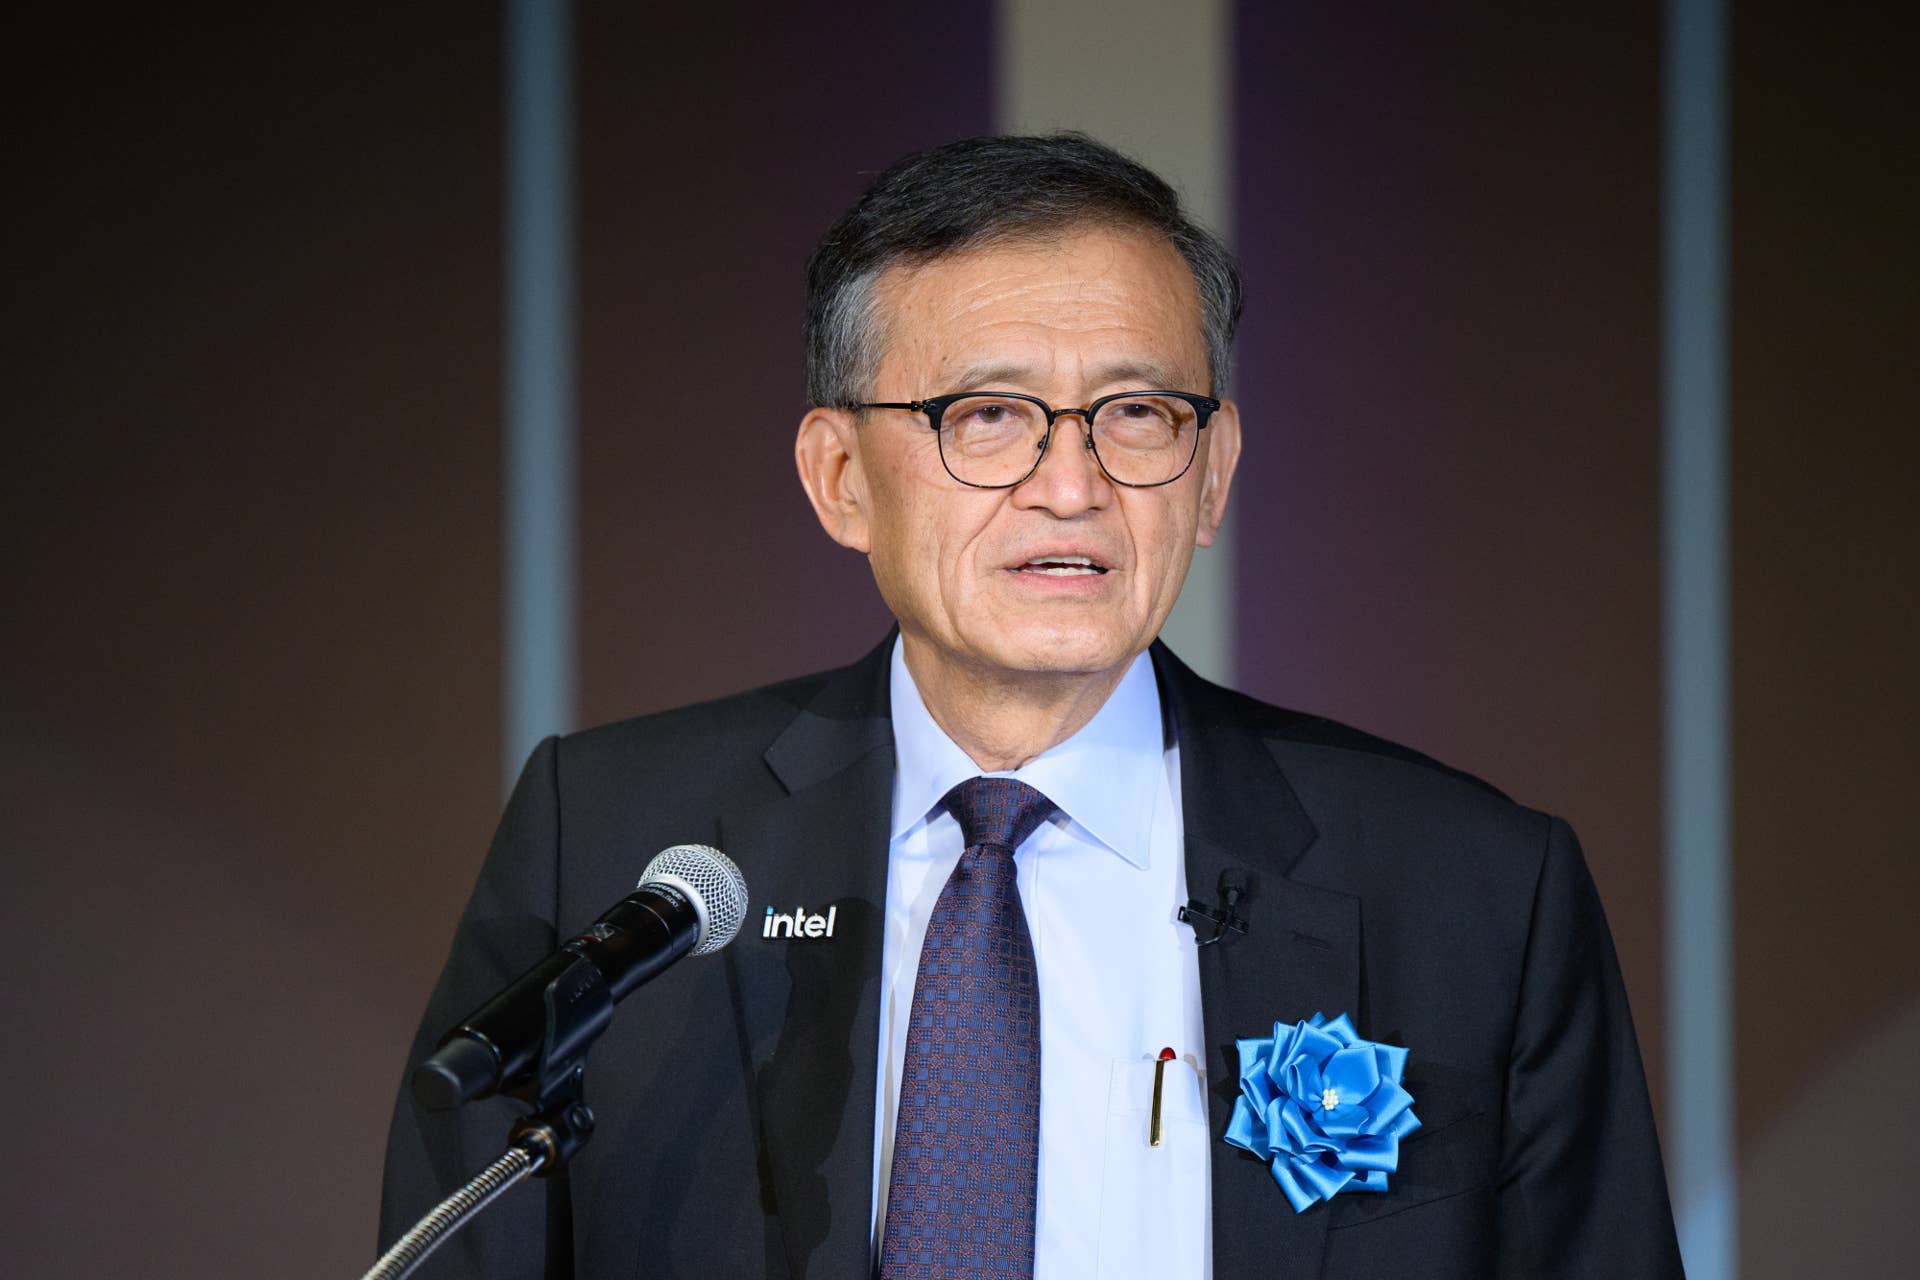
Intel (INTC) CEO Lip-Bu Tan told Yahoo Finance that buyers willing to pay more might not get enough memory. For Micron (MU) investors, it’s a strong signal that its pricing power could last well into 2027.
Intel’s memory warning goes beyond sticker shock
Intel CEO Lip-Bu Tan believes that even with buyers willing to pay higher prices for memory, they might not be able to get it.
“Yes, six, seven times. And even if you’re willing to pay, you may not get it,” he said, arguing that the shortage could get a lot worse in 2027.
TrendForce offers a clearer yardstick.
In September, it forecast that conventional DRAM contract prices would rise 10% to 15% from the prior quarter in the final three months of 2026, with NAND flash up 15% to 20%, with the pressure extending far beyond the high-bandwidth memory used in AI accelerators.
That plays right into Micron’s proverbial hands, and its recent results show what a tight market can mean on the selling side.
Fiscal Q4 sales climbed to $54.23 billion from $11.32 billion a year earlier. Adjusted earnings rose to $33.42 a share from $3.03, and adjusted gross margin reached 87%.
The question for investors isn’t whether the squeeze has helped Micron. It’s how much longer it can.
Micron has already locked in higher prices for much of 2027
Tan described Intel’s comeback as “a multi-year turnaround.”
The memory shortage in many ways explains why even a better processor might not be able to fix everything. A PC maker needs enough affordable RAM to build a machine customers will buy.
Micron is on the other side of that negotiation, and some of its customers are committing well before they need the chips.
More Micron:
- BofA sees 80% upside for Seagate stock, but Micron shares look cheaper
- Micron stock gets stunning $3,000 call despite 6% plunge
- Micron helps revive U.S. metal refining as China dominates supply
On its September earnings call, Micron said it reached agreements for the vast majority of its calendar 2027 high-bandwidth memory supply at significantly higher prices than in 2026.
It reported $32 billion in customer financial commitments across 26 strategic agreements and extensions, primarily in cash deposits. That isn’t $32 billion in recognized sales.
Moreover, it’s important to know that some agreements have price floors and ceilings, so locking in demand doesn’t exactly mean Micron captures every dollar of a further price spike.
In addition, there’s a limit to what buyers will absorb. TrendForce said on Nov. 6 that some smartphone makers were opting for lower-cost reworked memory components, especially for budget models.
So there is a flip side to that argument: Even though scarcity gives suppliers leverage, it also gives customers a reason to redesign products, trim specifications, or delay orders.
Meanwhile, Micron expects its first Idaho fab to begin producing wafers in mid-2027. It would be important to see how quickly the new output translates into shipments, not just when the fab starts.
Micron looks cheap at 4.5 times earnings, but here’s the catch
Micron closed Nov. 12 at $798.44, down 1.6% on the day but up nearly 22% from its Nov. 5 close.
At its Nov. 12 price, Stock Analysis put the shares at roughly 4.5 times forward earnings, versus 10.7 times trailing earnings. The discrepancy underscores how much bottom-line growth analysts expect. If those estimates falter, the stock might look more expensive without moving a dollar.
The upcoming earnings report gives investors a concrete test.
Micron guided to $61.5 billion in sales and an 86.25% adjusted gross margin at the midpoint for fiscal Q1. Management expects the margin to be at its low point in fiscal 2027. I’d pay more attention to whether Micron stands by that guidance than to whether it beats one quarter’s sales forecast.
Beyond that, it’s important to track whether Micron ramps its next-generation HBM4E on schedule and turns those higher contracted prices into cash as factory spending rises. Tan’s warning is evidence that supply remains tight.
Micron’s margins and cash flow will give investors a sense of whether that scarcity is still worth paying for.
Related: 5-star analyst revamps Nvidia stock target as CEO departs