A friend of mine runs a hardware shop, and I remember a time his shelves were running empty because a shipment of paint and some other items hadn’t arrived. The delivery was supposed to arrive that day I visited, but it didn’t show up until a few days later.
He definitely lost almost a week of sales and a few regular customers who went elsewhere. Since then, I know how much he values a supplier’s reliability.
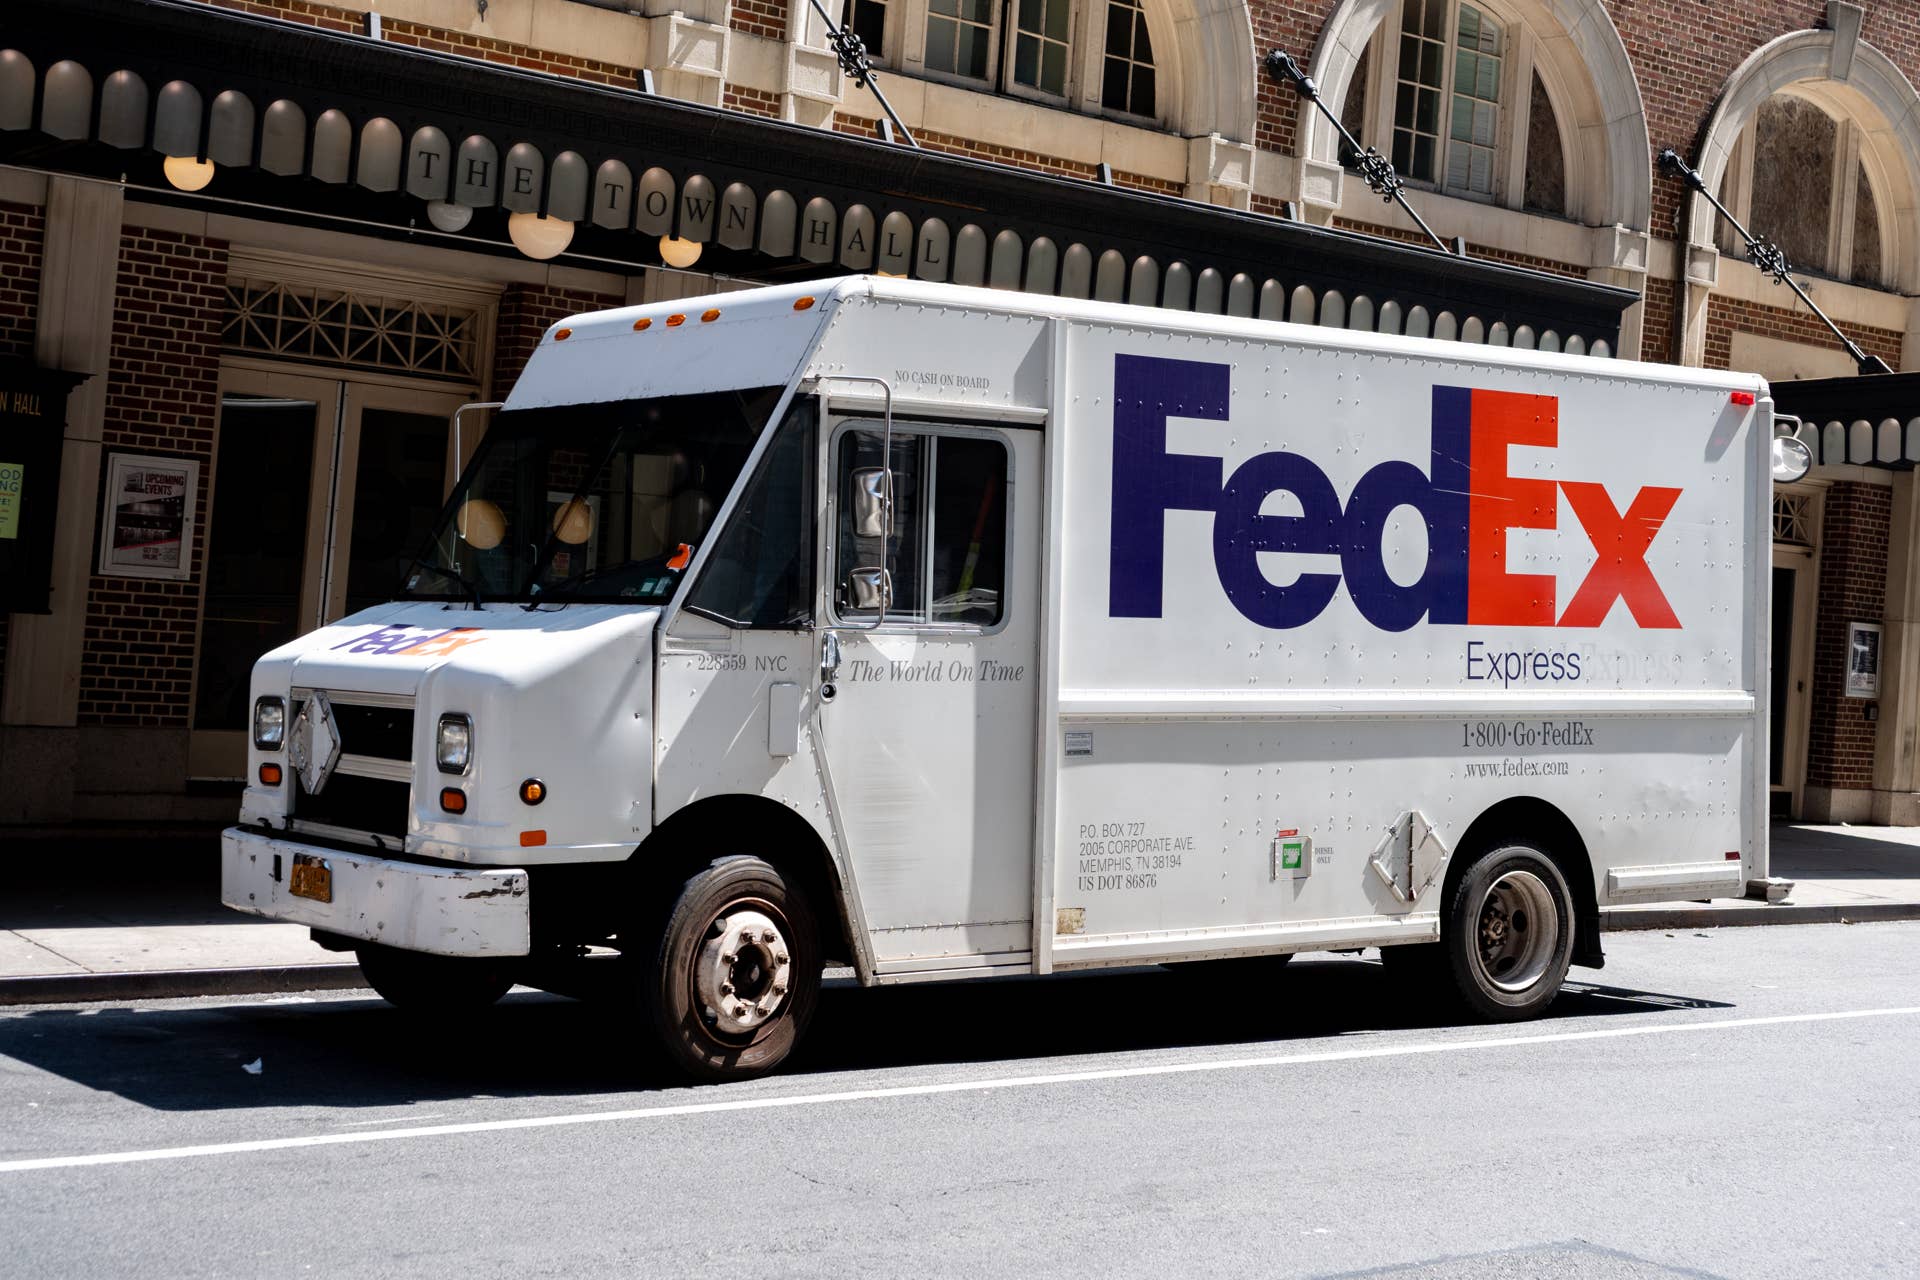
I remembered the empty-shelves debacle after coming across FedEx Freight (FDXF), the stock Jim Cramer endorsed on Nov. 3 on Mad Money Lightning Round.
You want to buy it. We like it for the Investing Club. It’s had a very nice move off the bottom.
FDXF currently trades near $130.26, up roughly 26% from an Oct. 28 low of $103.49, according to Yahoo Finance. Most of that came in a single Oct. 30 session after its first earnings report as an independent company, when shares jumped about 14%.
Also Read: FedEx CEO is seeing a shift in its customer base
The FedEx spinoff that started with a bang and then lost its footing
FedEx Freight began trading on June 1, 2026, after its parent FedEx spun off 80.1% of the business to shareholders. It is North America’s largest less-than-truckload carrier. That means it moves shipments that are too big for a parcel van but too small to fill a whole trailer.
FedEx Freight notes that it has about 40,000 team members and more than 365 locations. The debut was also loud. The stock peaked at $200 intraday on June 9, according to Yahoo Finance.
More Jim Cramer:
- Jim Cramer issues ‘falling knife’ warning on top chip stock after Intel’s outlook
- Jim Cramer raises a red flag to stock market investors
- Jim Cramer flags Netflix’s ‘biggest problem,’ and it isn’t price
Then it drifted, falling about 35% from the high to the current $130.26 as macro pressure and separation costs weighed on a company still learning to stand on its own.
I covered the early institutional interest in this name in August, when Bill Gates’ foundation trust disclosed a new $180 million FedEx Freight position in its 13F filing. I think that is a vote of confidence. October tested whether the business could back it up.
The FedEx Freight mixed results behind the 14% jump
The first report covered the four months ended Sep. 30, and in my opinion, it was mixed. Both sides of the ledger matter.
Revenue rose 9.2% to $3.3 billion, according to the company’s earnings release. But operating income fell 6.1% to $383 million, and diluted EPS dropped 43% to $1.54. Spinoff costs weigh on those figures.
On an adjusted basis, the picture is better. Adjusted operating income grew 16.4% to $510 million, and adjusted operating margin rose 90 basis points to 15.5%. Adjusted diluted EPS still fell 24.6% to $2.15, showing how much of the story depends on which line you read.
Related: What Jim Cramer is watching as Anthropic heads to Nasdaq
The operating detail explains the market’s relief. Average daily shipments slipped 1.4% to 88.9 thousand, and tonnage per day was flat at 41.7 thousand tons. Revenue per shipment rose 10.1% to $413. Excluding fuel, it rose only 1.6% to $318.23, so much of the pricing gain came from fuel rather than underlying rates. That is an honest caveat for anyone reading the headline.
Still, the company updated its transition-period outlook for fuel tailwinds and slightly higher volume assumptions. CFO Marshall Witt said underlying performance “was largely in line with our expectations” and that the company remains “confident in the base business as we approach 2027.” CEO John Smith said he was “encouraged by the momentum” across operations, commercial work and technology.
Why Cramer calls it a buy, and what the market is really pricing
Thinking about my friend’s shop, I’d say a carrier that delivers the day it promises to keep customers, and that reliability is what FedEx Freight sells.
Cramer’s reasoning is less about one quarter than about where the stock sits. A name that dropped about 35% after a hyped debut, then bounced off a clear low on earnings that were messy but not broken, is the setup he tends to favor. He says the Investing Club likes it, which means it is a position he likely owns and has already tested against his own risk limits.
Related: Jim Cramer raises a red flag to stock market investors
The business also has a cyclical backdrop that I have watched build across several recent stories. Fuel costs have been a theme in my airline coverage, from Delta’s $4.14 billion quarterly fuel bill to United‘s $8 billion year-over-year increase.
Freight carriers feel the same pressure, and fuel surcharges are part of what exactly lifted FedEx Freight’s revenue per shipment. That helps now. It also means investors should not treat the fuel-driven gains as lasting pricing power.
The honest risk is volume. Shipments are down slightly, and tonnage is flat, so the growth case depends on the commercial and technology initiatives management keeps citing turning into real freight, not just better margins on the same pallets.
What to watch going forward
FedEx Freight is only a few months into life as a separate company. The first full-year view will arrive as management leaves the transition period and gives a clean 2027 outlook. Investors should watch for shipment growth to turn positive, spinoff-related costs to ease and the gap between reported and adjusted earnings to narrow.
For the shop owner waiting on a delivery, I think it’s worth paying for a carrier that gets the truck there on time. For the investor, Cramer’s message is that a stock down more than a third from its peak, with a business that is working, is worth owning with the position sized sensibly.