AI investors have grown accustomed to seeing almost every dip treated as another buying opportunity.
Jim Cramer’s latest message, though, is uncomfortable.
While he believes the long-term AI story remains intact, owning too much of it can still wreck a portfolio when sentiment suddenly turns.
That became painfully visible after Nvidia (NVDA), Broadcom (AVGO), Alphabet (GOOGL), and other AI-linked names were hit hard by fresh questions surrounding OpenAI’s revenue. Consequently, the Nasdaq dipped 1.25% on Oct. 8, 2026, as semiconductor stocks came under particular pressure, as reported by Reuters.
Cramer does not think the AI boom is over. In fact, he told viewers he believes the sell-off can reverse and that “the AI trade will be back in action.”
But I think his larger warning is more important than that bullish nod.
Investors who have allowed AI winners to dominate their portfolios may discover that conviction and concentration are very different things when an unexpected headline suddenly challenges the market’s most crowded assumptions.
Cramer says the AI trade can recover, but concentration is the real danger
Cramer’s warning comes as questions emerge about OpenAI’s sales trajectory, sending much of the AI complex lower.
On “Mad Money,” he described Nvidia, Broadcom, and Alphabet getting caught up in what he called a “charnel house.”
More Tech:
- Anthropic-powered AI model sends shocking message to employee
- Rocket Lab clears 1st hurdle in its biggest satellite deal
- Apple’s $54 billion iPhone machine may be about to break its biggGest ritual
The underlying OpenAI story deserves a bit of nuance.
Reuters subsequently reported that OpenAI told investors its September annualized revenue was nearly $50 billion, below an earlier indication approaching $70 billion. But the discrepancy appears partly related to accounting comparisons.
For perspective, OpenAI excludes certain revenue generated through cloud partners when making some comparisons with Anthropic.
Cramer recognized that uncertainty. He said he had not received independent confirmation that OpenAI’s business was deteriorating and predicted that the accounting comparison would ultimately prove not to be “apples to apples.”
More importantly, he said, “I bet the big declines we saw today in the complex can reverse.”
That said, it’s clear that he isn’t fundamentally bearish on artificial intelligence.
The semiconductor index had surged more than 80% in 2026 before the Oct. 8 decline, according to Reuters. Meanwhile, Goldman Sachs estimates the largest U.S. hyperscalers could spend about $800 billion on capital expenditures this year and $1.1 trillion in 2027.
So the fundamentals behind AI spending therefore remain enormous. The vulnerability is that expectations have become equally enormous.
That is why a single revenue report from a private company could suddenly hit public companies across the AI ecosystem.
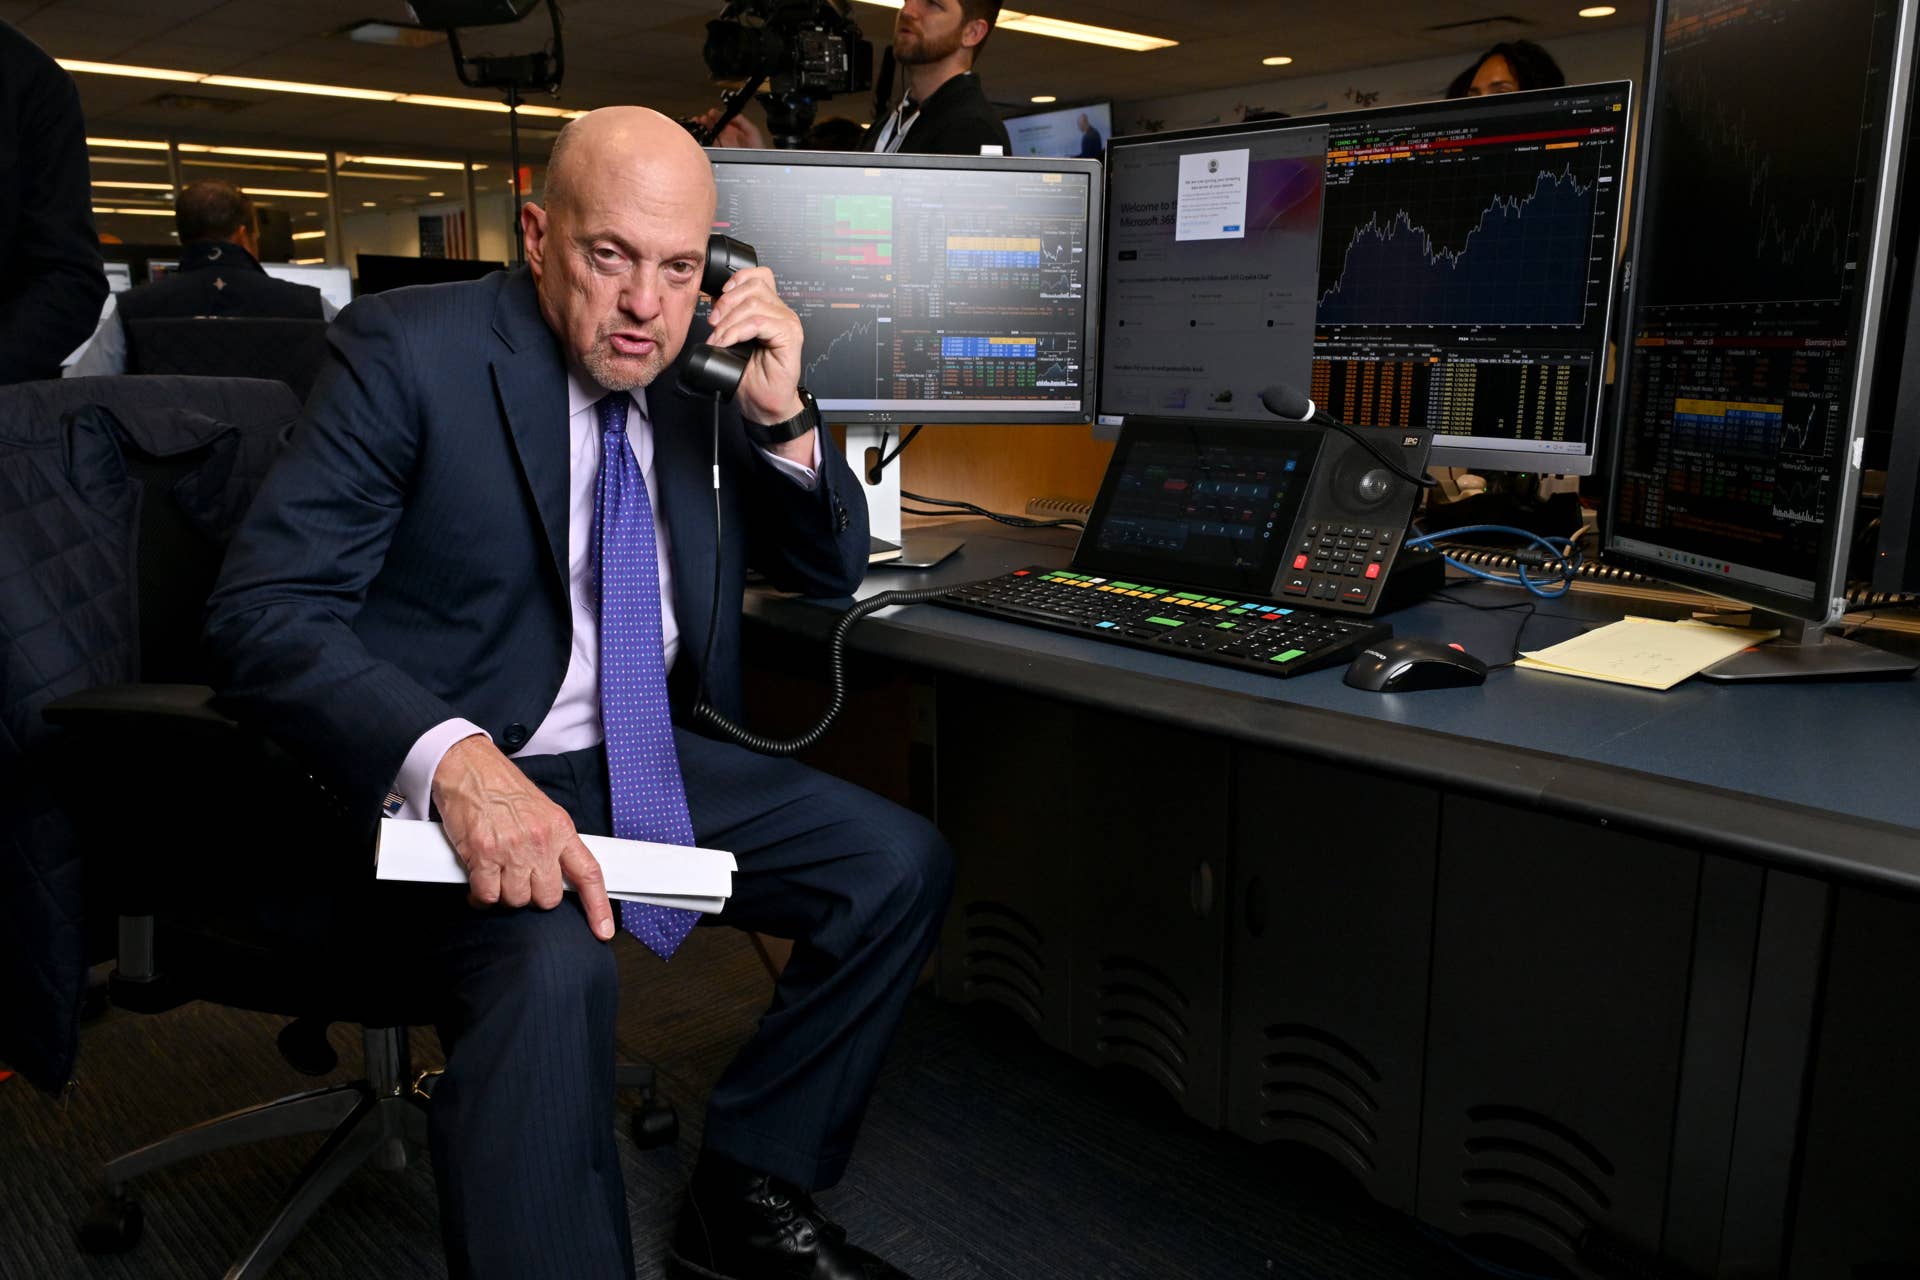
Cramer’s bigger message is about staying invested when the hottest trade breaks
The part of Cramer’s argument I find most useful for ordinary investors came after the sell-off.
He imagined an investor owning nothing but data-center stocks, watching those positions fall simultaneously, and eventually saying, “I can’t take this pain. I can’t take these losses.”
His concern is that concentrated investors may respond by selling everything and moving to cash at precisely the wrong moment.
Cramer pointed to investors who fled markets following earlier crashes and never fully returned, missing subsequent rallies.
“Diversification is the only free lunch in the business.”
His own example was Home Depot (HD) stock.
Cramer acknowledged that he had disliked owning the stock while housing and interest-rate pressures weighed on it. Yet when AI shares tumbled, Home Depot (HD) rose more than 3%, demonstrating why exposure to economically different businesses can soften a portfolio shock.
I would take that argument one step further. AI investors increasingly face correlation risk. Nvidia, Broadcom, Oracle, and other AI-infrastructure names participate in different parts of the ecosystem, but they can still trade as one basket when investors suddenly question AI profitability.
That risk is becoming more important as financing requirements grow.
Morgan Stanley estimates that AI infrastructure could require around $1.5 trillion of external financing by 2028, with investors demanding evidence that revenues can eventually support the enormous buildout.
Cramer’s answer was not to abandon those winners. He said “cash and stocks not impacted by the data center” can help investors endure periods when AI suddenly falls out of favor.
That is a very different message from trying to predict the next daily move.
Don’t confuse belief in AI with needing an AI-only portfolio
Cramer’s warning becomes much more useful primarily because he remains bullish on AI in the long term.
Instead, he expects AI stocks to recover while arguing investors should prepare for violent resets along the way.
There is evidence that valuations have already adjusted. The median AI-infrastructure stock recently traded around 22 times forward earnings, down from about 32 times in April, according to Goldman Sachs data cited by Wealth Professional.
The broader S&P 500 traded around 19.2 times forward earnings.
I therefore would not read the Oct. 8 tumble as proof that the AI thesis has broken down. I would watch whether hyperscaler spending, cloud demand, and semiconductor earnings actually begin weakening.
For investors already heavily exposed to Nvidia, Broadcom, or other AI winners, however, Cramer’s message is actionable now.
It’s imperative to check how much of the portfolio depends on the same AI spending cycle.
AI can remain one of the market’s strongest long-term themes, yet still be too large a percentage of an individual investor’s portfolio. Those two ideas are not contradictory.
Related: Jeff Bezos explains why Amazon is still cutting jobs