Artificial intelligence has a funding problem that dwarfs most corporate budgets. Bank of America forecasts that AI capital spending could top $5 trillion between 2026 and 2030, with roughly $1.2 trillion of it needing outside financing.
Most of the gap sits with Oracle (ORCL), SpaceX (SPCX), CoreWeave (CRWV) and Nebius (NBIS), where spending runs about $700 billion more in projected capital spending than operating cash flow.
Nvidia’s answer arrived on August 10, when it signed deals with six major asset managers to mobilize more than $500 billion in third-party capital for AI infrastructure, according to a Nvidia statement. The pitch is bold. Nvidia shares closed down 2.86% that day, while Apollo and KKR both rose more than 6%.
Also read: Nvidia, SK Hynix send strong signal to Micron investors
Lenders want more protection than Nvidia offered
Some lenders want higher guarantees than Nvidia first outlined, even for its industry-leading AI chips. Banking sources and credit managers said the August plan, announced with Apollo, BlackRock, Blackstone, Brookfield, Goldman Sachs and KKR, had envisioned chips as collateral with only a limited guarantee.
The structure works like a lease. A financing platform buys the chips, leases them to the customer and collects payments tied to the compute revenue. Nvidia backstops part of the residual value in some arrangements, which also lets the lender charge a lower rate.
The customer gets the hardware, the lender gets a long-dated return, and Nvidia books a sale, as long as the revenue holds.
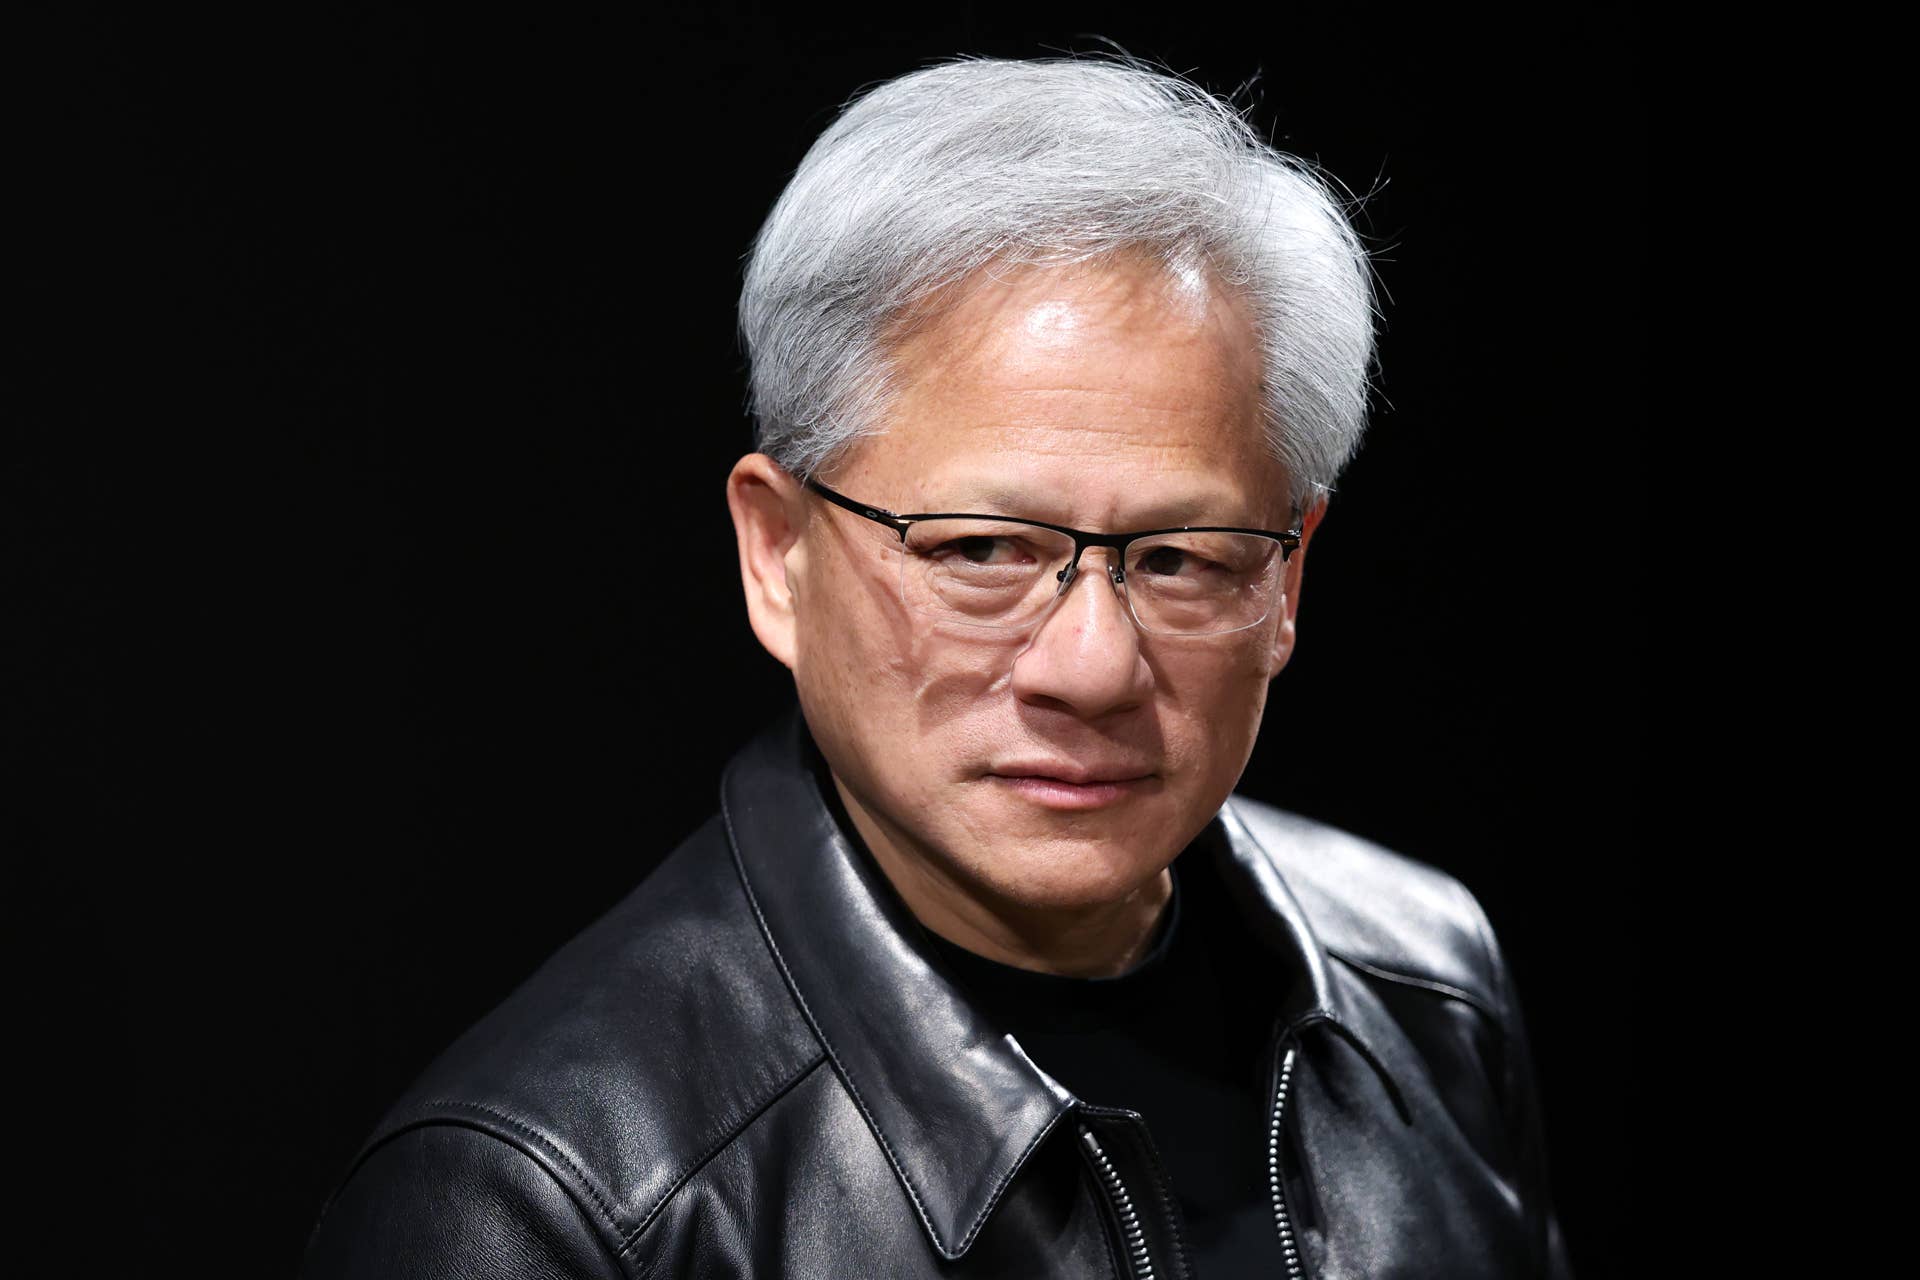
Chief Executive Jensen Huang has said Nvidia may provide support of up to 25% of an opportunity. He also said he approached only six firms and none turned him down. The money will all be third-party capital, Huang said.
Huang’s case is simple. Chips have become an investable asset class for the first time, he said. Blackstone’s Jon Gray compared the idea to mortgage lenders evaluating homes. Gray said usage at Blackstone portfolio companies surged sevenfold this year, evidence that demand is outrunning supply, CNBC reported.
The fight over how long a chip keeps earning
Huang has said graphics processing units can last up to a decade. Some credit investors see a shorter life. Andrew Chang of S&P Global Ratings said service beyond five years has held true so far, yet S&P takes a conservative view of the chips’ value.
Big cloud companies already disagree with the skeptics. Google, Microsoft and Oracle estimate their AI chips last about six years. Investor Michael Burry says two to three years is closer to the truth.
Meta said extending the estimated useful lives of certain servers to 5.5 years would reduce its 2025 depreciation expense by about $2.9 billion.
GPU valuations offer one clue. Six-year-old Nvidia A100 chips are still estimated to be worth nearly $5,000 each. CoreWeave has a customer contract for A100s running through 2029, Benzinga reported. Older chips can shift from cutting-edge training to inference and lower-cost work, extending their economic life.
Burry argues the longer lives flatten earnings. He estimates that major companies overstate profits by about $176 billion from 2026 through 2028. Nvidia has told investors that hyperscalers depreciate GPUs over four to six years, not the full decade that Huang describes.
Chip-backed loans still lean on contracts
CoreWeave put that theory to work in March. The company closed an $8.5 billion loan backed by its GPUs and a Meta contract worth at least $19 billion. Moody’s gave it an A3. Fixed-rate debt priced around 5.9%. Mitsubishi UFJ and Morgan Stanley led the deal, which matures in 2032.
CoreWeave won its rating largely because lenders rely on Meta’s contractual payments, which are viewed as highly dependable. Unlike Nvidia’s plan, earlier chip-backed deals leaned on revenue from a technology firm to support the debt payments.
More Nvidia:
- Nvidia just made a move Wall Street wasn’t ready for
- Nvidia just locked down deal that changes AI race
- Nvidia stock is doing something it hasn’t done in years
The Broadcom deal makes the math concrete. Apollo led a $35 billion package backed by Broadcom’s AI chips. With Broadcom’s guarantee behind it the debt priced at 5.75%. Without the guarantee it priced at 8.5%, Investing.com reported. That is 275 basis points. That is what a guarantee is worth.
The danger is that collateral values could slide. Analysts have warned that rapid depreciation could worsen if China floods the market with cheap compute. That would erode the value of chips behind these loans, and Huang’s bet hinges on outpacing AI developments in China.
Nvidia tries to calm the doubts
Nvidia is working to ease the concerns. One source said tens of billions of dollars in loan deals in the pipeline are likely to carry strong guarantees and contracts. A spokesperson did not directly address questions about expanded guarantees.
Guarantees move risk rather than remove it. If a supplier backs a package, it could face losses if projects fall short. Customers could struggle, or AI hardware could lose value faster than expected.
More funding may keep chip demand soaring, but it may also shift some of the AI boom’s financial risk back to the firms selling the technology.
The verdict is still open. Whether Nvidia’s chips behave like durable, bankable assets or simply extend the runway for a leveraged buildout may not be settled for years. Nvidia itself raised $25 billion in a June bond sale after investors offered $85 billion.
Until the chips prove their staying power, lenders will keep asking Nvidia to stand behind its claims. That negotiation will shape how the AI boom gets paid for.
Related: Nvidia is set to challenge Anthropic and OpenAI with a new product