I’ve always found airline ticket prices to be puzzling. You can travel thousands of miles on an international flight, only to discover that a much shorter domestic connection costs nearly as much, sometimes even more.
It makes you wonder how airlines decide what passengers should pay and how much choice we really have as travelers.
What once seemed like an occasional frustration has become a much bigger issue for airlines in 2026. And I have a number that helps explain why.
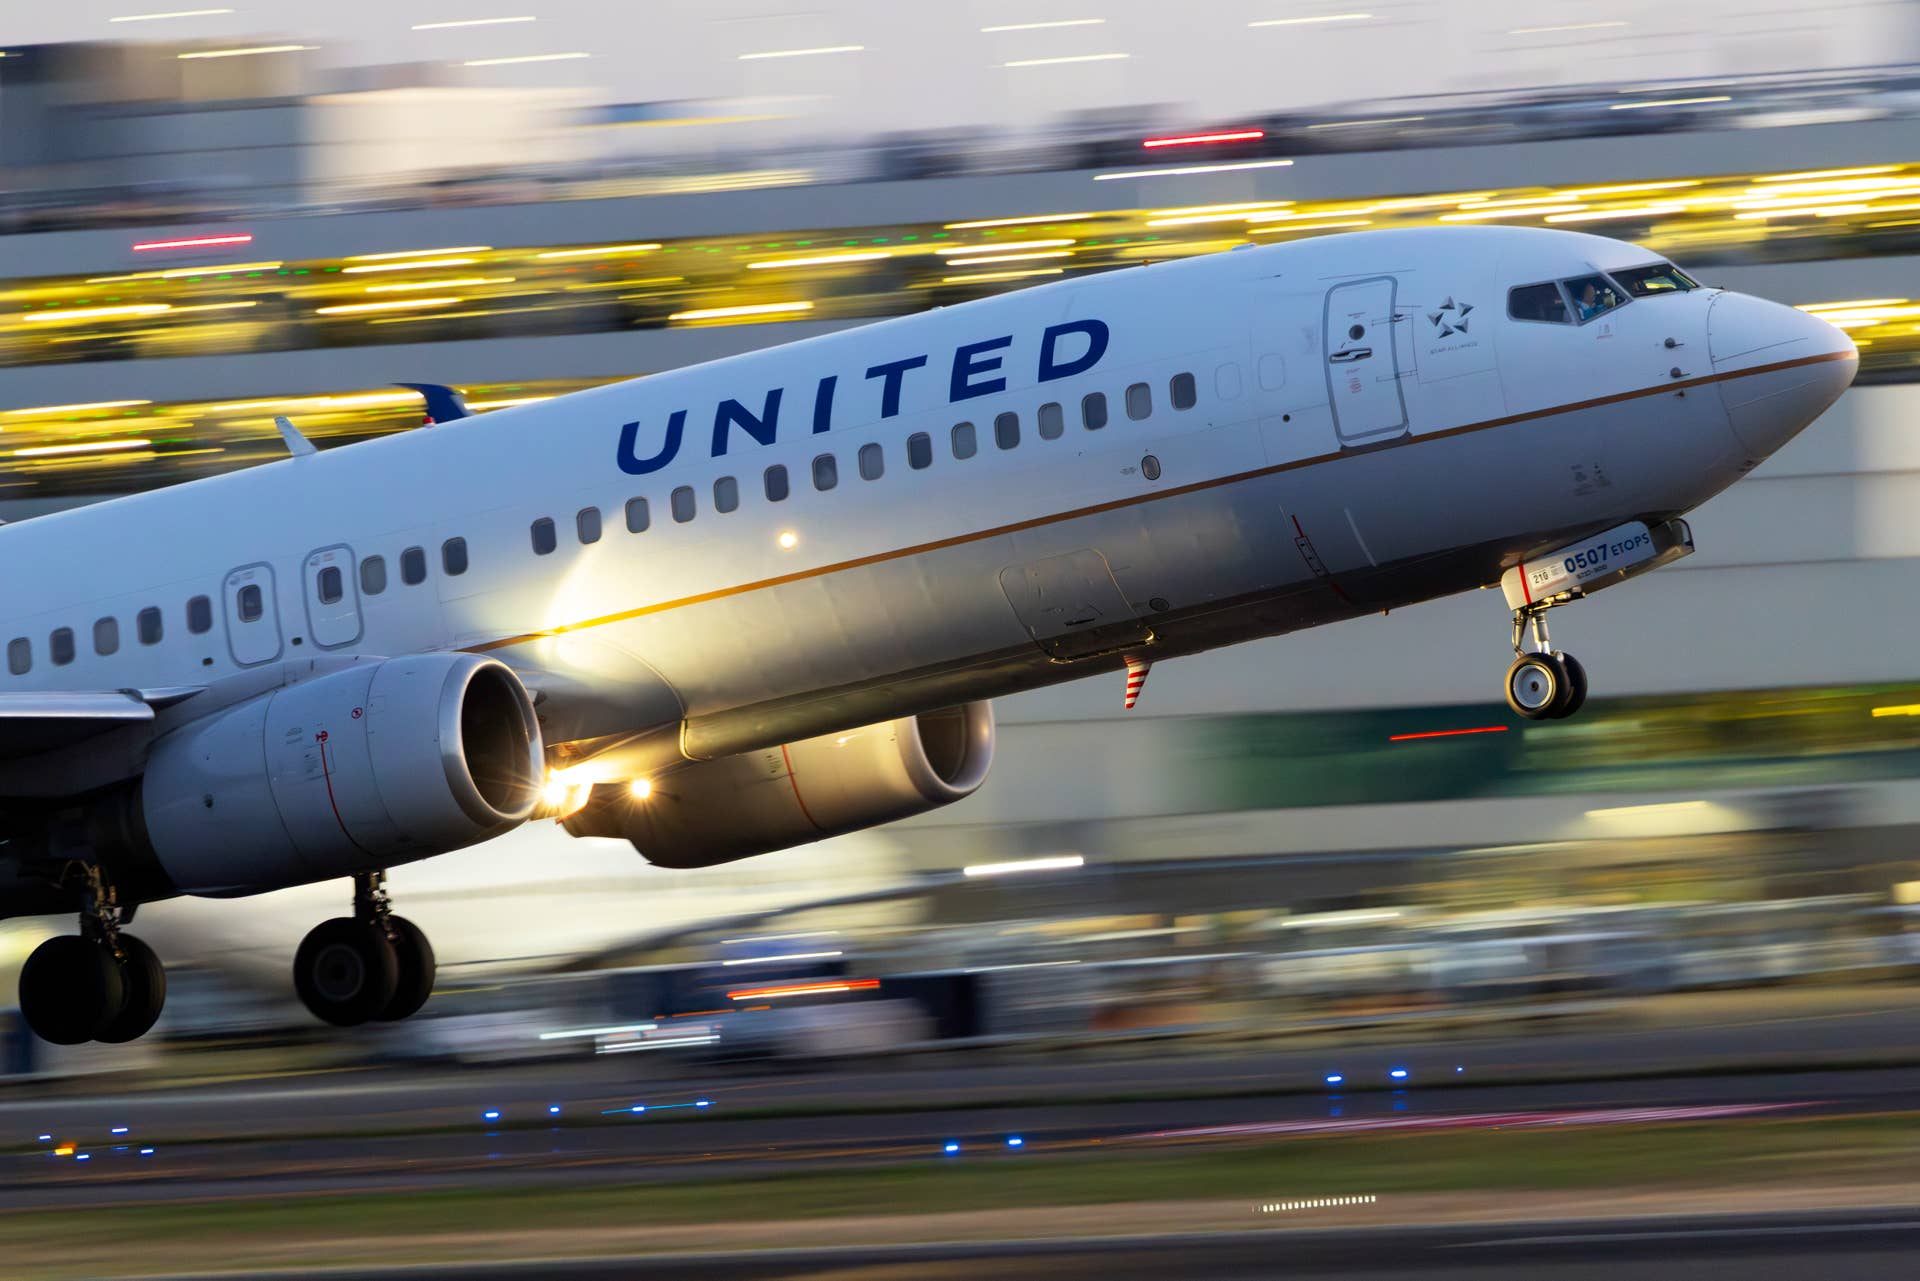
Jet fuel averaged $3.90 per gallon for United Airlines (UAL) in Q3 2026, up a whopping 60.3% from $2.43 a year earlier, according to the company’s Q3 earnings release.
United’s total fuel bill for the quarter was $4.84 billion, $1.8 billion more than Q3 2025. The airline passed roughly 72% of that increase on to travelers through higher fares, according to CEO Scott Kirby’s CNBC interview on Oct. 21. Passengers actually absorbed it, and United carried a quarterly record of 49.5 million customers.
Also Read: United Airlines filed for bankruptcy 24 years ago — here’s why
Why United Airlines is still profitable while most rivals are not
Kirby opened with a number that reframes the entire story.
“Fuel is up $8 billion year over year,” he told CNBC from Houston, where United is opening its biggest-ever lounge.
That $8 billion figure applies across the full airline, not just one quarter, and represents a structural cost shift that would have destroyed United’s profitability under its pre-pandemic cost structure.
It has not. Q3 total operating revenue hit $17.9 billion, up 17% year over year and a record for any quarter in the company’s history, according to the earnings release. Revenue per available seat mile grew 16%.
In fact, it’s the best quarterly unit revenue growth since the pandemic. Adjusted diluted EPS was $2.54, in line with guidance despite the fuel spike.
We’re still solidly profitable even in this environment.
“It’s a testament to the structural changes in the industry and to decommoditizing air travel here at United,” Kirby continued.
Decommoditizing air travel is the strategic logic behind everything United has done over the past four years. When passengers choose airlines based on price alone, carriers are forced to compete on fares, putting pressure on profit margins across the industry.
But when loyalty, Wi-Fi, seat quality, and reliability influence those decisions, airlines like United gain pricing power. That helps explain how United can pass through 72% of higher fuel costs while still filling 83.9% of its seats.
The casualties United Airlines CEO sees coming and what that means for passengers
I come back to my earlier observation about domestic airfares when I read Kirby’s bluntest comment: “Six to ten U.S. airlines are going to lose money this year.”
Spirit’s bankruptcy earlier this year, which Kirby acknowledged “gave a stay of execution to a number of other airlines,” was the first visible casualty.
Kirby has an idea of what comes next: carriers that are losing money will eventually stop flying routes where they lose money.
That sounds like an operational efficiency story. For passengers in smaller markets served primarily by budget carriers, it means fewer flights and less price competition.
“Running an airline and being successful is simple. Don’t fly to places that lose money. It’s emotionally hard, but it’s logically easy,” Kirby noted.
The math driving those decisions is $3.90-per-gallon jet fuel with no near-term relief in sight. Kirby said he expects oil to stay elevated into 2027.
The Starlink tailwind that separates United from the rest
The most forward-looking element of Kirby’s interview was the competitive differentiation he sees arriving from Starlink.
United had Starlink installed on more than 640 aircraft as of Q3, and available on approximately half of all flights, including regional service, according to the earnings release. The rollout is expected to reach 61% of the fleet by year-end 2026, 87% by June 1, 2027, and fleet-wide by year-end 2027.
“We already see customers moving from other airlines,” Kirby said. “It’s a unique tailwind.”
I recently covered Delta CEO Ed Bastian’s decision to reject Starlink in favor of Amazon’s Project Kuiper, and the social media exchange with Elon Musk that followed. To me, United CEO Scott Kirby’s latest numbers offer one of the clearest answers to that debate.
More Airlines:
- Another low-cost airline files for bankruptcy protection
- JetBlue, Southwest Airlines, and Allegiant make pricing move
- Southwest Airlines kills routes to multiple markets
According to my previous United coverage, customer satisfaction scores for Wi-Fi on Starlink-equipped aircraft are more than double those on its other planes. For a business traveler taking video calls at 35,000 feet or a family streaming movies on a long-haul flight, that’s a difference passengers can actually feel.
Q4 guidance calls for total operating revenue growth to accelerate beyond Q3 and set another record of over 20% year-over-year growth. The Q4 EPS range of $0.50 to $1.50 trails Street consensus of $1.75, with fuel costs the dominant variable.
If you’re a traveler, fares are still going up, and some routes may disappear.
As an investor, I think the carriers that can pass costs through and keep planes full are the ones worth watching. Kirby’s Q3 data shows United is one of them.