Transcript:
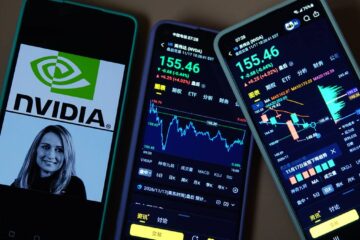
Caroline Woods: Joining me now, Carter Worth, CEO and founder of Worth Charting. Carter. Great to have you back at the desk. Great to be back. All right. I think Nvidia (NVDA) is a good place to start today. Taking a look at the reaction post earnings. Good earnings. Bad reaction. What does the price action tell you.
Carter Worth: Right. So it’s an important thing. There’s no such thing as good or bad results so to speak right. There’s only how the stock acts. So if a stock raises its earnings estimate increases the buyback says the margins are better but it goes down. Then obviously that wasn’t good enough right. And so in that’s the case always at this point the question is from here having dropped from well we’re down almost 40%.
Carter Worth: Yes. Some 242 42 to 1 150 does one. If one’s long and it’s just endured this nightmare of a thing, sell now or hold and wait for some sort of bounce and sell into a bounce at maybe a little bit of a reprieve price. Or if one’s not involved at all. Nibble. My hunch is to nibble. If you’re not involved, take a stake.
Caroline Woods: So as you look at the chart and kind of see this straight line down since early October, you would say that’s maybe the signs of a no.
Carter Worth: I mean, this is an extreme reading in terms of news. You speak to it. It’s not the magnitude, you know. It’s not that you can drop 40, can drop 45 can drop 50. It’s the it’s the sheer steepness of the line. Right. And it’s the, the clearing mechanism. At some point you have price discovery, the amount of shares that have changed hands.
Carter Worth: At this point, I would say that all that is bad has been discounted. Remember valuation that that is a terrible timing tool, right? How could Nvidia (NVDA) lose 35%? Caterpillar (CAT)’s done 50. Was it expensive before it dropped? Is it expensive now if you revise earnings down I mean a song can go down and down. Look at Nike (NKE).
Carter Worth: It’s going down for ten years. I mean, valuation is a terrible timing tool. But what we do know is that there are moments in the business of sequencing, and that’s what charting is. It’s studying sequences where something has gone too far in one direction or the other, and it’s right to play for mean reversion in this case, with this very important stock, if you can buy, you could sell or do nothing.
Carter Worth: I would say buy.
Caroline Woods: And is there any indication of what the rebound on the other side could look like for Nvidia (NVDA)?
Carter Worth: Well it’s it’s one of the hardest things to know how to cope with a winner. I think about a losers. You have something at ten and it goes to a you got to cut it before it goes to four right. But what do you do when you buy something at $10 it goes to 12. Got a 20% gain.
Carter Worth: Take it with anybody goes 18. Oh my gosh what a disaster. We were there. So the hardest thing to do let’s say this is judgment is right. Mine to buy for a bounce. And it bounces from 150. Let’s call it to 160. If you book that that’s a nice trade. Maybe it takes place over four days or four weeks and it ends up going back to 190.
Carter Worth: That’s a horrible thing. You’ve missed out in turn, it’s and this is the perversion of markets, which makes it so tricky. You buy it at 150 and it does bounce to 160. And you say, you know what, this is the time. It’s going to keep going to 190. So you stay and then it gives it back. It goes to 150.
Carter Worth: There is no answer to that. So the answer to your question is I would buy it here. And then after that if and as there are gains I would trim into that. So at 170 maybe take a third off 175. At 180 you start getting to 17518. I would call that a decent trade. Come out altogether. Now where to cut the loss?
Carter Worth: What about that bite at 150? I would tolerate 2 to $3. If it’s wrong, it’s wrong. And there’s nothing wrong with being wrong. But there’s something wrong. Be staying wrong if you buy something. 15149152151491. 47 walk away.
Caroline Woods: Is there a price, though, that tells you Nvidia (NVDA) has turned a corner?
Carter Worth: Well, remember the turning the corner in the in the words you’ve used. It’s a time. It’s time and price to turn a corner. If something is sick, you don’t get out of bed. Person doesn’t jump and run the Boston Marathon, Yukon last year. It’s a basing and bottoming and curing process. That’s not what this would be. That would take months and months.
Carter Worth: This is just a ricochet presumption that you can get some sort of bounce after this very steep, 40% selloff.
Caroline Woods: Nvidia (NVDA), though, was the stock to invest in. It wasn’t necessarily a trade. There were the, you know, own it, don’t trade it kind of calls. Has that changed since? Well, Jensen.
Carter Worth: Has an interesting 98% of all stocks on form T-bills over time. I just you know, it’s not a it’s not a long term, long term invest. The reason why indexes were because there’s their survivor bias. You shed the losers. You keep putting new winners in. But there are plenty of people have bought held they held Westinghouse and they held Western Union.
Carter Worth: And they held Cisco (CSCO) which is you know, down 70.
Caroline Woods: Is Nvidia (NVDA) the next one that we’ll be talking
Carter Worth: About, there’s no such thing as a growth stock that’s very important. There’s only stocks in growth phases. And so all stocks there was no greater company than IBM (IBM) when they when the Watsons controlled the most valuable the most valuable in the world Cisco was U.S. Steel was General Motors (GM) was Microsoft (MSFT) was Apple (AAPL) was Nvidia (NVDA), and now Nvidia also.
Carter Worth: It’s right to be on the right side of trend and one has to be disciplined. Take losses when a certain amount of damage has been done. There’s nothing wrong with being wrong, but you can’t stay wrong.
Caroline Woods: All right. You mentioned Apple and Microsoft both much closer to the highs than Nvidia (NVDA) is at this point. Last time you were on back in August, you said that Amazon (AMZN) had the healthiest chart of the Mag Seven, Microsoft had the weakest. Are you revising those calls now based on the action seen over the past few months?
Carter Worth: No, I would say the Microsoft has had the most, well, most volatility. Yes. Of those two. And Amazon I think is the better chart pattern here.
Caroline Woods: Of the Mag Seven. If you could only buy one, which one would it be?
Carter Worth: That’s a good question. Apple seems too complacent. So I would eliminate that Tesla (TSLA), too vague if you will or.
Caroline Woods: Too meaning.
Carter Worth: Well so Apple’s relative has having not drawn down at all during the semiconductor sell off. Now during this recent selloff in the S&P. It’s it’s really the face of fear. I would care that people are hiding in that the same way they’re hiding in staples. Maybe look at what’s.
Caroline Woods: Going on safety trades.
Carter Worth: It’s a safety trade right. And that at some point becomes crowded. Let’s say a Costco (COST) trading at 50 times, you know the valuation. But Costco’s up 3,040% in a matter of weeks. We have a certain coterie of stocks super cap names Walmart (WMT) seen that Johnson & Johnson (JNJ) that don’t just not much growth that people are hiding in. And that’s what a playbook says.
Carter Worth: Remember the the individual investor can always just say, I’m selling. I want to be in cash. The institutional investor is at a much harder job because they can’t just go to cash. You must be fully invested all the time. So as the damage is done in a semi or a caterpillar down 50%, or Nvidia (NVDA), that’s the classic rotation.
Carter Worth: But that’s the problem with the market, the ones that have received the money, let’s call them dry sponges. Procter & Gamble (PG) is up 30%. But if that sponge is saturated now they’ve all held the sponge in the sink. When the tap is running it can take no more water. These very defensive names like Berkshire Hathaway (BRK.B), like Costco, like Procter & Gamble, have been the recipient of the rotation out of high fliers.
Carter Worth: But the market structure is worse because those stocks now having bounced, there’s nowhere else to go.
Caroline Woods: Okay. I want to get into that defensive rotation in just a second. But let’s go back to Mag Seven and kind of wrap that up. So wouldn’t be Apple because it wouldn’t be Tesla to.
Carter Worth: Microsoft I would say I would say Amazon.
Caroline Woods: Amazon you would be Google (GOOGL).
Carter Worth: Now what else is in.
Caroline Woods: Nvidia, Meta, Meta.
Carter Worth: Yes. Small nibble okay.
Caroline Woods: As we’ve seen this you know defensive rotation that you’ve been talking about energy material staples, health care the best performing sectors year to date at this point all outperforming tech at this point. You think that those trades have been too crowded. Which one.
Carter Worth: Is not crowded. So let’s say again I mean energy is not to say institute part of the economy and the employment spectrum of United States, but we know that the sector is only 3.2% weight in the S&P, even though the sector’s earnings are 5.5% of the S&P and the revenues are seven. Now, that’s the nature of a discounted, value oriented kind of thing.
Carter Worth: I think energy is an overweight, is it exciting? No, but it’s not it’s not overbid, if you will. The way again, a lot of these staples and health care names.
Caroline Woods: Are which names within energy do you like.
Carter Worth: Well the sector of course three stocks are half the weight is you know I would just stick with the big I don’t like the drillers. So Schlumberger (SLB) Halliburton (HAL) Baker Hughes (BKR). No but Exxon Mobil (XOM) Chevron (CVX) just fine okay.
Caroline Woods: So you like energy healthcare. It sounds like staples. You would have underweighted.
Carter Worth: Underweight, yeah.
Caroline Woods: Staples because you don’t think that this is a market that you should play it safe in or because that’s what do you think that they’re okay.
Carter Worth: The sponges are saturated.
Caroline Woods: So you’d take profits here.
Carter Worth: I would in steep uncorrected ricochets in staples.
Caroline Woods: What about in healthcare.
Carter Worth: Well that’s more idiosyncratic right. So there’s there’s no big thing. One could just say, well, I just want to be long, Eli Lilly (LLY) and stick with it. There are great stocks. Think of health care was the biggest weight for years and the most stable, and then the business model maybe change and so forth. But Eli Lilly’s fine. Pfizer (PFE). I do do a.
Caroline Woods: Eli Lilly fine to buy here.
Carter Worth: To buy here. Hold here. Yeah. Just respectable J&J a little too complacent. And some of the device companies have gone a bit too far Edwards Lifesciences (EW) for instance. But in general, as a theme, I would rather be if you were to cook, remember the ultimate defense. That’s what this health care is, was never originally even. So, you go back 150 years.
Carter Worth: That’s called bite on a stick. We’re going to cut your leg off. In the Civil War, there were no pills. There was no medicine. That’s not defensive, okay? It didn’t exist. True. What they called soap and cereal. Right. So we have biscuit companies in this country that are 175 years, 200 years old. Kellogg’s, like Post Holdings (POST). And so soap and cereal, like Procter & Gamble selling literally soap and cereal.
Carter Worth: And that is the ultimate defense. That’s why their health care is more it is biotech does one thing. Devices do another. Managed care does something else. Pharma does something else versus and so forth. So that’s more of a stock picking thing. But as a theme, if one wants to now call it defensive or while it’s not as defensive as staples, I would be overweight versus staples, which are way over sort of over here.
Caroline Woods: And in terms of the Mag Seven, you had said basically two of the seven you would nibble on here last time you were on, you were saying underweight tech altogether. Does that hold true or have you seen that?
Carter Worth: We’ve seen pretty big damage since we talked. It’s been a disaster, frankly. Right. Semiconductors, software and so forth. I guess I wouldn’t be underweight tech at this point. I would move that up to equal weight. But that’s not saying much. Right? Right. I mean, I think at the.
Caroline Woods: Which would you buy here aside from
Carter Worth: There are some individuals sort of let’s say software not so. Yeah. Software names there that are trying to bottom like a ServiceNow (NOW), for instance. Oh not bad. But that’s a very much it’s important as a theme is tech the great underweight that it was in August. No it’s really been hurt. Call it an equal weight, but that’s a more of an institutional thing and individual.
Carter Worth: What do you want to do with that car? Equal weight. What does that mean? And so you got to pick the stocks. And there are some favorites. Snowflake (SNOW) is one I nibble on.
Caroline Woods: Anything outside of software though. What about memory chips.
Carter Worth: So now if you’re going to do that sort of bombed out game, I would just say Nvidia (NVDA) is as good as any or do it as an aggregation and say, all right, well I’ll just do the the iShares Semiconductor ETF (SOXX) and play for a bounce. But those are trades. That’s important. When something has collapsed it doesn’t repair itself quickly.
Carter Worth: And so the bottoming out or turning a corner that’s months of healing developmental action. That’s not what a trade in a in oversold circumstances.
Caroline Woods: Speaking of trades I saw that you actually brought us a trade. You’re exchanging a winner or a loser for a winner. Coca-Cola (KO) and Caterpillar Coca-Cola very close to the highs. Only about 3% from the highs. Caterpillar about 50% from the highs. Why why swap.
Carter Worth: You know why swap. And so sometimes again in the in the business of sequencing it’s not about whether coke is a good drink or a bad drink or caterpillar digs good holes or they’ll dig holes. Really centers. Or maybe people inside the caterpillar tractor drink Coke while they’re digging holes. It’s just about at some point you get overdone.
Carter Worth: And so from June 30th, the mid year point perchance caterpillar is down about 50% and Coke is up about 23. Okay. And so you could say they have nothing to do with what meaning in the business of pair trading quite often you want something that’s Coke and PepsiCo (PEP). Hertz (HTZ) and Avis Budget Group (CAR) McDonald’s (MCD) and Burke, John Deere (DE) and Caterpillar. But these two American classics, if you were to just look at a relative or ratio chart one divided by the other, there is a relationship going back since the 1980s where there are moments where the more cyclical business is doing better.
Carter Worth: Caterpillar, and they’re moments where the more defensive business is doing better. At this point, that ratio chart is at an extreme reading never seen in the past 50 years. And so this is symptomatic of what’s going on in the market, people hiding if you will, or money moving to non growth. Coca-Cola has no growth right. Its top line is 2 or 3% kind of thing.
Carter Worth: And so the sponge I would say is full whereas caterpillar is deeply oversold. And again it is nothing to do whether but when the AI thing stops and they don’t do any more data center holes then caterpillar can earnings can get cut. I think to do with that. It’s just about there are extreme moments where by my work it’s right to say, hey, we step up or make a trade.
Carter Worth: This is a pair that we like.
Caroline Woods: But you’re also calling this one a trade. So how long do you expect this trade to work? What would tell you it’s time to get out.
Carter Worth: If they’re only 13 instances where this circumstance where the spread between the two stocks, one being up 22, they’ll be down 50. So 70% like that. If you look at all instances where it’s been 40% or wider, this is the widest by far the only 13 others going back. And each and every time, essentially, it was right to play coke on the short side, cat on the long side for a trade for about 1,000 basis points.
Carter Worth: So we’re looking for about a 10%, net return by being paired, fading, selling the one that is loved here and in buying the one that is now hated.
Caroline Woods: What’s the takeaway, though, for the retail investor who maybe is more buy and hold but interested in looking at the charts, what should they be doing here?
Carter Worth: Well, so there’s it’s the only thing that matters for an investor is you have to know who you are in the market. That’s it. If you’re buying hold, then just don’t ever change that. Right. That’s but that.
Caroline Woods: Would you buy caterpillar here then if you were buy and hold.
Carter Worth: Yes. So.
Caroline Woods: So you sell coke here.
Carter Worth: Yes. Both of those if you’re buying hold I would. So let’s say one’s head coke. No one could say yes. But I got it from my grandmother that cost basis a dollar. I don’t want to pay taxes. Okay. But that is nothing to do with. We’re talking about the charts. That’s not do it fundamentals. That has nothing to do with the complacency or money flow.
Carter Worth: That’s an idiosyncratic personal thing that has nothing to do with portfolio manager. Is Coke here and now? If one used fundamentals, is it overvalued? It’s rich okay it’s full. But as a chart it’s complacent. Whereas caterpillar has literally been thrown out. So we liked that.
Caroline Woods: Pair it I was taking a look at your notes. You screened 100 lowest volatility stocks in the Russell 1000. And of those nine look like buys.
Carter Worth: Yes.
Caroline Woods: Can you that right.
Carter Worth: I would. Can you remind me what they are. Have so many.
Caroline Woods: I was going to say I don’t have the nine but I guess what is it that would separate the nine from.
Carter Worth: A good chart? Meaning? So a chart that is generally the 13th. We don’t want. Of all the factors that have ever been tested, the biggest relative strength and momentum matter the most. And it’s not because it’s the market. It’s the nature of like a political pain. It’s starting to get better and better and better sports season well is very important.
Carter Worth: So a good chart just it’s plain in a sense is something that is generally and uptrend that is outperforming some other thing of which it is a part an index and any of those nine and.
Caroline Woods: Which we don’t have.
Carter Worth: Which neither of us have. And that’s.
Caroline Woods: Not very helpful. You were going to.
Carter Worth: Have in your pocket my list. But there it is. I got a lot of less than that. But the point is that those charts and I’d have to look at that, are going to be stocks that are exhibiting those characters relative strength, bullish price volume correlation that are neither in steep downtrend nor the other circumstance where they’re just so up on a rope where they’ve become.
Caroline Woods: So that kind of aside, which names aside from the ones that we’ve mentioned, actually look like good opportunities here because of the charts.
Carter Worth: Well, let’s take one that like caterpillar, which is not John Deere. We like that a lot. That’s a that’s an excellent setup if you will, just now sort of moving above well-defined tops over the past 12 to 18 months and not extended and exhibiting the characteristics that are desirable. There are like, let’s take banks. We haven’t talked about financials.
Carter Worth: I wouldn’t we completely underwrite from the big banks like.
Caroline Woods: Underweight.
Carter Worth: Underweight, yeah, or it’s just about the same thing. It’s how a stock you can say there’s a great expression in. Well it doesn’t act well. People don’t like what are you doing. The stock is a stock. It doesn’t actually it doesn’t. But people get it in sports. Why do you think take a picture. He throws them. They get him out.
Carter Worth: You shouldn’t have thrown that pitch. This is a top athlete. He could put that thing anywhere he wants. Why did he throw that pitch? And that was you. You just always want to favor something that is performing better than other choices. Except if it’s too good, which we’ve talked about when it’s up.
Caroline Woods: On a roll. Yeah, but you know, consumer discretionary hadn’t been performing well. Consumer discretionary is doing quite well right now.
Carter Worth: Well remember that sector has weightings. Yeah. Amazon and Tesla and Home Depot (HD) are about 30%.
Caroline Woods: So are there any areas outside of Amazon.
Carter Worth: Well Starbucks (SBUX) for instance I think that’s an excellent setup. That’s again characteristics that are desirable here. It is not succumbing to the general market pressure that we see right here versus, a lot of the things like Ralph Lauren (RL) or Williams-Sonoma (WSM), all of which are are sort of rolled and are not acting well. And I wouldn’t do any of those.
Caroline Woods: Broadening it out and just taking a look at the broader market. It felt like a rough month. It’s been a rough stretch, but if you look, the S&P is only down about 3.5% in November. The Nasdaq only down about 4.5%. I mean, significant but not all that bad. Do you think that there’s more weakness to come?
Carter Worth: I would think so.
Caroline Woods: Why?
Carter Worth: So it’s about market structure. The market has pulled off a perfect magic trick. It’s been sideways for six months. And yet under the surface these like caterpillar down 50 while stocks are other stocks are up and to the right like a Costco. But again the the principal of the market. The way we study the market, the weak form is to look at the chart of the market.
Carter Worth: But the prince was the parts composed. The whole the whole comprises the parts. Right. And so the whole the S&P 500 comprises 500 constituents. The team comprises 60 athletes, right. And so forth. And so the way we try to figure out the market is to figure out the parts, to look at the constituents and have their behaving, even though the market, as you say, is basically unchanged, it’s only down a couple of percent as where it was in June.
Carter Worth: The ones that are damaged are really damaged and you don’t repair from damage quickly. It takes time, and the ones that have been the recipient of the money flow out are again saturated sponges. So the is a little bit of a checkmate here for the market to go up. I mean, the market doesn’t go up or down. The stocks go up or down.
Carter Worth: And then the index moves accordingly. Either the ones that have ricocheted and up 2,030% have to get even steeper. Even more expensive, Costco has to go to 60 times and Walmart and so forth. I don’t think that’s likely or the ones that are deeply damaged. Nvidia (NVDA) have to all bounce, and I think there are case by case, but those are trades.
Carter Worth: That’s not an enduring phenomenon. The market structure is worse, even though it’s unchanged by virtue of we have things that are now over owned and we have things that are badly damaged, bleeding from the neck that don’t quickly get out of that mess.
Caroline Woods: So the S&P 500 is trading around 7300 right now, a little higher than that. We’ve heard price targets at year end as high as 8000 8100. Do you have a downside price target on.
Carter Worth: This price? That’s a convention on Wall Street that only began in the last 20, 30 years. When I first started, they didn’t really have that. And it’s a comfort blanket people wanted to. Where do you think of it? Who cares? What do you think? Or if you’re just fastening the S&P? So here’s the thing. Strategists as long as they’ve been tracked, this goes about to about, the late 1990s strategist as a group, you’re talking about every major Wall Street firm from Goldman Sachs (GS) and Morgan Stanley (MS) at Barclays (BCS) to Merrill Lynch to Bank of America (BAC), have never once called for a down there in the market.
Carter Worth: So what is the point of price target? There are no point. Markets are. It’s called the sell side for a reason. They’re selling okay. So for you I’m just going to make a point so that they the street says it will be up every year because you just introduce like you’ve heard price targets I’m sure you have. They’re always bullish.
Carter Worth: No one ever thinks is going down. This is the problem with that whole thing because no one wants to hear that. It’s like.
Caroline Woods: Well, have you been bearish the past few years? You would have been wrong.
Carter Worth: But but the point is that that’s a convention that is useless. It doesn’t. It feels you think it’s going 8000 based on what. So let’s keep going with it because it’s very important for anyone. So the strategist he’s going to say he’s going to be this man. This one is going to say I went and did the earnings for all 500 companies.
Carter Worth: And then I figure out what those are going to be, which is very hard to do, figure out the future earnings. And then I figured out what you should pay for them, because I can figure out where the ten year yield is going to be. And I built my dividend income on my, my and I collectively determined that the S&P will earn this and therefore the price, please.
Carter Worth: I mean, it’s all a game. And I used to do that as a as a South Side strategist before doing charts. My hunch is to answer your question, though, but first, to disabuse the notion of price targets. You’ve heard a lot of them. I’m sure you have their nonsense. I think the market will be lower between now and year end.
Caroline Woods: How much lower? What’s your downside price target? No, but I mean.
Carter Worth: So how much. Why can’t we go down ten. Another 12.
Caroline Woods: So correction versus bear market.
Carter Worth: Well just I mean a lot of stocks are in bear markets. I mean if you look at the constituent S&P I mean you’re talking about 30, 3,540% have dropped 20%.
Caroline Woods: Right. So would you say this is a bear market?
Carter Worth: I think that this will I think the odds of this getting worse into the tune of not just 10 or 12, but worse are much higher than getting out of it. Now let me we just did a poll. So will the market make new highs by the end of the year? 30 sessions left. This was a 72% of institutional respondents said yes.
Carter Worth: Now I’m not talking about just pure play around. These are CIO’s are the biggest mutual fund copies, hedge funds, pension plans, endowments, mutual funds, long only they’re bullish. I don’t I don’t think that’s what’s going to happen.
Caroline Woods: But where will that money go? Because you’re saying basically the sponge is already full for the trade, so it doesn’t sound like you think it will go into tech with this kind of equal weight rating, where do you think it will sit in cash?
Carter Worth: Well, that’s always the issue. Where does money ever leave the market? The the market has changed in its structure on one for instance, the retail broker, whether they call them a stockbroker, they change for their registered rep. They changed the names in these days. No. No one trades anymore, right. You’re not allowed to even almost. They don’t want that don’t want get commissions charged.
Carter Worth: Want to take their asset gatherers. Right. Which is I understand it’s a business. It’s good for the firm. And then they place that money. And so the job is to get people to make that contribution every month. Then does the doctor, whoever it is, right, the lawyer. And that part is almost an unstoppable force. It would take something quite serious to stop that virtuous circle where you were just always putting in and always putting in, always putting.
Carter Worth: My 401 K and market participation house open is very high, but markets do have periods where people do leave the market, as you say. I guess go to cash because they’re not going to literally go to cash and put it there underneath the mattress, but, you know, not have it invest it. Well, that’s happened many times in history.
Carter Worth: And why can’t that happen on a more increasing basis right now? I would think so.
Caroline Woods: Are you sitting in cash?
Carter Worth: Well, I have let me tell you what I do. I’m very, very straightforward. I have real estate and all the city I have very small. I only really I’ve never had a long term tax gain. How about that I traded okay. So I don’t buy an all. That’s fine. That’s what you have to know who you are. So I trade and it’s almost invariably small cap dynamic exciting things where I could wow this could go from 17 to 32.
Carter Worth: This could go from 7 to 950. And so I have a lot of those. I do it all the time. I’m very active because that’s my passion, that’s my love, and that’s my job. Right. It’s based solely on the thing I do. I again, I’ve never had a long term gain. So the answer is I don’t invest, I trade, I’m a speculator.
Caroline Woods: So for everyone listening who does invest the takeaway for them.
Carter Worth: Know who you are. If you’re going to be long term, be long term, right. If you’re going to be a trader, be a trader.
Caroline Woods: But if you’re going to be long term thinking that the market now, if they, you know, believe you and that the market could fall 10 or 12% from here, should they be making any big changes?
Carter Worth: Remember the people that by and hold don’t don’t ever make changes. They just they’re just sitting there and they’re doing other things right. A lot of people don’t even. I haven’t looked at my my statements in 3 or 4 months. That’s great. Don’t look because over time markets go up. Seven years out of ten, the economy expands. They’re they’re more razors sold, more babies.
Carter Worth: And it just all is an excellent way forward. But if you are trying to have a little bit of, being dynamic and a little bit of in and out and a little bit at a minimum, if you’re generally lonely, sell some calls against your long positions or, or trim.
Caroline Woods: All right. Just finally, best chart in the market right now.
Carter Worth: Best chart a large cap stocks I’d go with John Deere.
Caroline Woods: John Deere okay. Worst chart you wouldn’t touch with the ten foot pole.
Carter Worth: Yeah I wouldn’t touch Nike okay.
Caroline Woods: All right. Great time to pivot to a rapid fire round of this or that. Quick questions. Quick answers, no hedging. Are you ready? Nvidia near 150: buy now or wait?
Carter Worth: Buy now.
Caroline Woods: Tech selloff. Opportunity or trap?
Carter Worth: Trap.
Caroline Woods: Semiconductors bottoming or more pain ahead.
Carter Worth: Play for a bounce.
Caroline Woods: Amazon or Microsoft. Amazon defensive stocks safe haven or crowded trade? Crowded trade. Utilities or industrials.
Carter Worth: Even money.
Caroline Woods: Buy the dip or wait for confirmation?
Carter Worth: Wait for confirmation.
Caroline Woods: S&P 500 market cap weight or equal weight?
Carter Worth: Market cap weight.
Caroline Woods: Santa Claus rally. Yes or no.
Carter Worth: No.
Caroline Woods: Stocks by year end. Higher or lower? Lower? How much lower?
Carter Worth: At least 5%.
Caroline Woods: Finish these sentences. The chart that worries me the most. That’s not Nike is.
Carter Worth: The cumulative advance-decline on the S&P.
Caroline Woods: The one stock I’d buy in a pullback is.
Carter Worth: Microsoft.
Caroline Woods: How much of a pullback.
Carter Worth: 1,012%.
Caroline Woods: From here.
Carter Worth: From here.
Caroline Woods: One word to describe how you’re feeling about the market heading into 2027.
Carter Worth: Dodgy.
Caroline Woods: And the one thing that will make you bullish is Johnson.
Carter Worth: Strength from here.
Caroline Woods: All right. That’s Carter Worth CEO and founder of Worth Charting Carter thanks so much.
Carter Worth: Thank you.
Caroline Woods: If you enjoyed this Street Talk check out our full interview with Victoria Fernandez. She thinks the market has more room to run and names the exact stocks to buy now. And don’t forget to like, subscribe and check out our community polls to share your take on the market. We want to hear from you.